


EN
Dutch Bros (BROS) After Raised Guidance And Strong Results Looks Undervalued
Dutch Bros (BROS) just paired another strong earnings update with a fresh push on expansion, lifting its full year 2026 revenue outlook and planning more new shop openings across its drive thru network.
That upbeat earnings release came after a tougher stretch for Dutch Bros shareholders, with the share price down 42.07% year to date and the 1 year total shareholder return declining 36.47% even after a 6.63% 1 day share price gain. Recent pressure has been more intense over the past quarter, where the 90 day share price return fell 27.36% and the 7 day move dropped 17.92%, hinting that investors had been reassessing risk before this latest update. Over a longer window, the 3 year total shareholder return of 33.17% versus a 5 year total shareholder return decline of 42.44% shows how momentum has shifted through different entry points as the business expanded, new guidance landed and leadership changes such as the incoming Chief Legal Officer were announced.
Scan how Dutch Bros compares with other consumer-facing growth stories by reviewing our curated list of 19 high quality undiscovered gems supported by strong fundamentals and expanding footprints.
After Dutch Bros jumped on the earnings release yet still trades at a wide discount to both analyst targets and intrinsic estimates, the real tension is simple: Is the market too harsh or are the models too generous?
Most Popular Narrative: 45% Undervalued
At a last close of $36.01 against a fair value estimate of $65.92, the analyst consensus Narrative on Simply Wall St frames Dutch Bros as meaningfully undervalued based on its long term cash generation and expansion plans, using an 8.92% discount rate to bring those future expectations back to today.
Dutch Bros continues to target aggressive national expansion toward 2,029 shops by 2029, supported by a dense real estate pipeline that management reports is already about 90% secured and at least 185 planned system openings in 2026, which could increase total revenue and aggregate earnings power as new units mature.
See why 84 investors see Dutch Bros as 45% undervalued.
Result: Fair Value of $65.92 (UNDERVALUED)
Still, the Dutch Bros story can break if wage and ingredient costs bite harder than expected, or if competitors tighten the screws on same shop sales.
Find out about the key risks to this Dutch Bros narrative.
Another View: What Dutch Bros Looks Like On P/E
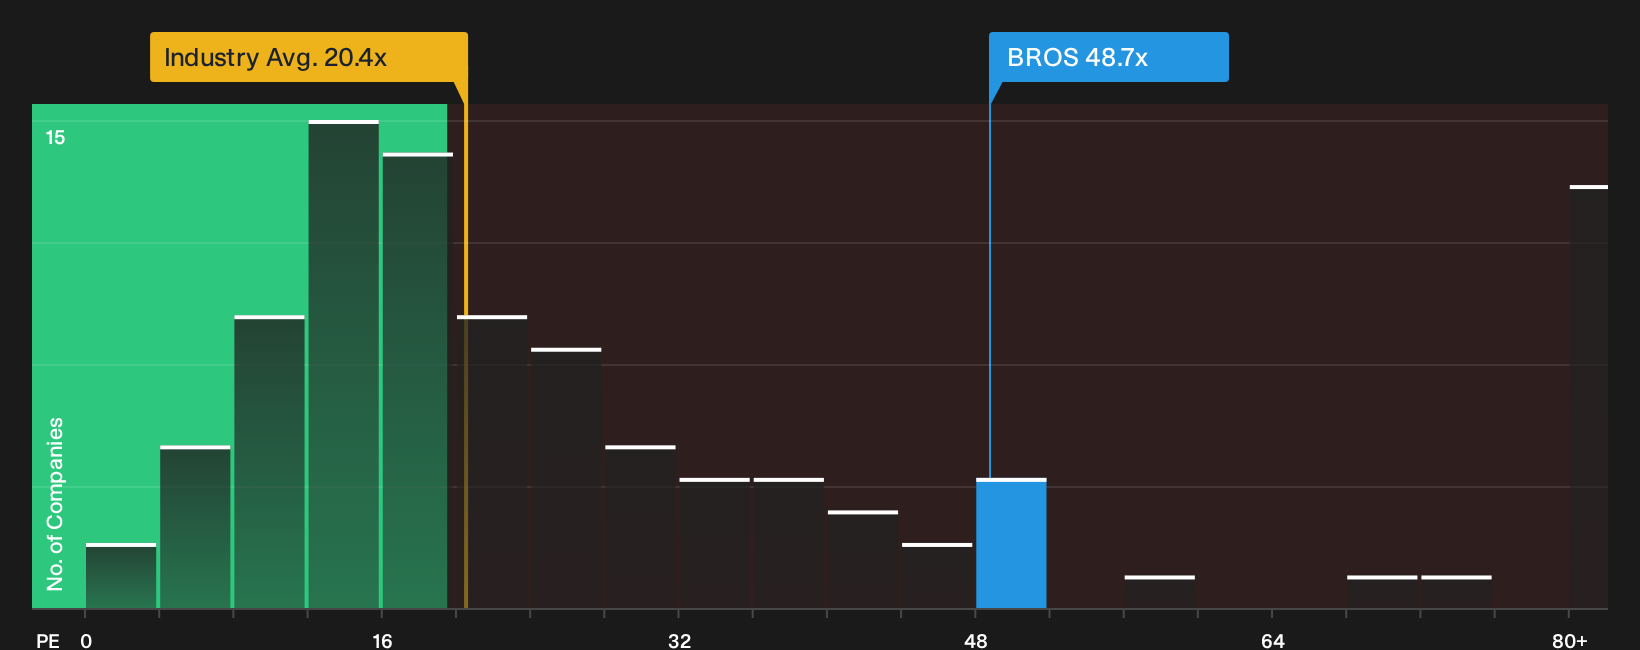
The earlier fair value work framed Dutch Bros as meaningfully undervalued. On simple earnings multiples, the picture is less generous. The stock trades on a P/E of 48.7x, compared with 20.4x for the wider US Hospitality group and a fair ratio of 28.7x that our model suggests the market could gravitate toward. That gap points to real valuation risk if enthusiasm cools or earnings assumptions shift.
To see how this earnings based view stacks up in detail against the growth story and cash flow narrative, review the See what the numbers say about this price — find out in our valuation breakdown..
For a clearer sense of where Dutch Bros sits against peers on headline valuation, study the
Next Steps
The tone of this Dutch Bros story may appear mixed so far. Review the full picture for yourself, including 3 key rewards and 1 important warning sign.
Looking for more Dutch Bros sized opportunities?
If Dutch Bros has sharpened your focus, do not stop here. Use the Simply Wall St screener to hunt for fresh ideas before others move first.
- Target quality at a discount by scanning the market for companies flagged in our 33 high quality undervalued stocks that combine solid fundamentals with appealing prices.
- Prioritise staying power by reviewing a curated list of solid balance sheet and fundamentals (25 results) so you can focus on businesses with financial strength at their core.
- Trim portfolio risk by checking out a 30 resilient stocks with low risk scores that highlights companies with more resilient profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com