


EN
How Strong Earnings Will Impact Old Dominion Freight Line Stock
- Old Dominion Freight Line reported third quarter 2026 sales of US$1.59b and net income of US$343.75m, alongside higher earnings per share compared with a year earlier, and issued fourth quarter 2026 revenue guidance of US$1.54b to US$1.58b, which management described as above normal seasonality.
- The tighter fourth quarter revenue range and comment that expected revenue sits above usual seasonal patterns highlight management’s view that Old Dominion Freight Line’s current operating efficiency, pricing discipline and capital investment program can support freight demand through year end.
- The next step is to observe how Old Dominion Freight Line’s third quarter earnings and above seasonal guidance could influence the existing investment narrative.
Scan how Old Dominion Freight Line’s above seasonal guidance compares with other freight and logistics operators using our hand picked list of solid balance sheet and fundamentals (25 results) for potential peers with resilient finances.
Old Dominion Freight Line Investment Narrative Recap
To own Old Dominion Freight Line, you need to be comfortable with a freight story built on efficiency, pricing discipline and heavy investment in the network rather than volume gains. The analyst consensus Narrative on Simply Wall St points to operating ratio improvement and yield management as key supports. The latest above seasonal revenue guidance reinforces that near term thesis rather than changing it.
The short term swing factor is whether pricing and service quality can keep offsetting softer unit volumes and higher diesel and capex. Freight softness and rising fuel remain the biggest operational risk. The new guidance tightens expectations but does not remove that pressure.
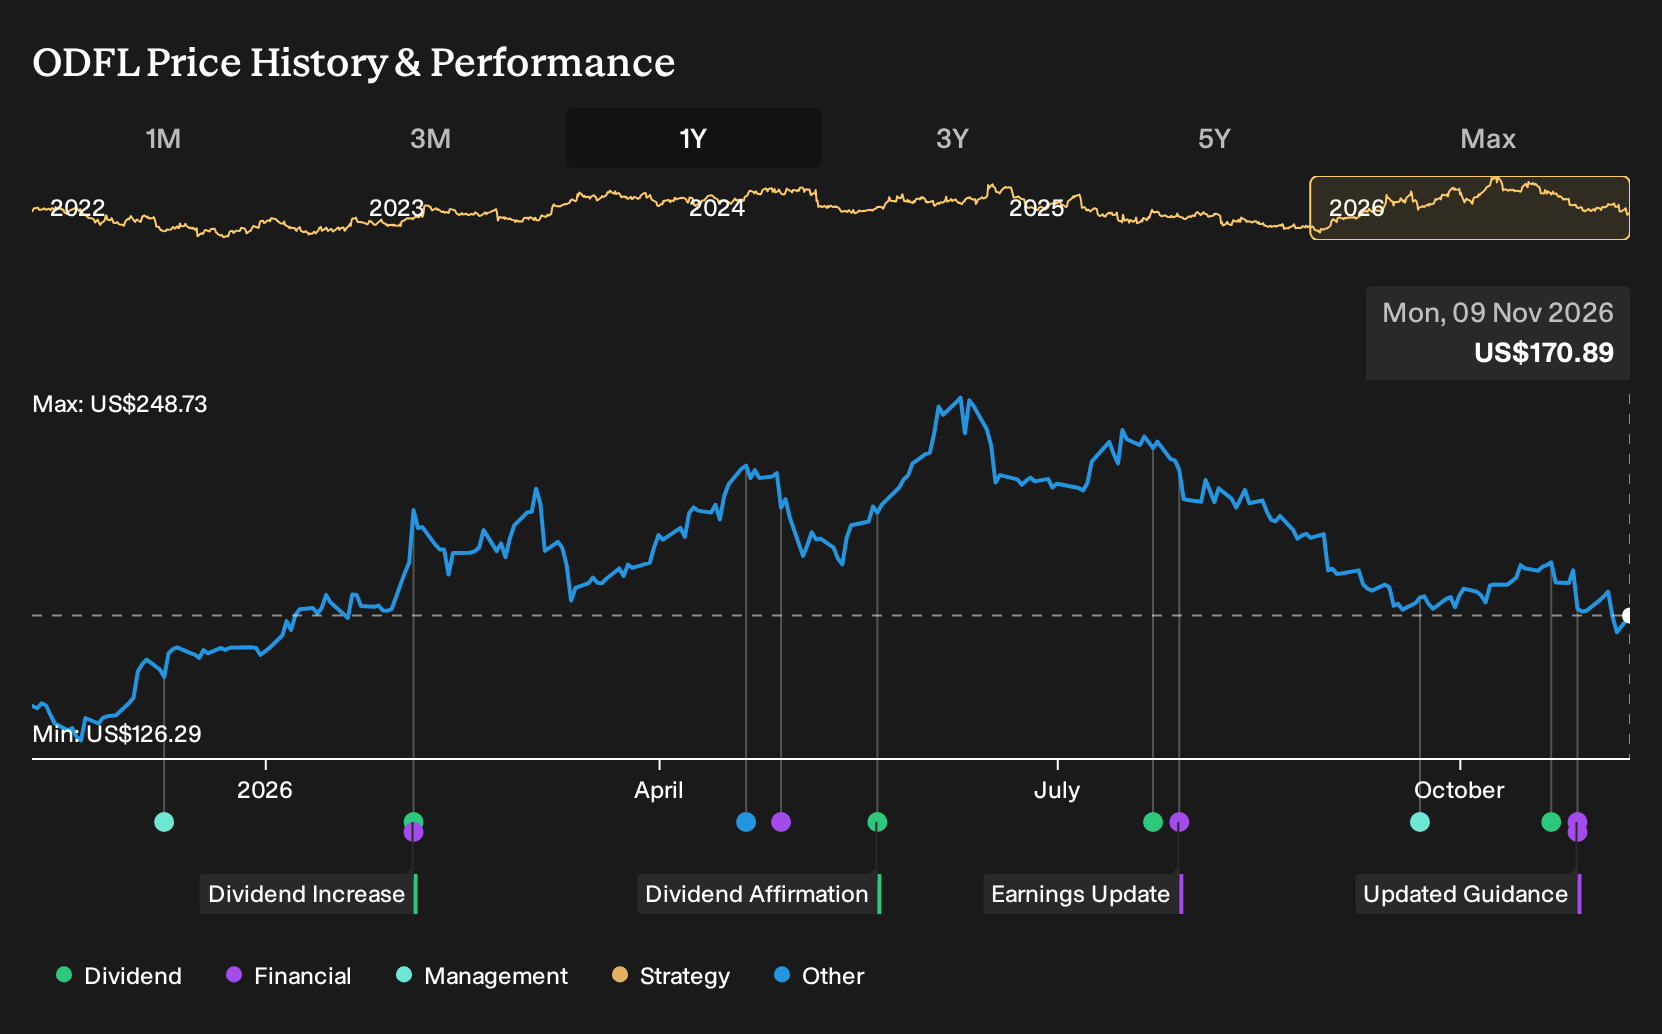
The most relevant update here is Old Dominion Freight Line’s third quarter 2026 result, with US$1.59b in sales, US$343.75m in net income and higher earnings per share than a year earlier. That print shows the efficiency and pricing focus described in the analyst consensus Narrative on Simply Wall St feeding through into reported profitability.
For catalysts, this earnings run rate gives context to the fourth quarter revenue outlook of US$1.54b to US$1.58b that management frames as above normal seasonality. Your key question is whether this level of performance can be maintained while unit volumes have been weaker than some peers and while diesel and capital spending stay elevated.
Old Dominion Freight Line’s current analyst narrative points to revenues of US$7.2b and earnings of US$1.6b by 2029. This is built on an assumed 7.5% yearly increase in revenue and an earnings uplift of about US$400m from US$1.2b today to the forecast consensus level in that same year.
Uncover how Old Dominion Freight Line's fair value indicates a 26% potential upside to its current price.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Old Dominion Freight Line’s excess service center capacity as a potential upside swing factor. Before this earnings beat and above seasonal guidance, they were already pencilling in revenues of about US$7.9b and earnings of US$1.8b by 2029. As fresh data lands, those narratives are likely to evolve.
Explore 4 other Old Dominion Freight Line fair value estimates, including one that suggests as much as 46% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Old Dominion Freight Line research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Old Dominion Freight Line. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old Dominion Freight Line's overall financial health at a glance.
Looking For More Investment Ideas Beyond Old Dominion Freight Line?
Once you have a handle on Old Dominion Freight Line, it can help to widen the lens and compare it with other businesses that match your risk tolerance and income goals. The Simply Wall St screener makes that process faster by filtering the market down to focused lists that you can review in minutes instead of hours.
- If capital preservation sits high on your list, start with resilient businesses that score well on risk by scanning our 30 resilient stocks with low risk scores.
- For investors who care most about balance sheet strength and cash flow support, check out this curated list of solid balance sheet and fundamentals (25 results) to see which companies currently clear those hurdles.
- If you are hunting for under followed quality with strong fundamentals, use the 19 high quality undiscovered gems to spot potential ideas before they become crowded trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com