


EN
Did $3.0b Buyback Just Shift Steel Dynamics (STLD) Stock Investment Narrative?
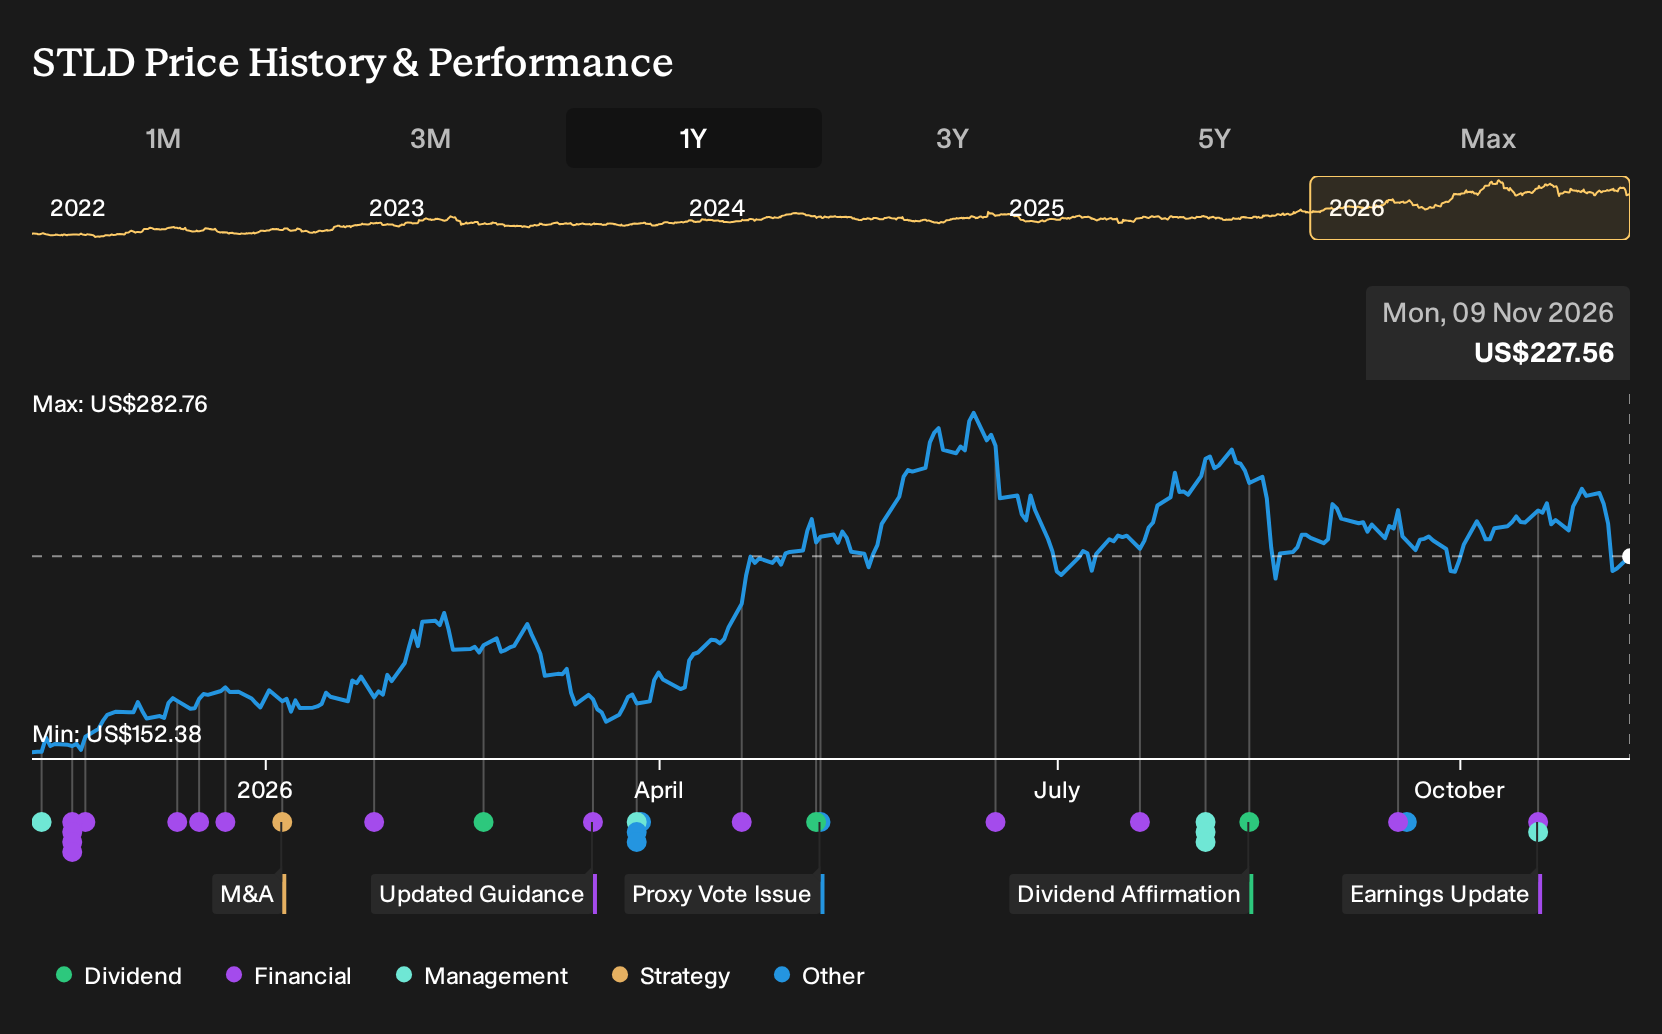
- Steel Dynamics recently reported that its board approved an additional US$3.0b share repurchase authorization, on top of a prior US$1.5b program, and declared a fourth quarter 2026 cash dividend.
- The combined use of large buybacks and ongoing dividends signals that Steel Dynamics is allocating substantial cash to shareholders alongside its heavy investment in new steel and aluminum capacity.
- We will now explore how Steel Dynamics' expanded US$3.0b repurchase authorization affects the existing investment narrative around earnings power and capital deployment.
Scan other shareholder yield plays that combine sizeable buybacks and cash returns alongside Steel Dynamics in our curated list of 6 dividend fortresses
Steel Dynamics Investment Narrative Recap
To own Steel Dynamics, you need to be comfortable with a heavy build out in aluminum and biocarbon operations while those newer platforms are still loss making. The analyst consensus Narrative on Simply Wall St leans on these units progressing toward the targeted through cycle EBITDA levels as they scale. The fresh US$3.0b buyback authorization does not change that core bet.
The biggest near term swing factor remains execution on the aluminum ramp and whether customer qualification and spreads hold up. The key risk sits in a potential cool down in construction, automotive or manufacturing demand once current non residential backlogs fade, which could pressure shipments and earnings.
The extra US$3.0b repurchase program, layered on top of the prior US$1.5b authorization, is the announcement that ties closest to this story. Management is signaling comfort using balance sheet capacity for shareholder returns while still funding projects estimated to contribute about US$1.4b of through cycle annual EBITDA, if those assets perform as outlined.
For you, the link to catalysts is straightforward. If aluminum operations move from operating losses toward the EBITDA positive target in the second half of 2026 and steel utilization around 90% is sustained, then a shrinking share count could lift per share metrics. If guidance keeps trailing expectations or end markets soften, there is room for valuation compression even with the buyback in place.
Steel Dynamics' current analyst story ties to revenues of US$24.9b and earnings of US$3.2b by 2029, built on assumed yearly top line growth of 6.6% and an earnings rise of about US$1.6b from US$1.6b today.
Uncover why Steel Dynamics' fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the extra buyback as a secondary catalyst alongside Steel Dynamics pushing for higher aluminum margins. Before this news, the bullish camp was already modeling about US$26.4b of revenue and US$4.1b of earnings by 2029, far above consensus, so those views may change as fresh information becomes available.
Explore 4 other Steel Dynamics fair value estimates, including one that suggests as much as 46% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Steel Dynamics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Steel Dynamics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Steel Dynamics' overall financial health at a glance.
Looking for more Steel Dynamics style investment ideas?
If the Steel Dynamics story has sharpened your thinking on shareholder returns and capital allocation, it can be useful to scan other businesses with different profiles but similarly clear cash flow angles.
- For investors who want potential upside with a margin of safety, review companies trading on appealing valuations and solid fundamentals through the 33 high quality undervalued stocks.
- If you care most about balance sheet strength and resilience across cycles, filter for companies with robust finances and durable operations using the list of solid balance sheet and fundamentals (25 results).
- For those who prefer to back quieter opportunities before they are widely followed, focus on financially sound smaller companies by checking the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com