


EN
Missed Out On Affiliated Managers Group's Run? Here's What Changed
If Affiliated Managers Group sat on your watchlist instead of in your portfolio, the result over the last year may feel painful to revisit. Investors who held Affiliated Managers Group over the past year are up 47.6%, including dividends. That outcome invites a simple question. Back on 9 November 2025, when analysts disagreed sharply on future P/E and alternative asset exposure, what clues in the boutique manager expansion story might have signalled that this growth mix could matter most?
If the move has made Affiliated Managers Group harder to judge, start where the gap is still open and scan 33 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On Affiliated Managers Group
Affiliated Managers Group shares cost US$259 at the start of the period, and investors had to decide which story about the business felt more realistic.
The bullish camp worked off a Fair Value of US$331, the rough price implied if its optimistic assumptions played out, built on 6.0% annual revenue growth and profit margins rising to 24.6% within three years, while the future P/E moved to 16.7x.
The bearish view anchored to a Fair Value of US$195, again a price implied by its model, assuming only 1.7% yearly revenue growth, higher 27.8% margins and a compressed future P/E of 9.8x, as alternative assets faced liquidity and regulatory risks.
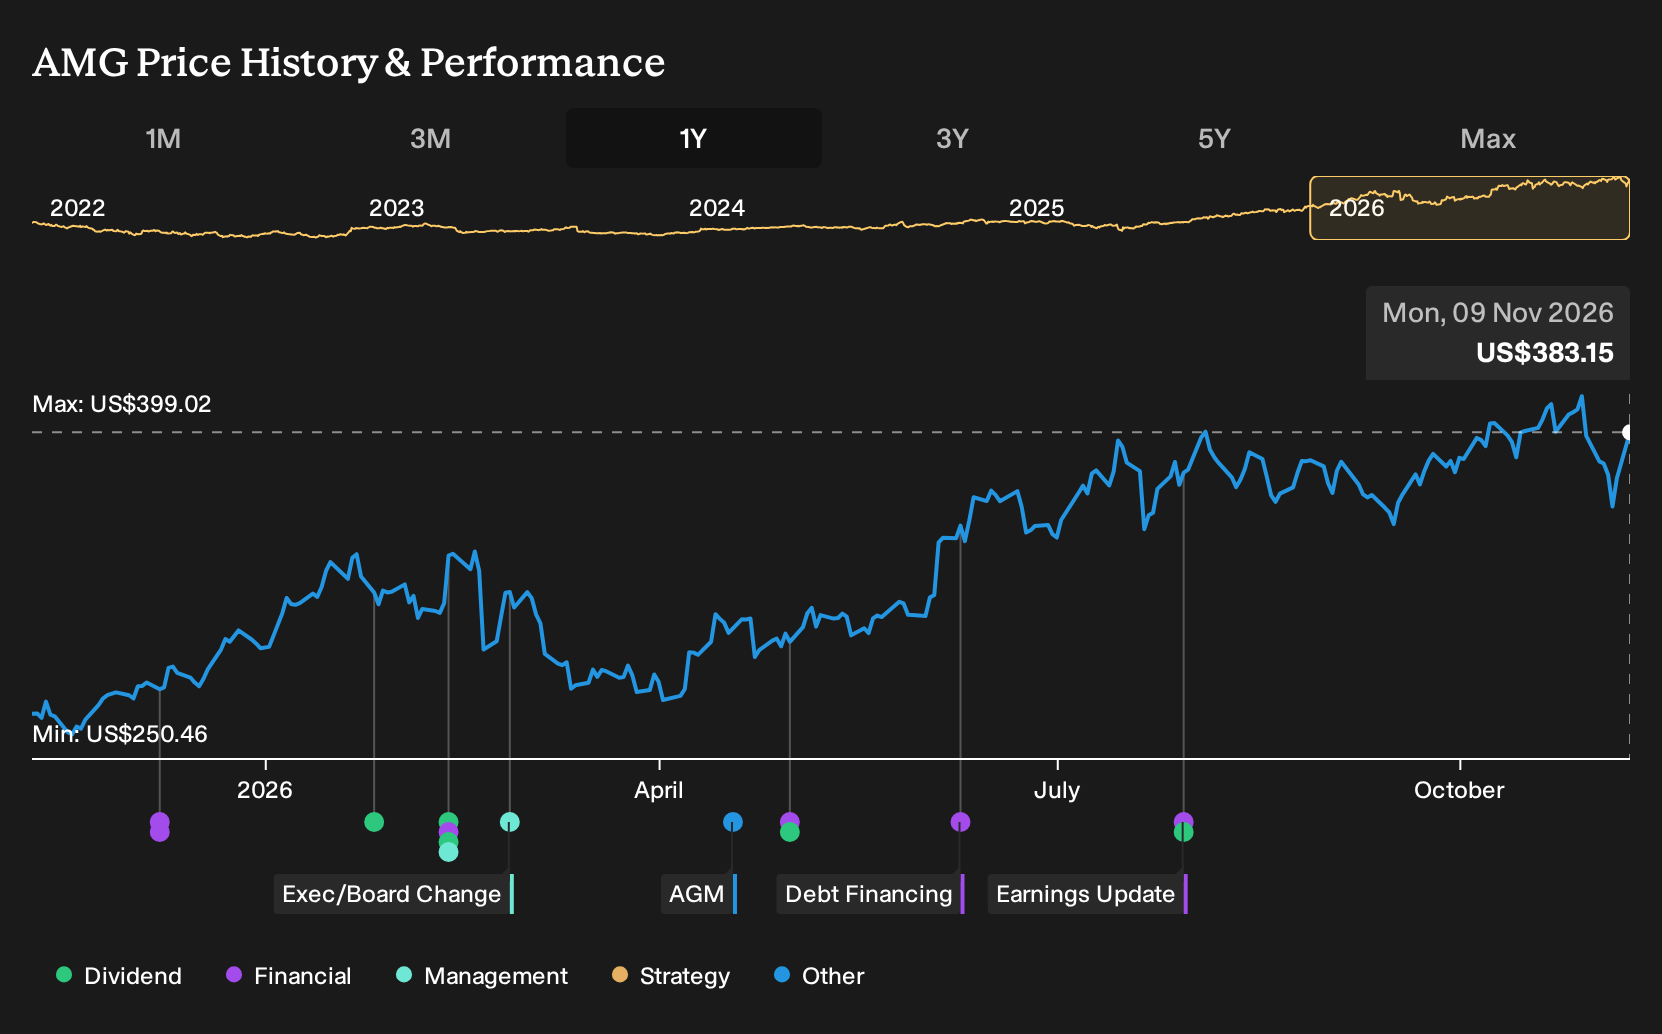
What The Results Changed For Affiliated Managers Group
The most concrete shift came from Affiliated Managers Group securing a new US$1.25b revolving credit facility. This supported the bullish story that capital for affiliate deals, buybacks and alternatives expansion would be available. Evidence on the cautious side remained live, with revenue growth, margin targets and the future P/E still model driven rather than settled. Overall, the evidence did not settle the question.
The lesson is simple. When a thesis leans on expansion and repurchases, treat committed financing lines as a key checkpoint and track how management actually uses that capacity in later filings.
What Affiliated Managers Group's Rally Already Prices In
Affiliated Managers Group trades around US$383 after a 47.6% total return over the past year, and this bearish analyst Narrative on Simply Wall St places its Fair Value below that level. The gap reflects concern that concentration in alternatives and key affiliates could tighten the margin for error.
Anyone paying today’s price is effectively assuming alternative and liquid strategies keep offsetting fee pressure and outflows from traditional products. The open question is how that assumption holds up against the Narrative’s focus on earnings concentration and ongoing pressure on active management fees.
"Although Affiliated Managers Group reports strong recent growth in alternative strategies, the continuing net outflows of $14 billion in Q2 2026 and $45 billion in 2025 from differentiated long only equities indicate that fee pressure and a mix shift away from traditional active products could still weigh on consolidated management fee revenue and limit operating leverage."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 41% below our estimate - turn a growing subsea project list into faster tieback work and extended maintenance services.
- Company 2 - 31% below our estimate - tie expanded AI capabilities directly to existing cloud subscriptions and usage-based commercial terms.
- Company 3 - 42% below our estimate - sell integrated AI computing hardware and software that large customers reserve through substantial orders.
Those are three of them. See all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com