


EN
Missed Sulzer's Run? What Holders Had To Believe
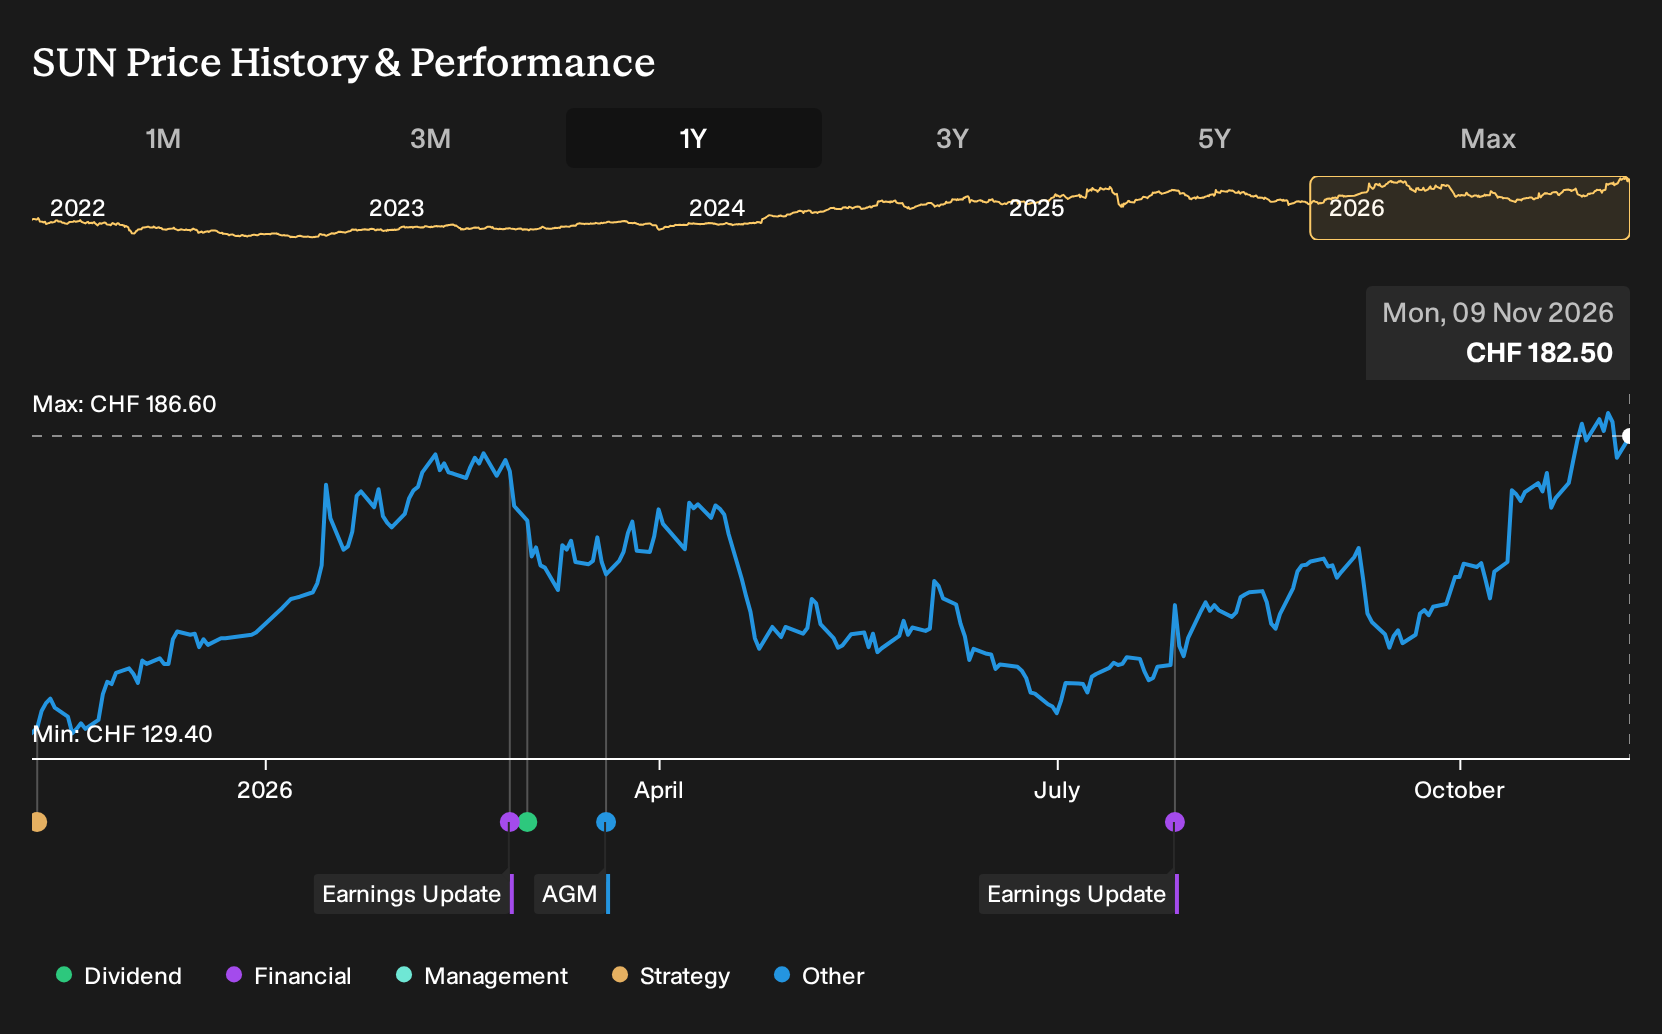
Sulzer’s year was punctuated by concrete wins, including a long-term Corporate Procurement Agreement with Aramco to supply centrifugal pumps, spare parts, and services across its global operations. For Sulzer shareholders, the return over the past year was 44.0%, including dividends. If you had been weighing a purchase before that contract was announced, what conviction about tariffs, delayed projects, and long-term demand would you have needed to press the buy button?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The move put Sulzer in the middle of this trade. Scan 91 robotics and automation stocks for other companies exposed to it.
The Two Sulzer Stories Investors Were Arguing About
The shares cost CHF128 at the start of the period, and Sulzer sat between two very different stories about tariffs, project timing, and decarbonization spending.
The bullish Narrative saw Fair Value at CHF176, 37% above the start price, built on assumptions of 3.7% revenue growth, a 9.8% profit margin, and a future P/E of 17.4x over roughly three years.
The bearish view pointed to CHF89 as Fair Value, 31% below the start price, stressing risks from Asian overcapacity, tariff pressure, and weaker refining and petrochemical demand in Chemtech’s core markets.
What The Results Changed For Sulzer’s Tariff And Demand Story
The Aramco Corporate Procurement Agreement gave Sulzer fresh backing for the bullish demand story, with a five year pump and services deal plus an option for three more years. Measured results pulled the other way. Revenue moved from CHF1,743.9m in H1 2025 to CHF1,672.6m in H1 2026, while net income and margin both rose. Overall, the evidence cut both ways.
The period turned on one simple assumption: you needed to know whether lower or delayed orders would still produce better profitability. For any similar stock, track whether net margin moves toward the thesis figure and check new contracts against that margin trend rather than just headline order size.
What Sulzer’s One Year Run Already Prices In
Sulzer shares are now CHF182 after a 44.0% gain over the past year, and this Narrative’s Fair Value sits below the current price rather than above it.
The bearish analyst Narrative on Simply Wall St argues that the current valuation leans on aftermarket strength and execution on Chemtech and cash conversion. A buyer today would be assuming those higher margins hold up, so the question is how that perspective aligns with Chemtech’s order swings and working capital strain described here.
"Although Sulzer is benefiting from higher-margin aftermarket work that now represents 62% of sales and supports group EBITDA margins above 15%, the 3.9% decline in H1 2026 order intake and weak large-project demand suggest mix alone may not offset softer volume. This could cap revenue growth and limit further earnings expansion if large CapEx orders remain slow to materialise."
One Narrative disagrees with today's price. → See where this Narrative says Sulzer should trade
Where Sulzer’s Story Points Next
Sulzer’s pumps live in refineries and petrochemical plants. Your attention might drift somewhere colder.
AI data centres burn power and turn it into heat. That heat must move out quickly or the racks shut themselves down.
One specialist quietly builds the power gear and liquid cooling hardware that lets those facilities keep running.
Its engineers work on how to pull heat off chips, route it through coolant, and keep servers in their narrow comfort zone.
If demand for that infrastructure keeps compounding, the real contest may be which supplier can keep every watt and litre under control.
That argument has a Narrative and a number behind it. → See the company one Narrative values 104% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com