


EN
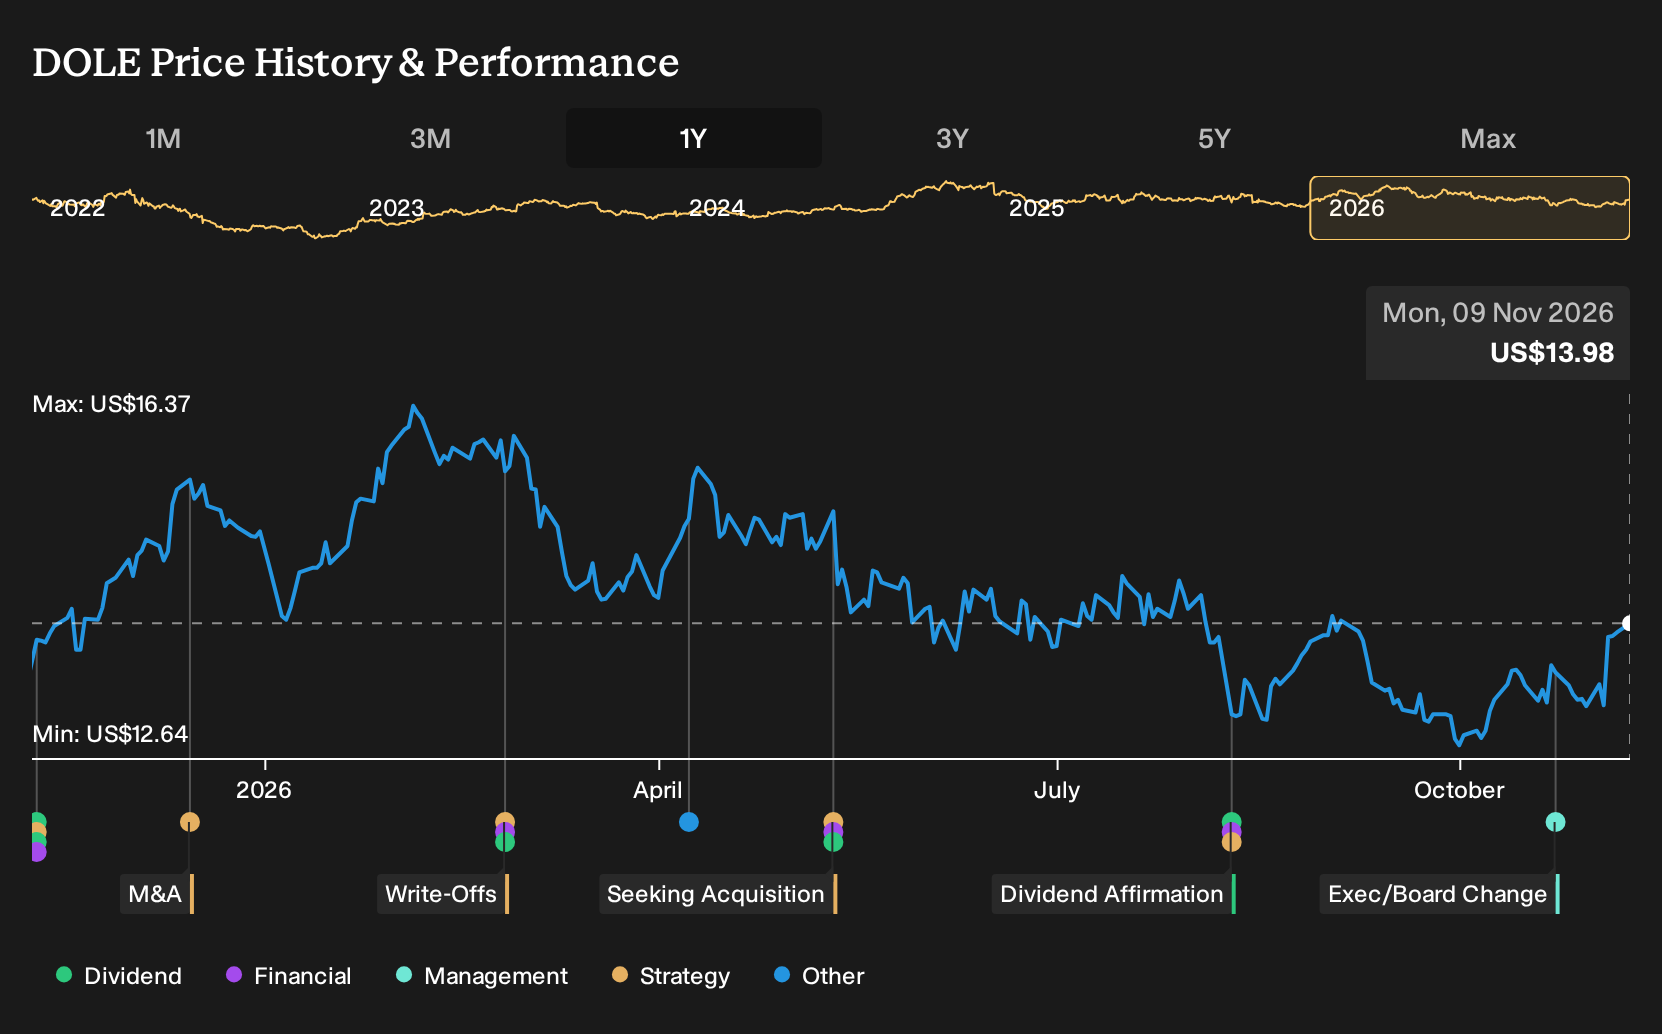
Did Outlook Cut Just Shift Dole Stock's Investment Narrative?
- Dole reported third quarter 2026 sales of US$2,366.18 million and net income of US$38.51 million, with earnings per share of US$0.41. The company also reduced its adjusted EBITDA outlook, citing higher fuel, shipping, and input costs, as well as weather related supply issues.
- Investors also saw Dole generate substantial free cash flow, trim net debt, record lower impairment charges than a year ago, and affirm a US$0.085 quarterly dividend for shareholders of record on December 16, 2026.
- We will look at how Dole's mixed earnings and lowered adjusted EBITDA outlook reshape the investment narrative around its cost pressures.
Compare Dole's cost squeezed quarter with a curated group of companies that screen well for pricing power and balance-sheet strength using our list of solid balance sheet and fundamentals (25 results).
Dole Investment Narrative Recap
To own Dole, you need to believe the fresh produce platform and diversification outlined in the analyst consensus Narrative on Simply Wall St can matter more than cost and legal headwinds. The latest quarter shows that story is still tied to execution. Sales and net income for both the quarter and nine months are solid in absolute terms, yet margins remain thin and exposed.
The key short term catalyst is whether cost management and logistics projects can offset higher fuel, shipping and input costs that led to the adjusted EBITDA outlook cut. The biggest immediate risk is that these pressures, along with any legal or weather issues, keep profitability below what that thesis requires.
The most relevant fresh data point is the third quarter 2026 earnings release. Dole reported US$2,366.18 million of sales and US$38.51 million of net income for the quarter, with basic and diluted EPS of US$0.41. For the first nine months, revenue reached US$7,207.76 million with net income of US$95.79 million, again translating to basic and diluted EPS of roughly US$1.01 and US$1.00.
Those results sit alongside the lowered adjusted EBITDA outlook, which flags that cost inflation and weather related supply issues remain the swing factors for near term earnings. In that context, the smaller impairment charge and the free cash flow and deleveraging already discussed become key operational catalysts, because they influence how much flexibility Dole has if pricing or volumes come under more pressure.
Dole's outlook projects US$10.2b in revenue and US$160.6 million in earnings by 2029. That profile assumes annual revenue growth of 2.3% and an earnings increase of about US$89.8 million from current earnings of US$70.8 million.
Uncover why Dole's fair value indicates a potential upside of 25% to its current price before the gap closes.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Dole’s automation and M&A plans as a potential upside catalyst, rather than cost risk. Before this earnings cut, they were sketching out revenue of about US$10.2b and earnings of US$144.5 million by 2029. You can compare that positive outlook with your own assessment of today’s cost-squeezed update.
Explore 3 other Dole fair value estimates, including one that suggests as much as 160% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Dole research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Dole. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dole's overall financial health at a glance.
Looking For More Investment Ideas Beyond Dole?
If Dole's mix of cost pressure, cash generation and dividends has you thinking about portfolio balance, it can help to line it up against other businesses with different risk and return profiles. The Simply Wall St Screener lets you do that quickly by filtering for the type of financial traits you want to focus on next.
- If you want potential mispricing with solid fundamentals, start by checking a curated 33 high quality undervalued stocks that combine quality balance sheets with attractive valuations.
- If income resilience matters most to you, scan for companies that resemble robust income payers by using the 6 dividend fortresses to see which stocks currently offer higher yields.
- If capital preservation is your priority, narrow your search to businesses with steadier profiles by running the 30 resilient stocks with low risk scores that filters for companies with lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com