


EN
Is Quarterly Net Loss Altering The Investment Case For Credit Acceptance (CACC)?
- Credit Acceptance reported third quarter 2026 revenue of US$594.6 million and a net loss of US$56.6 million, compared with a profit a year earlier, alongside weaker earnings metrics for the first nine months of the year.
- The shift from income to loss, combined with reduced collection expectations and fresh legal scrutiny, highlights mounting pressure on Credit Acceptance's subprime auto lending model and how it manages credit risk and compliance costs.
- We will examine how Credit Acceptance's investment narrative is being tested by the swing to a quarterly net loss and weaker collections.
Compare Credit Acceptance's stressed profile with other lenders by scanning 30 resilient stocks with low risk scores, which aims to pair resilient balance sheets with tighter risk controls.
Credit Acceptance Investment Narrative Recap
For Credit Acceptance, the investment case described in the analyst consensus Narrative on Simply Wall St focuses on a data and AI driven subprime auto model that can still produce solid originations and acceptable returns despite tighter rules and scrutiny. The recent swing to a US$56.6 million quarterly net loss challenges confidence in near term earnings resilience and credit performance.
The key short term catalyst is whether AI enabled underwriting, collections and dealer tools can stabilise loss trends while complying with new settlement terms. The biggest current risk sits in legal and regulatory pressure, which could keep funding more constrained and compress pricing if collection expectations keep being revised lower.
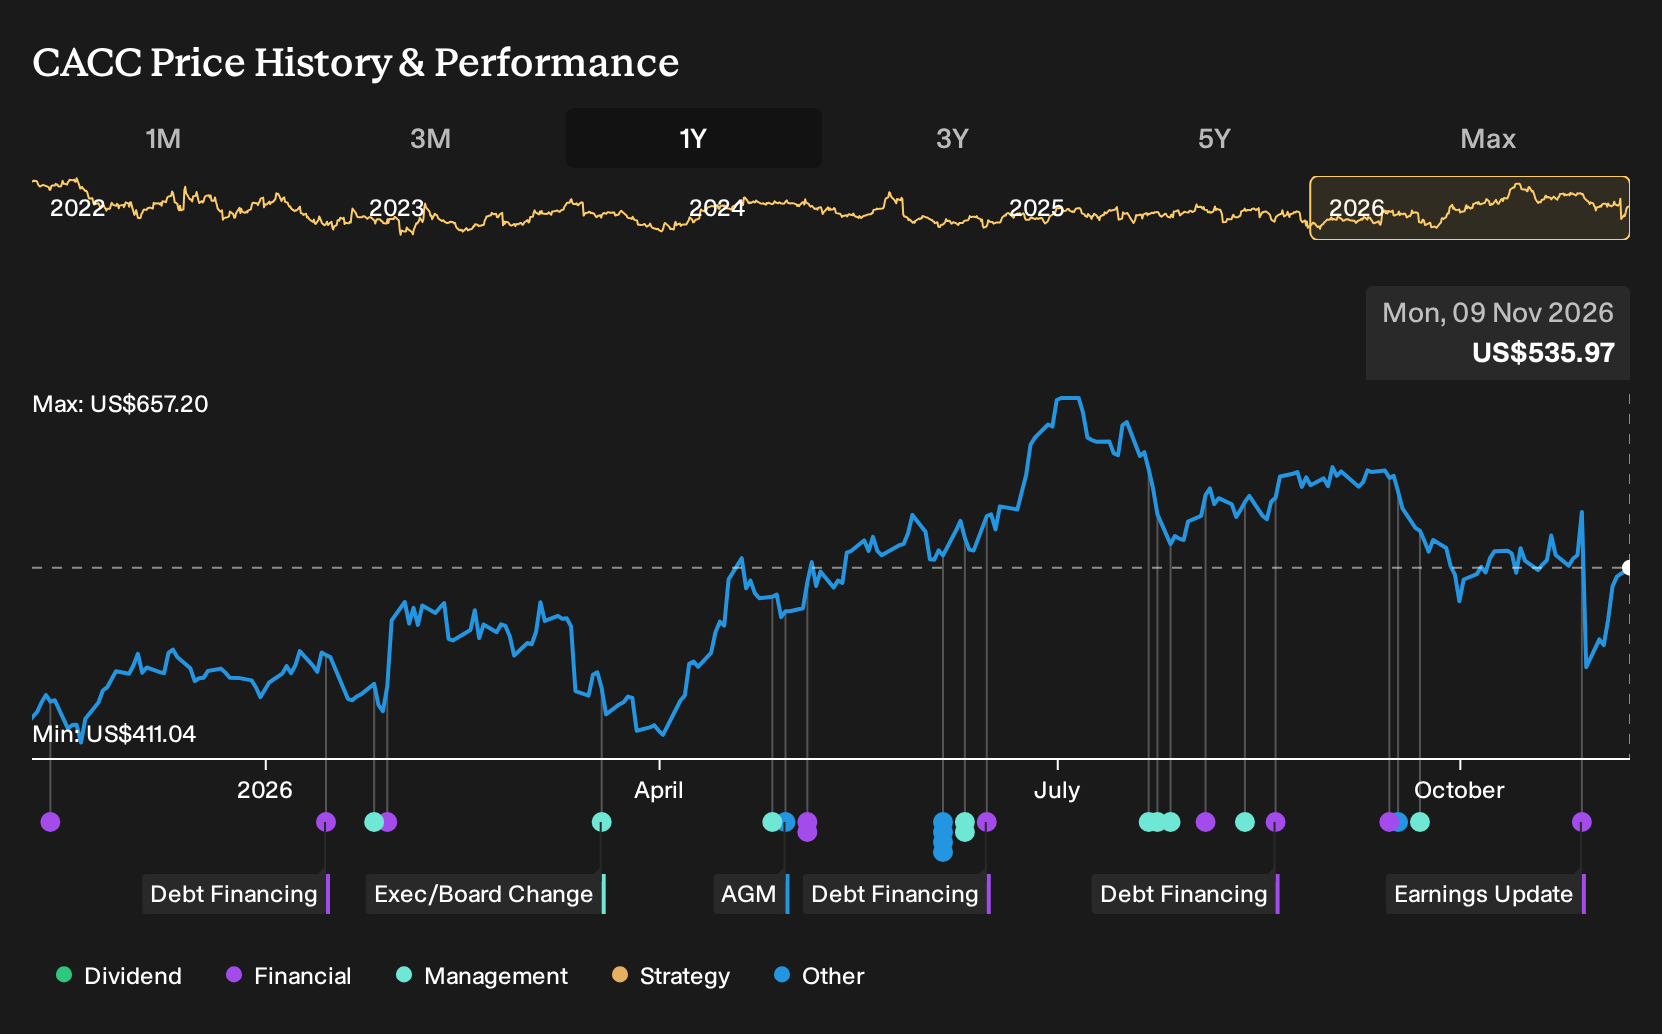
The third quarter 2026 earnings release is the key update tying all of this together. Revenue for the quarter was US$594.6 million, with a reported net loss of US$56.6 million and basic and diluted loss per share of US$5.43 from continuing operations. That compares with profit a year earlier, so you are seeing pressure fall through to the income statement.
Across the first nine months of 2026, revenue reached US$1,762 million and net income came in at US$215.1 million, with basic earnings per share of US$20.40 and diluted earnings per share of US$19.92 from continuing operations. For anyone watching Credit Acceptance, this set of numbers sits directly against the catalysts in the analyst consensus Narrative on Simply Wall St, because it tests how quickly the AI powered model and dealer network can offset legal costs, weaker collections and any funding friction.
What The Current Assumptions Mean For Credit Acceptance
Credit Acceptance's analyst narrative points to forecast revenue of US$3.5b and earnings of US$286.3 million by 2029. That profile assumes revenue growth of 47.9% per year and an earnings decrease of US$50.8 million from current earnings of US$337.1 million.
Uncover how Credit Acceptance's fair value indicates a 4% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fair value views from the Simply Wall St Community span just two retail investors so far, with estimates between US$350.49 and US$556.67 for Credit Acceptance. You are seeing those opinions set before the recent quarterly loss, multistate settlements and lawsuit, so fresh legal and funding risks could reshape how future contributors frame performance and valuation.
Explore another Credit Acceptance fair value estimate, including one that suggests it could be valued at $556.67.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Credit Acceptance research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Credit Acceptance. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Credit Acceptance's overall financial health at a glance.
Looking for more Credit Acceptance alternatives?
If Credit Acceptance's risk profile feels too concentrated, broaden your watchlist with lenders and financial stocks that match your own comfort level on balance sheet strength, pricing power, and income potential using the Simply Wall St Screener.
- For investors who care most about resilience, start with a list of solid balance sheet and fundamentals (25 results) that can offer more predictable fundamentals through different parts of the cycle.
- If value is your priority, scan a 33 high quality undervalued stocks that currently combine quality fundamentals with prices that sit below their estimated worth.
- For those focused on income, you might prefer a 6 dividend fortresses that can support higher yields while still maintaining underlying financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com