


EN
Did Net Inflows Just Shift Ashmore Group's (LSE:ASHM) Investment Narrative?
- Ashmore Group reported FY 2026 net inflows of $2.7b into its emerging market strategies, supported by about $12.5b of subscriptions and the lowest redemptions in over a decade.
- The return of client demand for emerging market allocations gives Ashmore Group a larger base of fee-earning assets to work with across equities, fixed income and alternatives.
- This article will examine how Ashmore Group’s renewed net inflows could reshape the investment narrative around its fee-based earnings power.
Ashmore Group Investment Narrative Recap
To own Ashmore Group, you need to believe that its emerging market focus, mix shift toward higher fee strategies and long term client relationships can convert rising assets under management into steadier fee income. The key near term swing factor is whether the current phase of net inflows holds up long enough to offset fee margin pressure and softer performance fees.
The biggest risk right now is that higher AUM again fails to feed through to adjusted net revenue, as already happened in FY 2026 when weaker performance fees and currency effects hit income. Any further squeeze on the roughly 34 bps blended management fee margin would add pressure, especially if seed capital gains become less supportive.
The analyst consensus narrative on Simply Wall St frames one major operational catalyst around client activity. Rising FY 2026 subscriptions of about $12.5b and the lowest redemptions in over a decade give Ashmore Group more fee earning assets to work with across equities, fixed income and alternatives. This matters directly for near term earnings quality and consistency.
That same view also highlights how mix and seed capital returns shape the outlook. Growth in equities and alternatives, now around 19% of group AUM, plus roughly £82.5m of seed gains in FY 2026, has supported margins and profit. For shareholders, the execution question is whether Ashmore Group can lean more on recurring management fees and less on volatile, non cash seed driven contributions.
Ashmore Group's current analyst storyline points to forecast revenue of £189.9 million and consensus earnings of £74.6 million by 2029, based on an assumed 10.9% yearly revenue growth rate and a move in earnings from £103.3 million today to £74.6 million. This implies an earnings decline of about £28.7 million over that period.
Uncover why Ashmore Group's fair value indicates it is roughly in line with its current price.
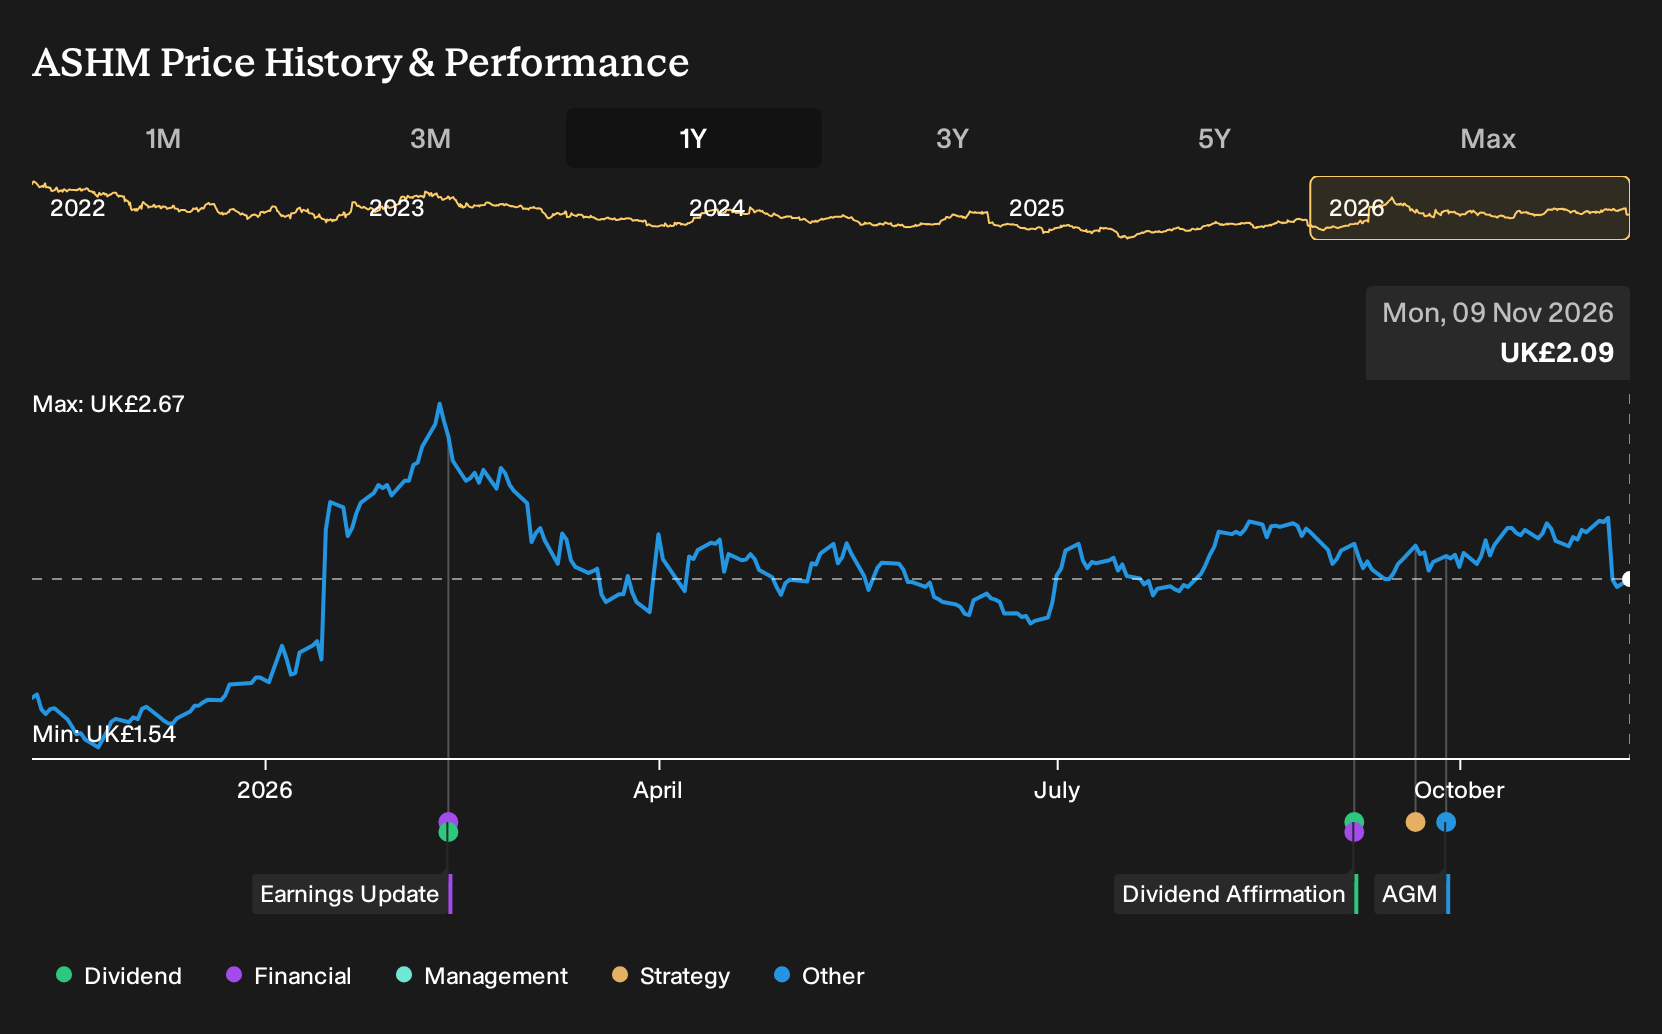
Exploring Other Perspectives
One alternate view hangs on Ashmore Group’s seed capital engine. The most optimistic analysts were pencilling in about £202.5 million of revenue and £86.7 million of earnings by 2029 before this inflow news, assuming that recycling those seed gains supports richer profit streams. You can compare that upbeat story with more cautious forecasts and decide which feels closer to your own expectations.
Explore 5 other Ashmore Group fair value estimates, including one that suggests as much as 62% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ashmore Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ashmore Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ashmore Group's overall financial health at a glance.
Looking for more Ashmore Group style investment ideas?
If the Ashmore Group story has you thinking more broadly about where to put fresh capital to work, it can help to scan a wider field of listed businesses with different risk and income profiles.
- For investors who want potential upside with tighter risk controls, consider starting with a curated list of companies that screen as relatively resilient, using the 4 resilient stocks with low risk scores as your jumping off point.
- If income is front of mind and you care about regular cash returns, you can zero in on higher yielding payers by reviewing the 6 dividend fortresses that currently clear the Simply Wall St filters.
- Those hunting for under the radar opportunities can cast a wider net across less followed tickers by running through the 5 high quality undiscovered gems and seeing which stories deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com