


EN
Upstart Holdings (UPST) Lifts 2026 Revenue Guidance, Is It Still 42% Below Fair Value?
What Upstart Holdings’ Latest Earnings Mean For Investors
Upstart Holdings (UPST) just released third quarter 2026 results, reporting net income of US$36.58 million and higher earnings per share than a year earlier, alongside fresh full year revenue guidance.
Management now expects about US$1.35b in revenue for 2026, and the latest figures give you a concrete snapshot of how the AI lending platform is converting its model into reported profit.
The earnings release and updated guidance arrived after a mixed year for Upstart Holdings’ stock, with the share price down 51.46% year to date and the 1 year total shareholder return declining 42.61%, even as the 3 year total shareholder return is slightly positive at 1.88%.
Short term momentum has started to firm up, with a 1 day share price return of 1.64% and a 7 day share price return of 4.41%. However, the 30 day and 90 day share price returns are still down 7.68% and 25.56% as investors reassess risk around the business model and its valuation after a long slide that leaves the stock at US$22.25 today.
Look beyond Upstart Holdings and see how other AI focused lenders and fintech platforms are priced with our hand picked 42 profitable AI stocks that aren't just burning cash.
After a sharp multi year drawdown and a small recent bounce, Upstart Holdings now poses a simple question to potential new investors: Does the risk still justify stepping in at US$22.25?
Most Popular Narrative: 42% Undervalued
On the analyst consensus narrative on Simply Wall St, Upstart Holdings screens as undervalued, with a fair value of about $38.38 against the latest $22.25 close. This frames the recent earnings beat inside a wider long term thesis built on AI underwriting, product breadth and committed funding capacity, using a 9.63% discount rate.
The implementation of Model 19, featuring the Payment Transition Model, remains central to Upstart Holdings’ effort to improve underwriting accuracy. This is likely to support higher approval rates and more resilient credit performance, with potential benefits for revenue and net margins as newer vintages season.
See why 145 investors see Upstart Holdings as 42% undervalued.
Result: Fair Value of $38.38 (UNDERVALUED)
Still, the bullish Upstart Holdings story relies heavily on AI model accuracy in a tougher credit backdrop, where higher default risk or weaker underwriting could quickly unsettle funding partners.
Find out about the key risks to this Upstart Holdings narrative.
Another View On Upstart Holdings’ Valuation
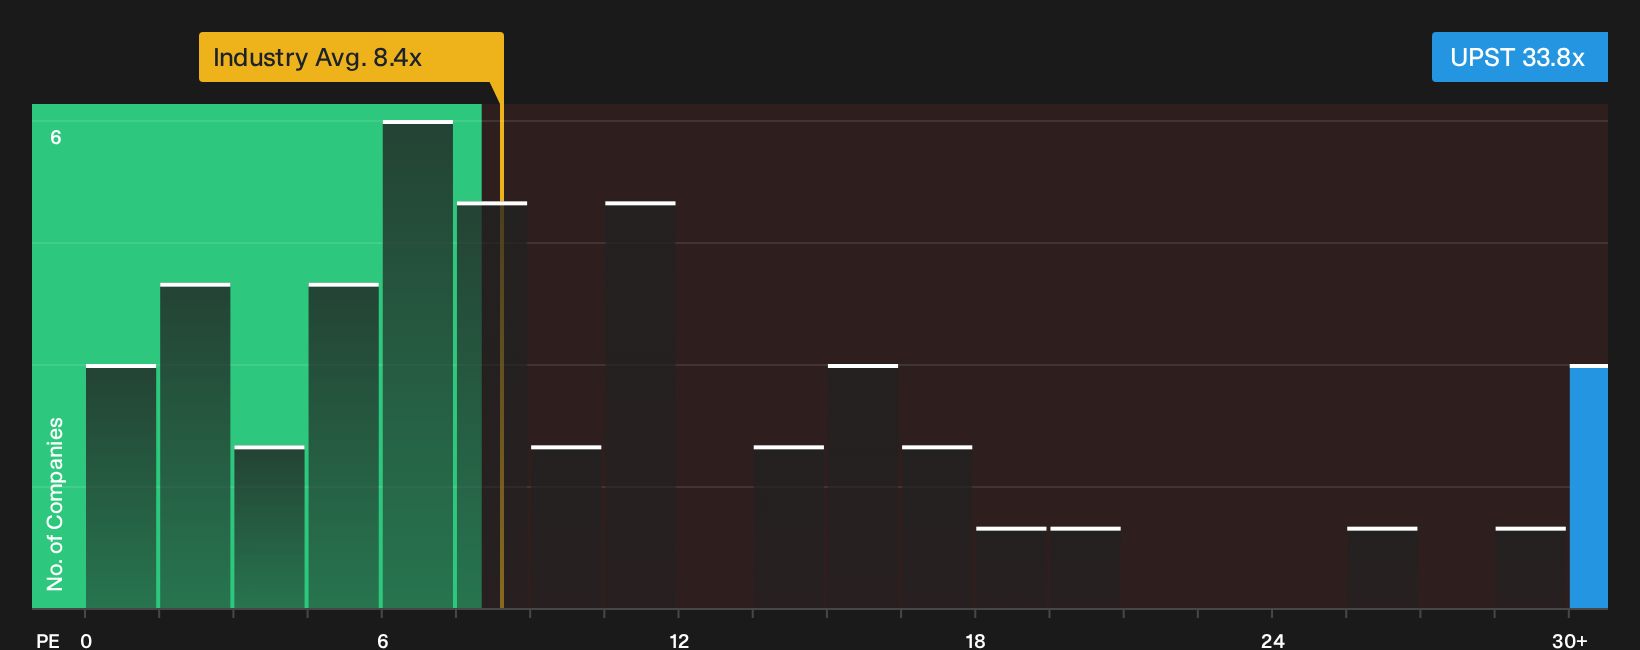
The first story around Upstart Holdings leans heavily on a discounted cash flow style fair value of about $38.38. Using a simpler earnings lens, the picture shifts. UPST trades on a P/E of 33.8x compared with a fair ratio of 24.1x, its peer group on 10.7x and the US Consumer Finance industry on 8.4x. That gap points to meaningful valuation risk if sentiment or forecasts cool off. Which yardstick do you trust more when the numbers disagree?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data can be useful if you use them. Act while the latest earnings are still fresh and build your own take around the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Upstart Holdings?
Do not stop with one stock. Broaden your watchlist and pressure test your thesis by comparing Upstart Holdings with other opportunities that fit different roles in your portfolio.
- Target cash flow resilience by scanning a list of solid balance sheet and fundamentals (25 results) that can better handle tough credit conditions and funding swings.
- Hunt for mispriced potential and line up alternatives to Upstart Holdings by reviewing a curated 19 high quality undiscovered gems before the crowd catches on.
- Dial back portfolio stress and balance higher risk bets like AI lending with a 30 resilient stocks with low risk scores that focuses on resilience first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com