


EN
Does Recurring Services Growth Change The Bull Case For Currys Stock (LSE:CURY)?
- Currys reported that independent non executive director Magdalena Gerger stepped down from the board and its Remuneration and Nominations Committees, with the search for a new non executive already underway.
- The business continues to lean into higher margin recurring services, with credit, installations, connectivity and repairs already contributing over 30% of UK revenue and expanding faster than product sales.
- We will look at how Currys' investment narrative is shaped by this recurring services expansion and the evolving board composition.
Scan beyond Currys and compare its services focused model with other retailers that lean on recurring income using a curated list of 5 high quality undiscovered gems.
Currys Investment Narrative Recap
To own Currys, you need to believe the shift toward services keeps reshaping the business. Credit, installations, connectivity and repairs already make up over 30% of UK revenue and are growing faster than product sales, so the key short term catalyst is continued customer uptake that supports EBIT margins despite wage and tax headwinds.
The biggest risk right now sits in execution. Higher labour costs of £32m this year and the delayed UK cloud migration with about £40m of extra cash outflows can still squeeze free cash flow. The planned board change looks manageable and does not materially alter these near term drivers.
The analyst consensus narrative on Simply Wall St centres on recurring services growth, cost efficiency and B2B expansion. That ties directly to Currys focus on higher margin income streams such as FlexPay credit and iD Mobile connectivity, which analysts see as important for earnings resilience if Nordic market share pressure or wage costs weigh on profits.
Against that backdrop, the cloud migration delay already flagged as a risk becomes highly relevant. Dual running costs and extra cash demands raise the bar for those same services and B2B initiatives to support EBIT and free cash flow. Execution on this IT project, alongside recruiting a new non executive director, will be closely watched for evidence that the current plan is on track.
Currys’ current analyst narrative assumes revenue grows at 2.8% a year, reaching about £10.1b of sales and £155.8m of earnings by 2029. This implies an earnings decline of £9.2m from £165.0m today rather than an increase.
Uncover how Currys' fair value indicates a 26% potential upside to its current price before that valuation gap starts to close.
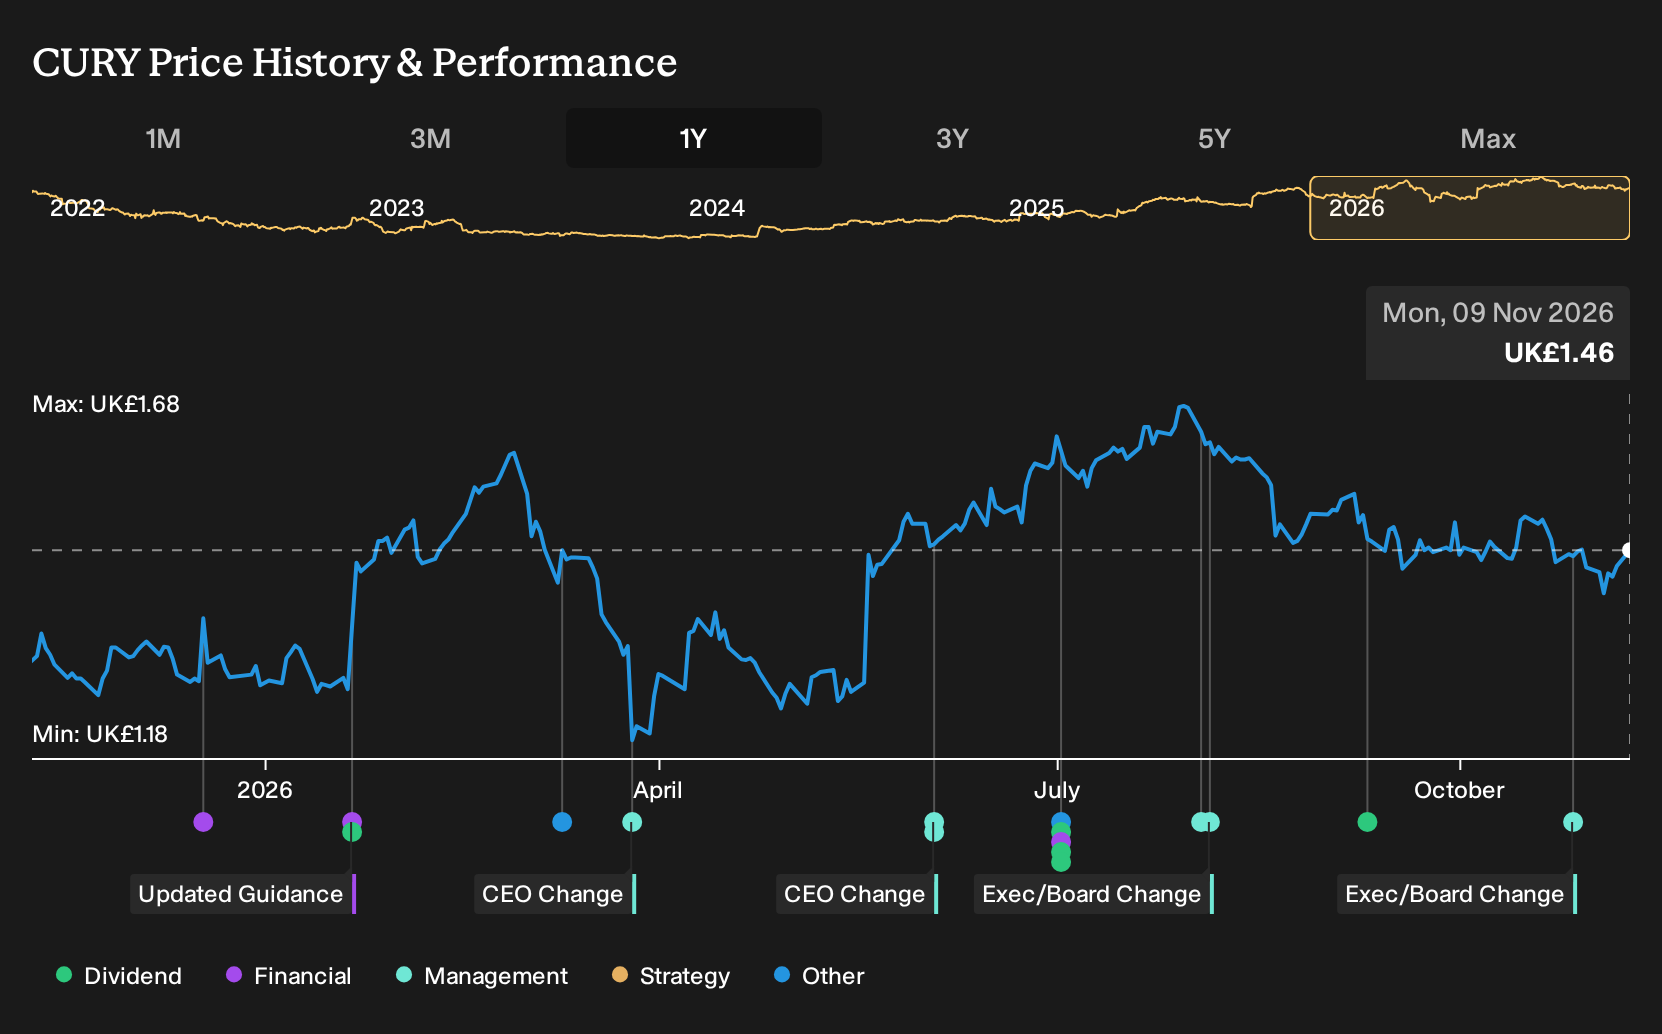
Exploring Other Perspectives
One alternate view focuses on Currys’ exposure to online rivals rather than the services push. The most bearish analysts were working off slower top line assumptions, with revenue projected at about £9.9b and earnings around £139.7m by 2029, before this board change. Use that gap to test how your own expectations might shift as the story evolves.
Explore 3 other Currys fair value estimates, including one that suggests it could be worth just £1.52.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Currys research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Currys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Currys' overall financial health at a glance.
Looking For More Investment Ideas Beyond Currys?
Once you have formed a view on Currys, it can help to set that thesis against a wider watchlist. Use the Simply Wall St Screener to build a line up of opportunities that match your own risk tolerance and return goals instead of relying on a single story.
- If you want potential value opportunities with solid fundamentals, start by scanning a curated set of 16 high quality undervalued stocks that combine quality metrics with pricing that may look attractive on closer inspection.
- For investors who care most about balance sheet resilience, filter for companies on the list of solid balance sheet and fundamentals (9 results) and see which businesses pair financial strength with steady operating profiles.
- Income focused readers can zero in on higher yielding opportunities by reviewing the 6 dividend fortresses that aim to combine substantial payouts with robust cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com