


EN
Is Wärtsilä Oyj Abp (HLSE:WRT1V) Undervalued Following Mixed Q3 Earnings?
What the latest earnings tell you about Wärtsilä Oyj Abp
Wärtsilä Oyj Abp (HLSE:WRT1V) has just put fresh numbers on the table, with third quarter 2026 and nine month results showing higher sales alongside reduced net income compared with the previous year.
The update gives you a mixed picture. Third quarter sales reached €1,493 million versus €1,397 million a year earlier, while net income came in at €123 million compared with €181 million. This sets up a nuanced read on profitability.
Investors have been weighing those mixed Wärtsilä Oyj Abp earnings against the share price, which closed at €26.41 after a 1-day share price return of 2.32% and a 7-day share price return of 1.19%, yet remains down about 10% over both the past month and past quarter. That softer recent momentum contrasts with a 1-year total shareholder return of 1.30% and very large 3-year and 5-year total shareholder returns of about 15x and a little over 2x respectively. This suggests the latest results and earnings call on 27 October 2026 are being treated more as a pause for reassessment rather than a reset of the longer run story.
Compare Wärtsilä Oyj Abp's latest reset in earnings power with other industrials that combine resilient balance sheets and cash flow support by scanning our hand picked list of solid balance sheet and fundamentals (194 results).
Bulls point to Wärtsilä Oyj Abp’s long run total returns and current discount to some valuation estimates, while bears focus on softer earnings and share price pressure. Which story do the numbers back up as you test the valuation?
Most Popular Narrative: 20.1% Undervalued
On the analyst consensus Narrative on Simply Wall St, Wärtsilä Oyj Abp screens as undervalued, with a fair value of €33.04 against the last close at €26.41, which puts the focus on whether the current share price reflects its contracted backlog and service potential.
Expanded engine manufacturing capacity in Vaasa, which is running at 100% of technical capacity in 2026 with order slots sold out for 2028 and largely committed for 2029, supports a long queue of deliveries that can feed Wärtsilä Oyj Abp revenue and earnings as projects are executed and invoiced.
Very high agreement attachment rates above 80% on new equipment orders, including the large data center backlog, create scope for Wärtsilä Oyj Abp to convert installed assets into long duration service contracts that can add more recurring revenue and potentially steadier net margins.
See why 22 investors see Wärtsilä Oyj Abp as 20% undervalued.
Result: Fair Value of €33.04 (UNDERVALUED)
Still, the Wärtsilä Oyj Abp story depends on shipowners not extending maintenance deferrals for long, and on limited 2028 to 2029 capacity not constraining future orders.
Find out about the key risks to this Wärtsilä Oyj Abp narrative.
Another View: What Wärtsilä Oyj Abp’s P/E Is Telling You
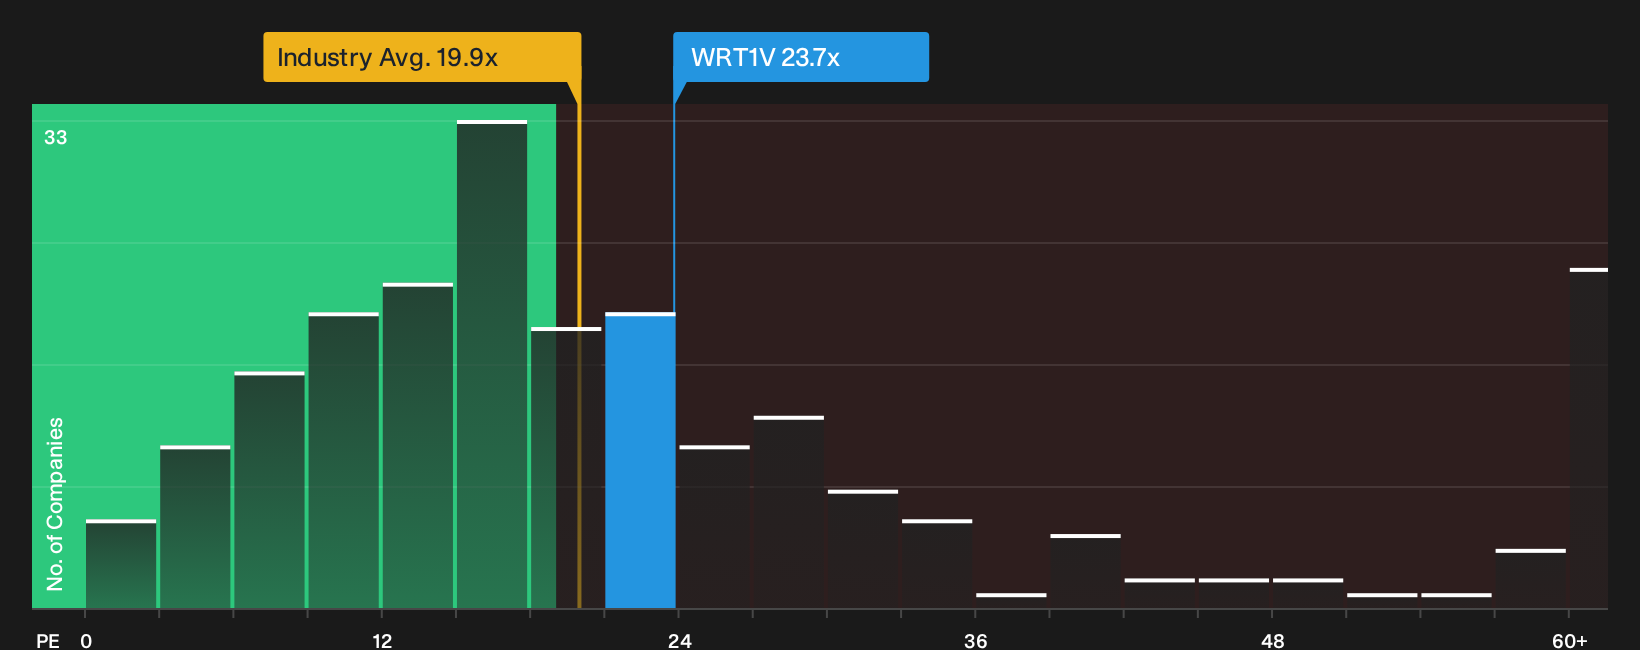
The DCF output paints Wärtsilä Oyj Abp as good value, yet its 23.7x P/E sits above both European Machinery peers on 19.9x and its own sector peer group on 22.9x, while still below a fair ratio of 25.4x. That mix points to some valuation cushion, but also less room for error if earnings disappoint. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages or quiet opportunity, the debate around Wärtsilä Oyj Abp only matters if you pressure test the data yourself and act before sentiment shifts. To see what positives others are already focusing on, review its 3 key rewards.
Looking for more investment ideas beyond Wärtsilä Oyj Abp?
If you stop here, you only see one angle. Widen your options with focused stock ideas that match how you like to balance risk and reward.
- Target potential bargains by scanning companies that currently screen as value opportunities using our 209 high quality undervalued stocks.
- Build an income focused list by reviewing higher yielding payers filtered through the 222 dividend fortresses.
- Prioritise resilience and financial strength by analysing companies highlighted in the 202 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com