


EN
Learn Why The Bull Case For Morgan Sindall Group (LSE:MGNS) Could Change Following Infrastructure Pipeline Growth
- Morgan Sindall Group reported that it released its Q3 2026 sales and trading statement on 5 November 2026, giving investors updated detail on performance across construction, infrastructure, regeneration and housing activities.
- The focus on a long-duration infrastructure workload and a regeneration and housing pipeline of about 55,000 homes sets out how secured partnerships may influence activity levels across the group.
- This update also outlines how Morgan Sindall Group's investment narrative is shaped by investor attention on its long term infrastructure pipeline.
Scan the wider UK construction and infrastructure space by comparing Morgan Sindall Group with a curated set of peers in the list of solid balance sheet and fundamentals (9 results).
Morgan Sindall Group Investment Narrative Recap
To own Morgan Sindall Group, you need to believe that its long duration infrastructure workload and large regeneration and housing partnerships can keep turning a visible pipeline into real projects. The analyst consensus Narrative on Simply Wall St leans on that conversion, supported by a cash backed model and medium term divisional targets. The latest Q3 trading update date itself does not look like a major swing factor.
In the short term, the key catalyst is still execution on regeneration schemes and infrastructure frameworks as they move from planning to build phases. The biggest risk is that Fit Out margins and volumes normalise faster than other divisions can compensate, or that capital remains tied up for longer in Partnership Housing and Mixed Use Partnerships, limiting returns.
The most relevant recent disclosure is the focus on Morgan Sindall Group’s long duration infrastructure frameworks and roughly 55,000 home regeneration and housing pipeline. That is where contract timing, planning progress and funding decisions feed directly into future activity. The Q3 statement matters mainly as a checkpoint on how much of that pipeline is actually converting.
For catalysts, attention stays on how quickly schemes that are currently secured or at preferred bidder stage shift into delivery, particularly in energy, nuclear and power frameworks and on larger multi decade urban regeneration projects. Any signs in the numbers that viability challenges are causing extended delays, or that Fit Out profitability is stepping down from recent levels, would weigh on the narrative built into analyst models.
Morgan Sindall Group Analyst Assumptions And Valuation Anchors
Analysts sketch a relatively steady profile for Morgan Sindall Group, with forecasts built around modest top line expansion and flat earnings. The consensus view points to revenue increasing by 3.1% a year over the next three years and profit margins easing from 3.6% today to 3.3% by 2029.
Earnings today are put at £189.0 million, with analysts expecting that figure to stay at roughly the same level by the 2029 forecast horizon. That implies no material earnings change in value, even as the business mix tilts further toward long duration infrastructure and regeneration work.
To make those assumptions line up with current analyst targets, investors would need to be comfortable with Morgan Sindall Group trading on a 2029 P/E ratio of 18.3x, compared with 9.6x on today’s numbers and above the 16.3x level quoted for the wider GB Construction sector. The forecasts also build in a small 0.19% yearly increase in the share count over the next three years and use a discount rate of about 9.4% to translate future cash flows into today’s values.
Morgan Sindall Group's narrative projects £5.7b revenue and £189.0 million earnings by 2029. This assumes 3.1% yearly revenue growth and earnings remaining broadly unchanged from current earnings of £189.0 million.
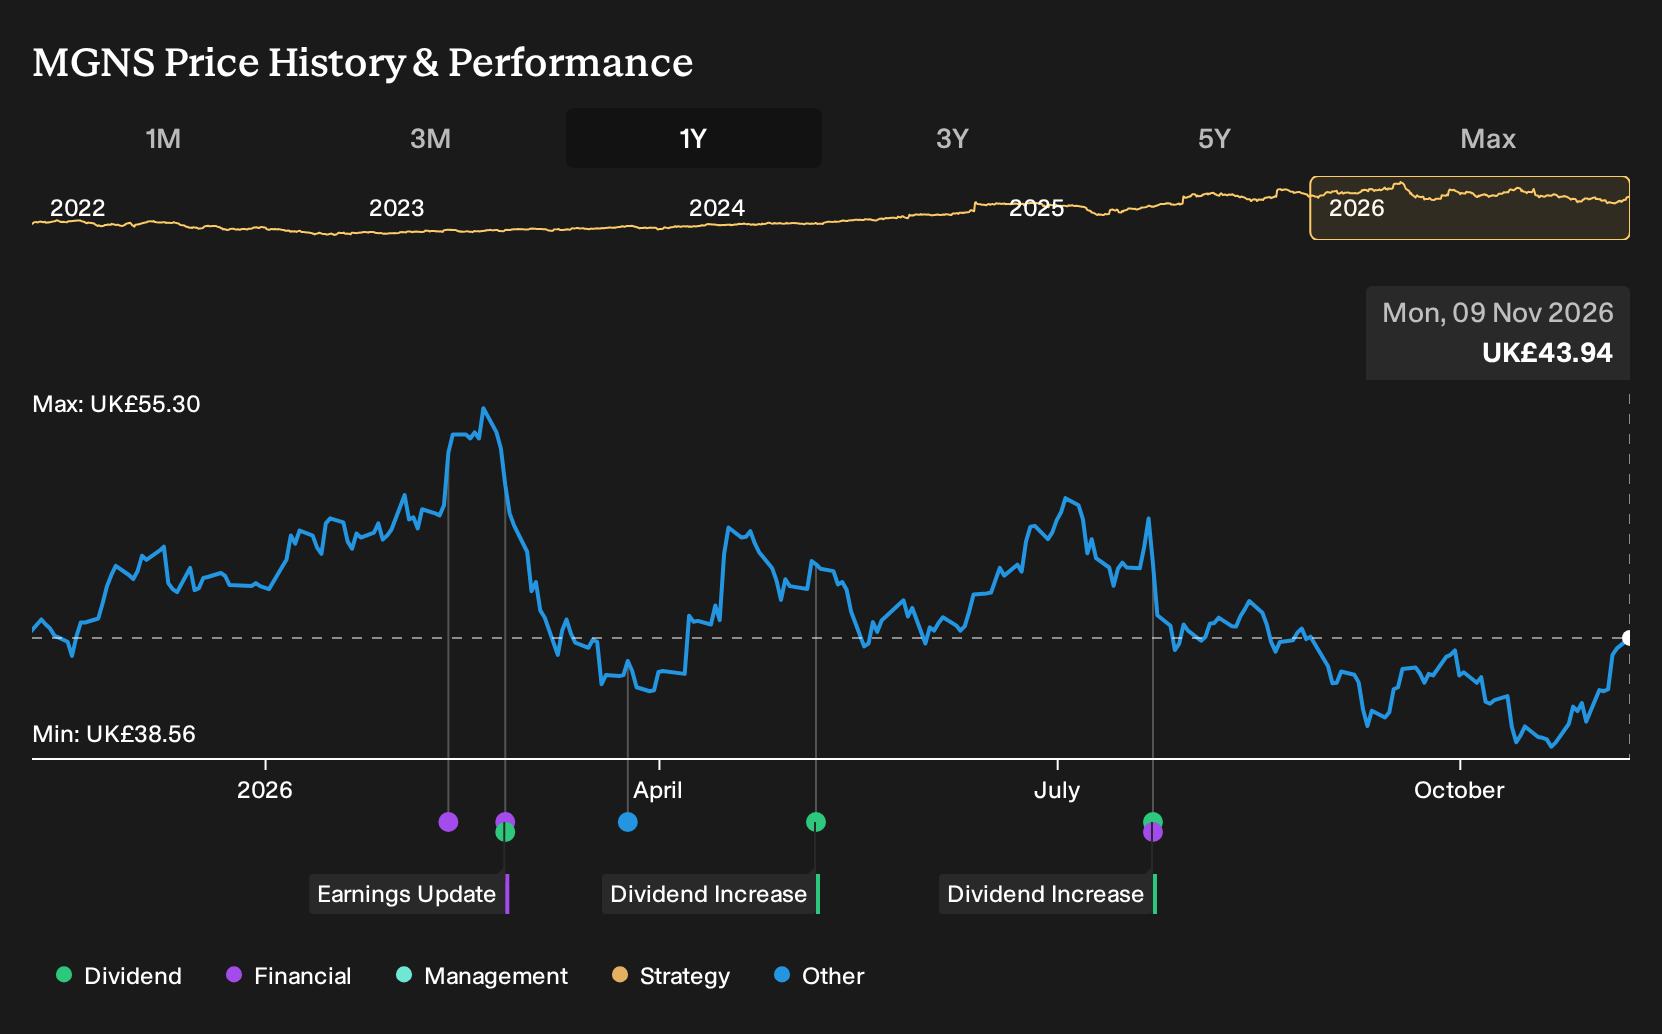
Uncover why Morgan Sindall Group's fair value indicates a 28% potential upside to its current price, which could close more quickly than the earnings profile suggests.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster tightly between £53.68 and £56.21, so retail opinions around Morgan Sindall Group sit in a narrow band. Those views were formed before the 5 November Q3 statement. Treat them as a starting point and then weigh them against execution risks in regeneration and infrastructure frameworks.
Explore 2 other Morgan Sindall Group fair value estimates, including one that suggests it could be worth just £53.68!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Morgan Sindall Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Morgan Sindall Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Morgan Sindall Group's overall financial health at a glance.
Looking For More Ideas Beyond Morgan Sindall Group?
If the Morgan Sindall Group story has sharpened your thinking, use that momentum to broaden your watchlist with other companies that fit clear financial filters in the Simply Wall St Screener.
- Focus on quality at a discount by scanning for companies with strong fundamentals that may be trading below their estimated worth through the 16 high quality undervalued stocks.
- If capital preservation is front of mind, narrow in on businesses with sturdier financial profiles using the 4 resilient stocks with low risk scores.
- For investors interested in potentially resilient income streams, filter for higher yielding payers through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com