


EN
Is DexCom (DXCM) Still Below Fair Value As Guidance Rises And Buybacks Begin?
DexCom (DXCM) just packed several updates into one week, pairing a third quarter earnings release and higher 2026 revenue outlook with a new share repurchase plan and a fresh CGM launch in Canada.
DexCom shares have pulled back in recent months, with a 90 day share price return of down 9.45% and a 30 day move of down 3.61%. Yet the year to date share price return of 21.84% and 1 year total shareholder return of 47.83% point to momentum that has been building over a longer stretch as investors weigh the stronger revenue guidance, buyback plan and CGM rollout against longer term total shareholder return that is still down over 3 and 5 years.
Scan how DexCom’s latest guidance, buyback and G7 15 Day launch compare with other potential breakout opportunities in our hand picked 36 healthcare AI stocks list.
Bulls point to DexCom’s higher 2026 revenue outlook, solid year to date returns, and a fresh buyback, while bears focus on multi year underperformance. Which side does the current valuation actually support?
Most Popular Narrative: 31% Undervalued
DexCom’s last close at $81.07 sits well below the $117.59 fair value estimate in the most followed narrative, according to MarkoVT, a Simply Wall St Community investor who built a detailed model using growth, margins and a set discount rate.
DexCom has continued to reap the rewards stemming from positive Earnings and investors seeking appealing, undervalued stocks outside of memory chip / semiconductor companies. YTD price performance stands at 23.50%. Re-evaluation of metrics refocuses Fair value to $117.59 under the following adjustments:
See why 2 investors see DexCom as 31% undervalued.
Result: Fair Value of $117.59 (UNDERVALUED)
Still, DexCom’s weaker 3- and 5-year total returns and a forward P/E above sector averages could pressure sentiment if growth or margins fall short.
Find out about the key risks to this DexCom narrative.
Another View On DexCom’s Valuation
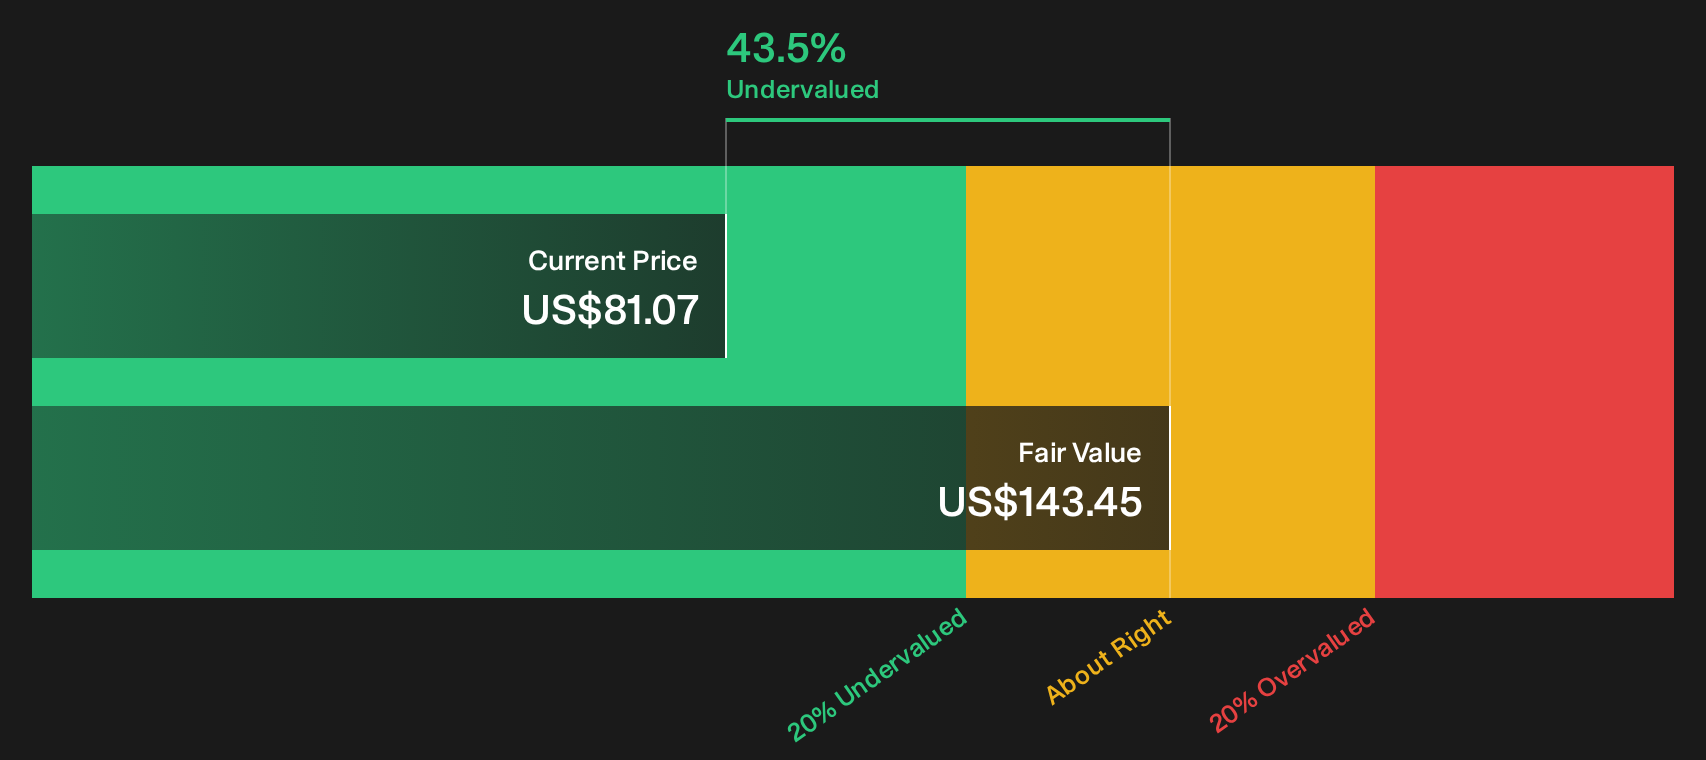
There is a catch. While the community narrative leans on growth and multiples to discuss whether DexCom is undervalued, our DCF model presents a different perspective, with an estimated future cash flow value of $143.45 compared with the current $81.07 share price.
That is a wide spread for any investor to consider. It raises a simple question: is the market appropriately reflecting execution and growth risks, or placing too little emphasis on potential long-term cash generation?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
All this optimism around DexCom’s potential is only useful if you pressure test it yourself and act before the next sentiment shift. To weigh the upside that others are watching, take a closer look at the 4 key rewards.
Looking for more investment ideas beyond DexCom?
If you stop with DexCom, you only see part of the opportunity set. Use targeted stock lists to pressure test your thesis and uncover fresh ideas early.
- Hunt for potential mispricing by scanning a curated set of 33 high quality undervalued stocks that pair strong fundamentals with prices that may not fully reflect them.
- Secure your income stream by reviewing a focused group of 6 dividend fortresses that combine higher yields with an emphasis on durability.
- Guard against nasty surprises by filtering for 30 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com