


EN
Ripple Custody Deal Could Be A Game Changer For Bank of New York Mellon Corporation (BNY)
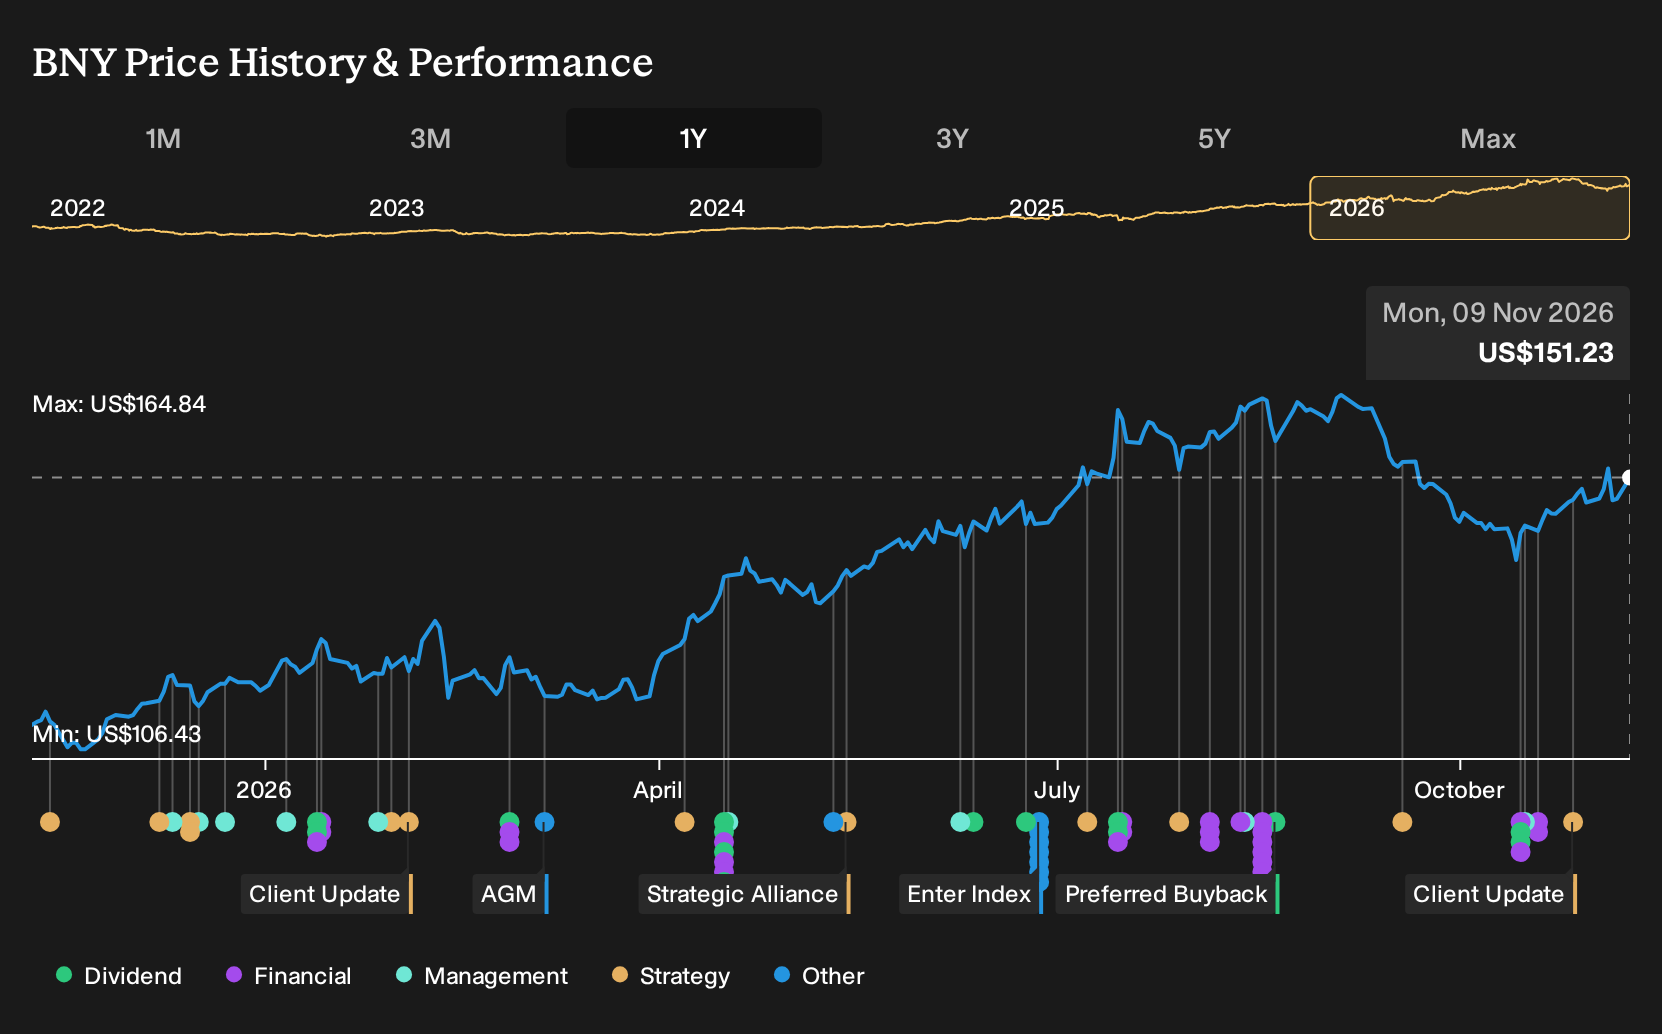
- Ripple reported an expanded collaboration with BNY that adds XRP and RLUSD to BNY’s Digital Asset Custody platform and sets up work on tokenized trade finance and RLUSD minting and redemption for eligible institutional clients.
- The Tradeweb Markets link to BNY’s LiquidityDirect platform and BNY’s ongoing role as Agent Bank on multiple floating rate notes highlight how Bank of New York Mellon Corporation is trying to embed its infrastructure deeper into client workflows across both digital assets and traditional securities.
- The next area of focus will be how Bank of New York Mellon Corporation's expanded digital asset custody work with Ripple could shape that investment narrative.
Scan how Bank of New York Mellon Corporation is leaning into custody, payments and tokenization themes, then broaden your watchlist with hand picked list of solid balance sheet and fundamentals (25 results).
Bank of New York Mellon Investment Narrative Recap
To own Bank of New York Mellon Corporation you need to believe its fee hungry custody and servicing machine keeps humming while the AI supported platform model and digital asset build out stay on track. The analyst consensus Narrative on Simply Wall St leans on stable fee income, rising efficiency and disciplined costs to support this view.
In the near term, the key swing factor is whether expense growth stays below revenue so the recent 600 basis points of positive operating leverage and roughly US$2b of efficiency savings do not unwind. The biggest risk is pressure on mandate flows or pricing that weakens fees at the same time as sector P/E multiples compress.
The extended Ripple agreement looks most relevant for Bank of New York Mellon Corporation right now because it sits exactly where the analyst consensus Narrative on Simply Wall St sees potential new fee pools, digital custody and tokenization. Supporting XRP and RLUSD on the Digital Asset Custody platform keeps BNY involved where institutional plumbing is being retooled.
Execution will matter. Safekeeping XRP and RLUSD, plus potential tokenized trade finance flows and RLUSD minting and redemption for eligible clients, all test whether BNY can turn engineering spend into recurring servicing income without letting operational risk or compliance complexity drag on costs or distract from core custody and corporate trust work.
Bank of New York Mellon's narrative projects US$24.4b revenue and US$7.4b earnings by 2029, based on analysts' assumption of 4.5% yearly revenue growth and an earnings increase of about US$1.4b from the current US$6.0b level.
Uncover why Bank of New York Mellon's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$147 and US$163 per share, which already shows how far private opinions on Bank of New York Mellon Corporation can spread. With fresh Ripple custody work and upcoming conference commentary on costs and fees, those views may shift and investors may wish to explore several alternative viewpoints.
Explore another Bank of New York Mellon fair value estimate, including one that suggests it could be worth just $147.39.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bank of New York Mellon research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank of New York Mellon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of New York Mellon's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bank of New York Mellon?
Once you have a view on Bank of New York Mellon Corporation, it often helps to widen the lens and compare it with other potential opportunities that fit different risk and income profiles.
- For investors who want income potential with an emphasis on resilience, review a set of higher yielding payout candidates through 6 dividend fortresses.
- If capital protection and steadier profiles matter more to you than rapid upside, scan a basket of companies flagged as relatively resilient using 30 resilient stocks with low risk scores.
- When you want to focus on quality at a reasonable entry point, line up candidates that combine fundamentals and valuation support via 33 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com