


EN
ASML Holding (ASML) Falls Back, Is The Stock Still Cheap?
ASML Holding (NasdaqGS:ASML) has drawn renewed investor attention after recent share price swings, with the stock down about 15% over the past month and roughly 16% over the past 3 months.
Despite the recent decline, ASML Holding’s 1-year total shareholder return of 46.43% and 3-year total shareholder return of about 1.36x indicate stronger longer-term gains, while the 30-day share price return of negative 15.0% suggests that momentum has recently faded.
Scan how ASML Holding compares with other chipmakers under pressure by checking a curated set of 53 AI infrastructure stocks right now.
Bulls see a temporary reset in ASML Holding after a strong run, while bears see a rich price tag meeting rising expectations. Which side does the current valuation actually support next?
Most Popular Narrative: 16% Undervalued
ASML Holding last closed at $1,513.25, while the most followed narrative on Simply Wall St puts fair value at $1,809.43, implying the shares trade at about a 16% discount according to that framework. TradingClimbers, a Simply Wall St Community investor who wrote the narrative, frames ASML as a high quality business where timing the entry price matters more than chasing recent strength.
My thesis is simple: ASML is a toll booth on the progress of semiconductors. Every new node, every new DRAM generation and every AI accelerator needs more lithography layers, and the most advanced layers can only be printed on ASML's tools. The moat is wide: decades of R&D, a unique supplier network (Zeiss optics above all), deep customer integration and a growing installed base that produces recurring, high-margin service revenue. The business is cyclical, which is why I want to build the position on weakness, step by step, instead of chasing strength.
See why 5 investors see ASML Holding as 16% undervalued.
Result: Fair Value of $1,809.43 (UNDERVALUED)
Still, tighter export controls on China or a sharp pullback in AI and memory capex could quickly challenge the bullish fair value story around ASML Holding.
Find out about the key risks to this ASML Holding narrative.
Another View: ASML Holding Looks Expensive On Earnings
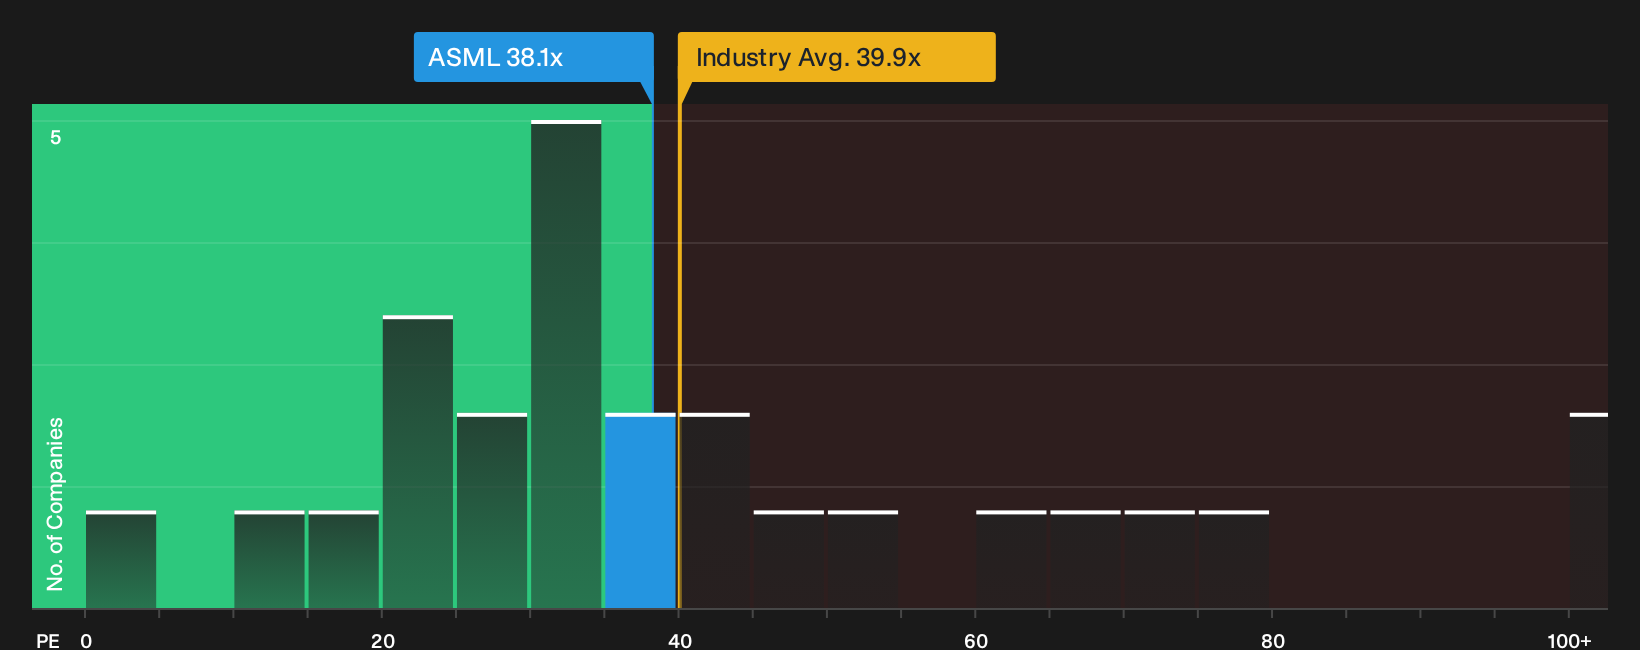
The most followed Simply Wall St narrative calls ASML Holding about 16% undervalued, but the earnings-based picture is less friendly. At a P/E of 38.1x versus a US Semiconductor peer average of 32.5x and a fair ratio of 34.2x, the stock carries a rich valuation that could limit upside if sentiment cools.
This kind of premium can persist for a quality business, yet it also raises the question investors care about most: Is paying above both peers and the fair ratio a risk worth taking, or a signal to demand a wider margin of safety before stepping in?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around ASML Holding can feel messy, so move quickly, look through the underlying data, and decide what stacks up for you. To understand what investors view as upside potential, review the 2 key rewards.
Looking for more ASML Holding sized opportunities?
Do not stop with ASML Holding. Use the Simply Wall St screener to hunt for fresh ideas that match your risk comfort and return goals before the next move passes you by.
- Target potential mispricings by scanning a curated set of 33 high quality undervalued stocks that combine quality fundamentals with attractive valuations.
- Secure potential income streams by reviewing a focused group of 6 dividend fortresses that aim to pair higher yields with resilient cash generation.
- Dial down volatility risk by concentrating on a handpicked 30 resilient stocks with low risk scores designed to highlight businesses with more durable financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com