


EN
How Narrower Losses Will Impact Axsome Therapeutics Stock Investors
- Axsome Therapeutics reported third quarter 2026 revenue of US$259.69 million and a net loss of US$12.88 million, with nine-month revenue at US$669.27 million and a loss of US$128.73 million. Both periods showed lower basic loss per share from continuing operations than a year earlier.
- The earnings update indicates progressing cost control relative to revenue for Axsome Therapeutics, with losses narrowing as the central nervous system portfolio scales. This may matter for how investors weigh ongoing R&D and commercialization spending.
- This context helps explain how Axsome Therapeutics' stronger revenue base, alongside a smaller quarterly loss, may influence the broader investment narrative.
Axsome Therapeutics Investment Narrative Recap
To own Axsome Therapeutics, you need to believe the CNS portfolio can scale enough to cover ongoing R&D and commercial spend. The recent quarter, with revenue of US$259.69 million and a net loss of US$12.88 million, points to losses narrowing but not gone. The analyst consensus Narrative on Simply Wall St still flags reliance on Auvelity, Sunosi and SYMBRAVO as a key operational tension.
The most important near term catalyst remains execution on current launches and payer access, because that is what can change the loss profile fastest. The biggest immediate risk is that gross to net pressure or slower uptake keeps margins weak. The latest earnings do not remove that risk; they instead show the business moving in the right operational direction.
The fresh earnings release is the announcement that matters most here. It provides an updated read on Axsome Therapeutics' ability to turn its CNS portfolio into a more self funding model. Revenue of US$669.27 million for the first nine months of 2026, alongside a nine month loss of US$128.73 million, illustrates how much work is still required.
Those figures sit against catalysts highlighted in the analyst consensus Narrative on Simply Wall St, which focuses on expanding products like SYMBRAVO and late stage programs such as AXS 05, AXS 12 and AXS 14. Execution on those opportunities could diversify revenue away from the current lead therapies. If that rollout stumbles or payers tighten further, the risk of extended losses and potential dilution remains front and center.
Axsome Therapeutics' current earnings are a loss of US$157.3 million, with analysts expecting earnings of US$928.4 million by 2029, which implies an earnings increase of about US$1.1b. That consensus outlook also assumes revenue growth of 44.7% per year and is tied to forecasts for 2029 revenue of US$2.6b.
Uncover how Axsome Therapeutics' fair value indicates a 102% potential upside to its current price, which could narrow quickly as sentiment adjusts.
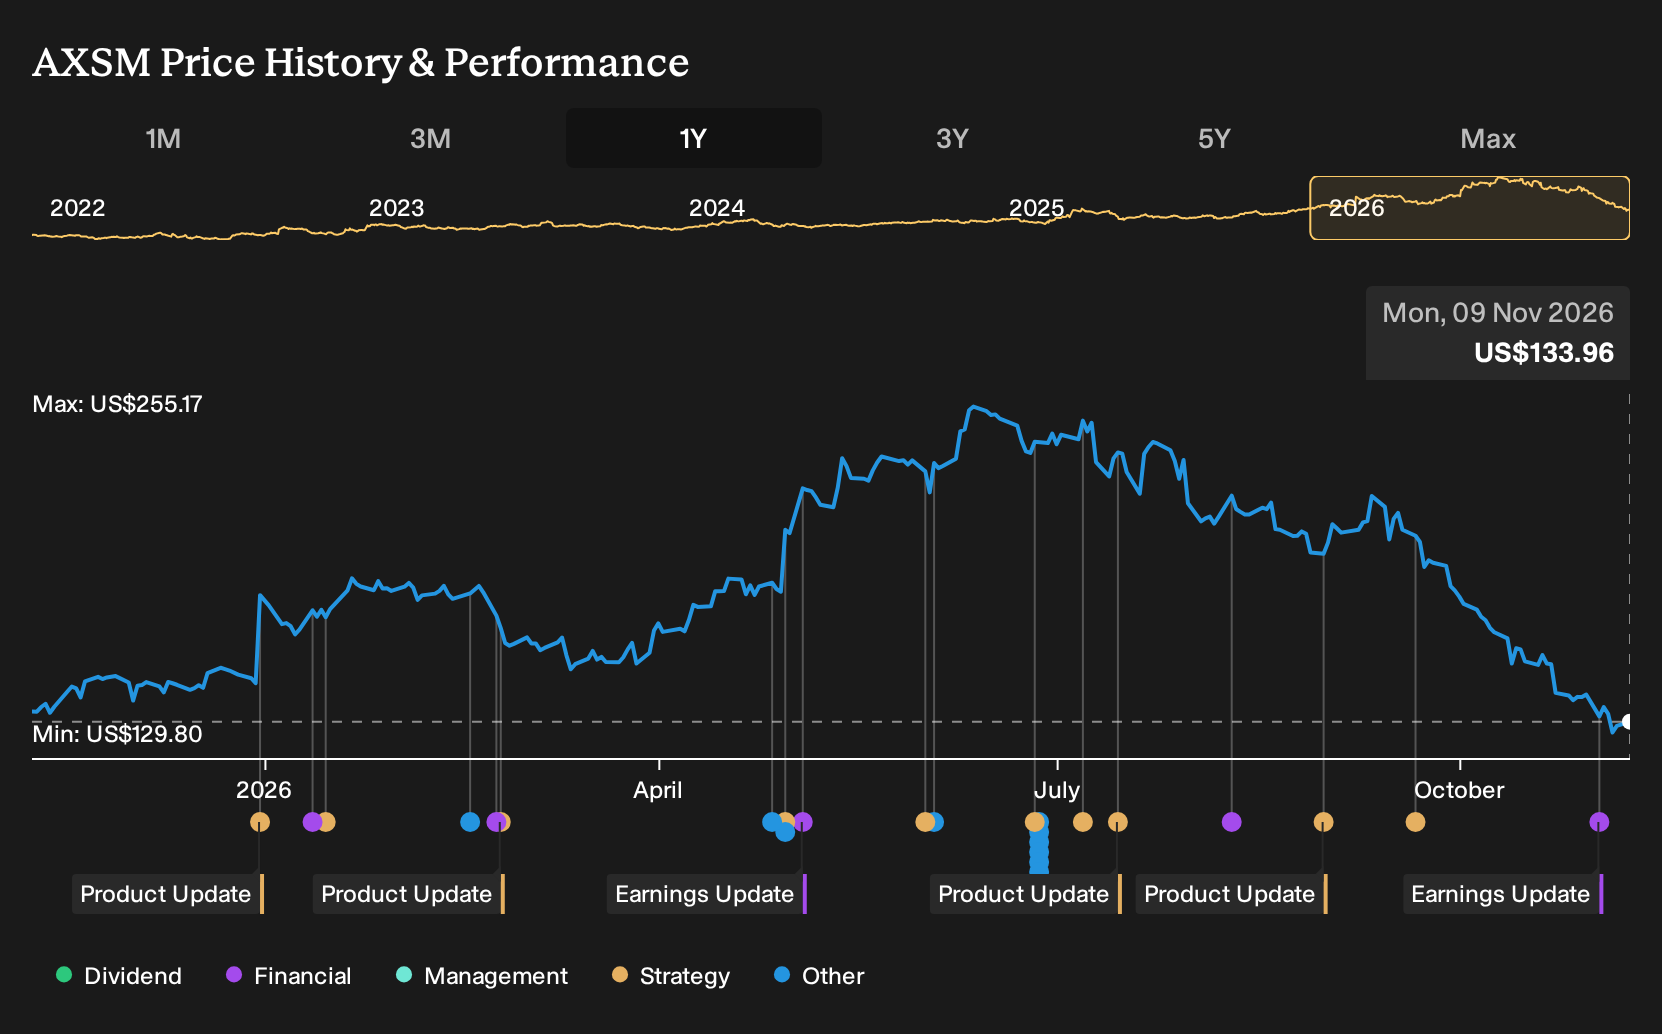
Exploring Other Perspectives
One bullish catalyst you may want to weigh against Axsome Therapeutics' current earnings is the high end revenue and profit outlook. The most optimistic analysts were modeling about US$3.2b in 2029 revenue and US$1.7b in earnings before this quarter and the upcoming conferences, which is far more upbeat than consensus. Those views lean heavily on AXS 12 approval and Auvelity scaling smoothly, so this earnings print and the November presentations could push those expectations higher or lower. Use that spread in opinions as a reminder to compare several narratives, not just one, before you decide how Axsome Therapeutics fits your own portfolio thinking.
Explore 4 other Axsome Therapeutics fair value estimates, including one that suggests as much as 553% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Axsome Therapeutics research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Axsome Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Axsome Therapeutics' overall financial health at a glance.
Looking for more Axsome Therapeutics style investment ideas?
If Axsome Therapeutics has you thinking about position sizing, risk and upside across your whole portfolio, it can help to broaden the watchlist using a structured screener rather than headlines alone.
- For investors who care most about quality at a reasonable price, start with companies that look attractively priced on both cash flows and balance sheet strength through the 33 high quality undervalued stocks.
- If resilience and capital preservation matter more than headline growth, narrow your search to businesses with steadier risk profiles using the 30 resilient stocks with low risk scores.
- When you want financially sound operators as the foundation of your holdings, focus on companies with robust balance sheets and fundamentals with the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com