


EN
JetBlue Stock Faces A Bigger Baggage Fee Bet As Costs Rise
- JetBlue Airways has raised checked baggage fees for most economy passengers across the U.S., Canada, Latin America, and the Caribbean to at least $50 each way, citing elevated jet fuel prices and higher operating costs while aiming to keep base fares competitive.
- The fee increase highlights how JetBlue is leaning more on ancillary revenue from baggage and extras to manage cost pressure without relying solely on headline fare changes.
- This development raises questions about how JetBlue's higher baggage fees, used to offset fuel and operating costs, may influence the broader investment narrative.
JetBlue Airways Investment Narrative Recap
To back JetBlue Airways as a shareholder, you need to believe the airline can turn solid leisure demand and cost work into consistent cash generation, despite current losses and volatile demand patterns flagged in the analyst consensus Narrative on Simply Wall St. The baggage fee hike and tighter ancillary strategy point to management pushing harder on revenue per customer rather than relying only on headline fares.
The bigger swing factor in the near term still looks like execution on operations and cost control, especially with rising labor and fuel costs and no fuel hedging. The fee move helps on the margin but does not change the main risk, which is pressure on unit revenues and load factors in weaker travel periods.
The new Fort Lauderdale routes to Indianapolis and Columbus look most relevant for thinking about JetBlue Airways right now. They fit into JetForward and the focus on an East Coast leisure network with Fort Lauderdale as a core node, giving the carrier more ways to connect U.S. customers into Caribbean and Latin America flying.
For catalysts, those flights feed directly into the capacity story that analysts already assume, where grounded aircraft coming back are expected to support low single digit growth from 2026. The risk is that added seats into these Midwestern markets meet softer demand or tougher competition, which could limit the benefit from higher fees and incremental connectivity.
JetBlue Airways' narrative projects revenues of US$13.1b and earnings of US$44.9m by 2029. This setup uses a 9.4% yearly revenue growth assumption and implies an earnings swing of about US$1.0b from a loss of US$1.0b today to positive earnings in that forecast year.
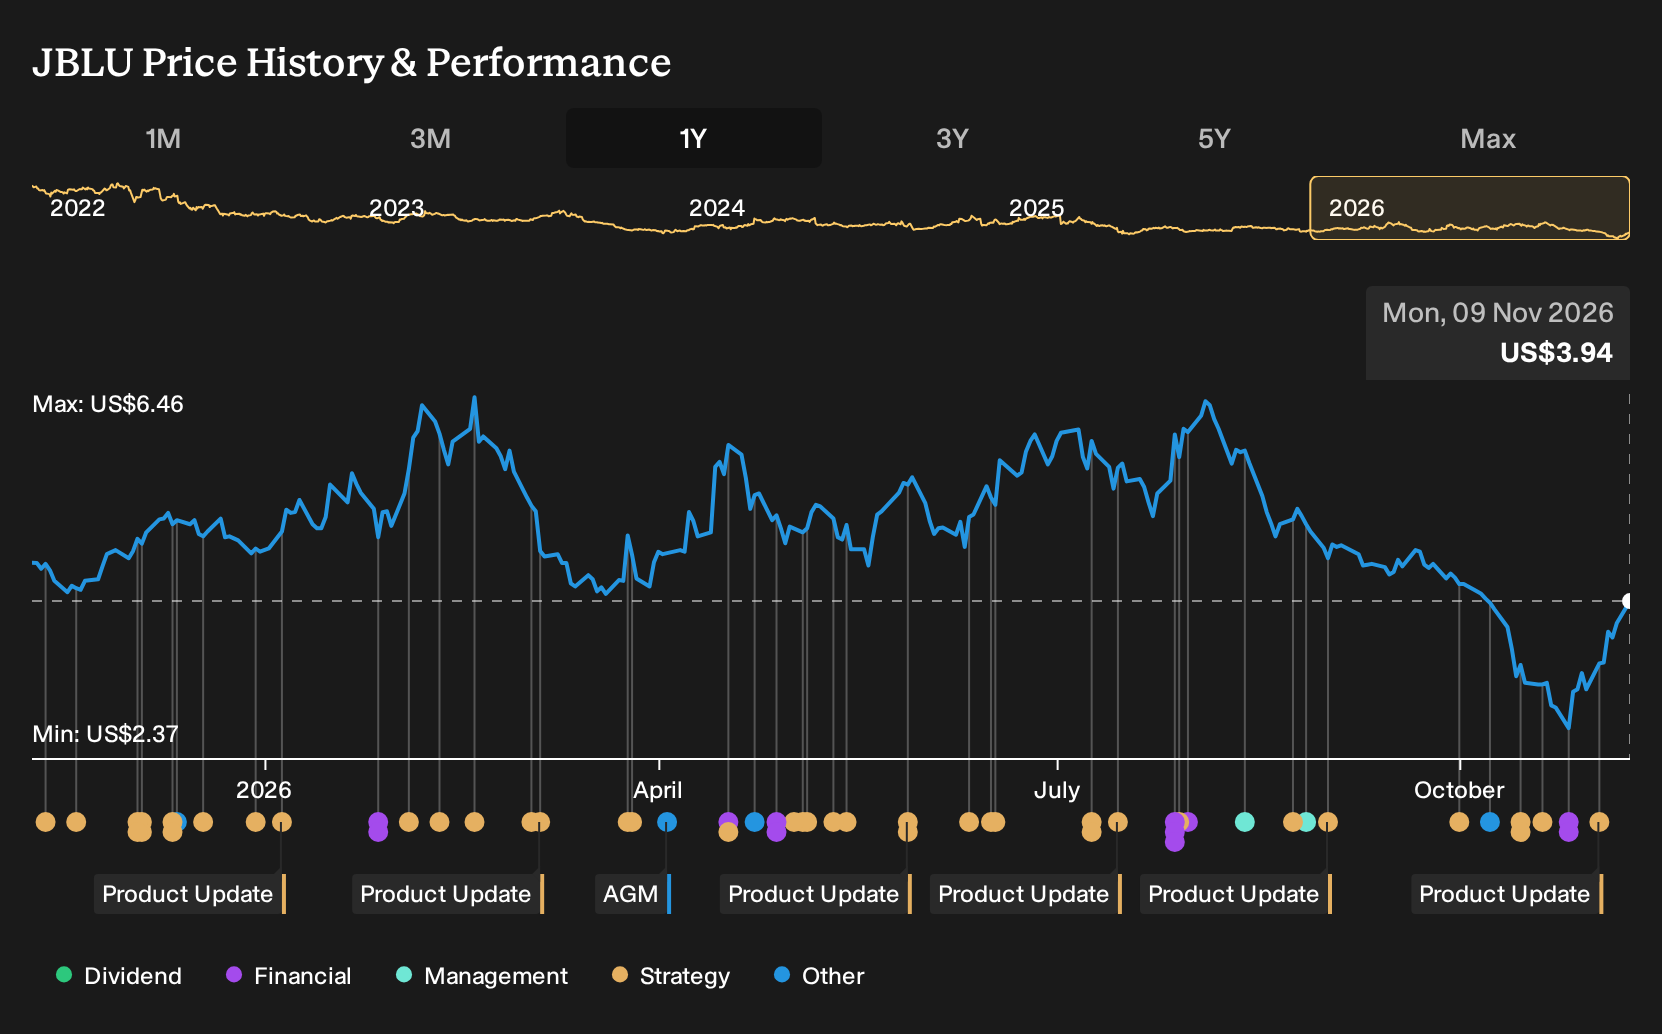
Uncover why JetBlue Airways' fair value indicates a 6% potential upside to its current price before the gap to market pricing narrows.
Exploring Other Perspectives
One alternate view focuses less on Fort Lauderdale growth and more on the risk that higher jet fuel costs keep eating into JetBlue’s JetForward earnings uplift. The most cautious analysts were penciling in revenue of about US$12.5b and earnings near US$35.4m by 2029. That is far below the wider group’s expectations. These pre news estimates show how far opinions can spread. Use them as a prompt to explore several forecast paths, especially because the new routes and fee changes could nudge both narratives over time.
Explore 2 other JetBlue Airways fair value estimates, including one that suggests it could be worth just $4.17.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your JetBlue Airways research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for JetBlue Airways. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JetBlue Airways' overall financial health at a glance.
Looking for more investment ideas beyond JetBlue Airways?
If JetBlue Airways has you thinking about where risk and reward feel better balanced, it can help to scan a broader set of companies with clear financial profiles and different drivers.
- For investors who want potential upside without taking on extreme balance sheet stress, consider reviewing a curated 11 elite penny stocks with strong financials that already meet strict financial quality filters.
- If resilience and capital strength matter most to you, focus on businesses that pair cleaner finances with steadier fundamentals by using the list of solid balance sheet and fundamentals (25 results).
- When income and staying power are a priority, you can look at companies offering higher yields with robust coverage by scanning the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com