


EN
What Bread Financial Doubters Got Wrong
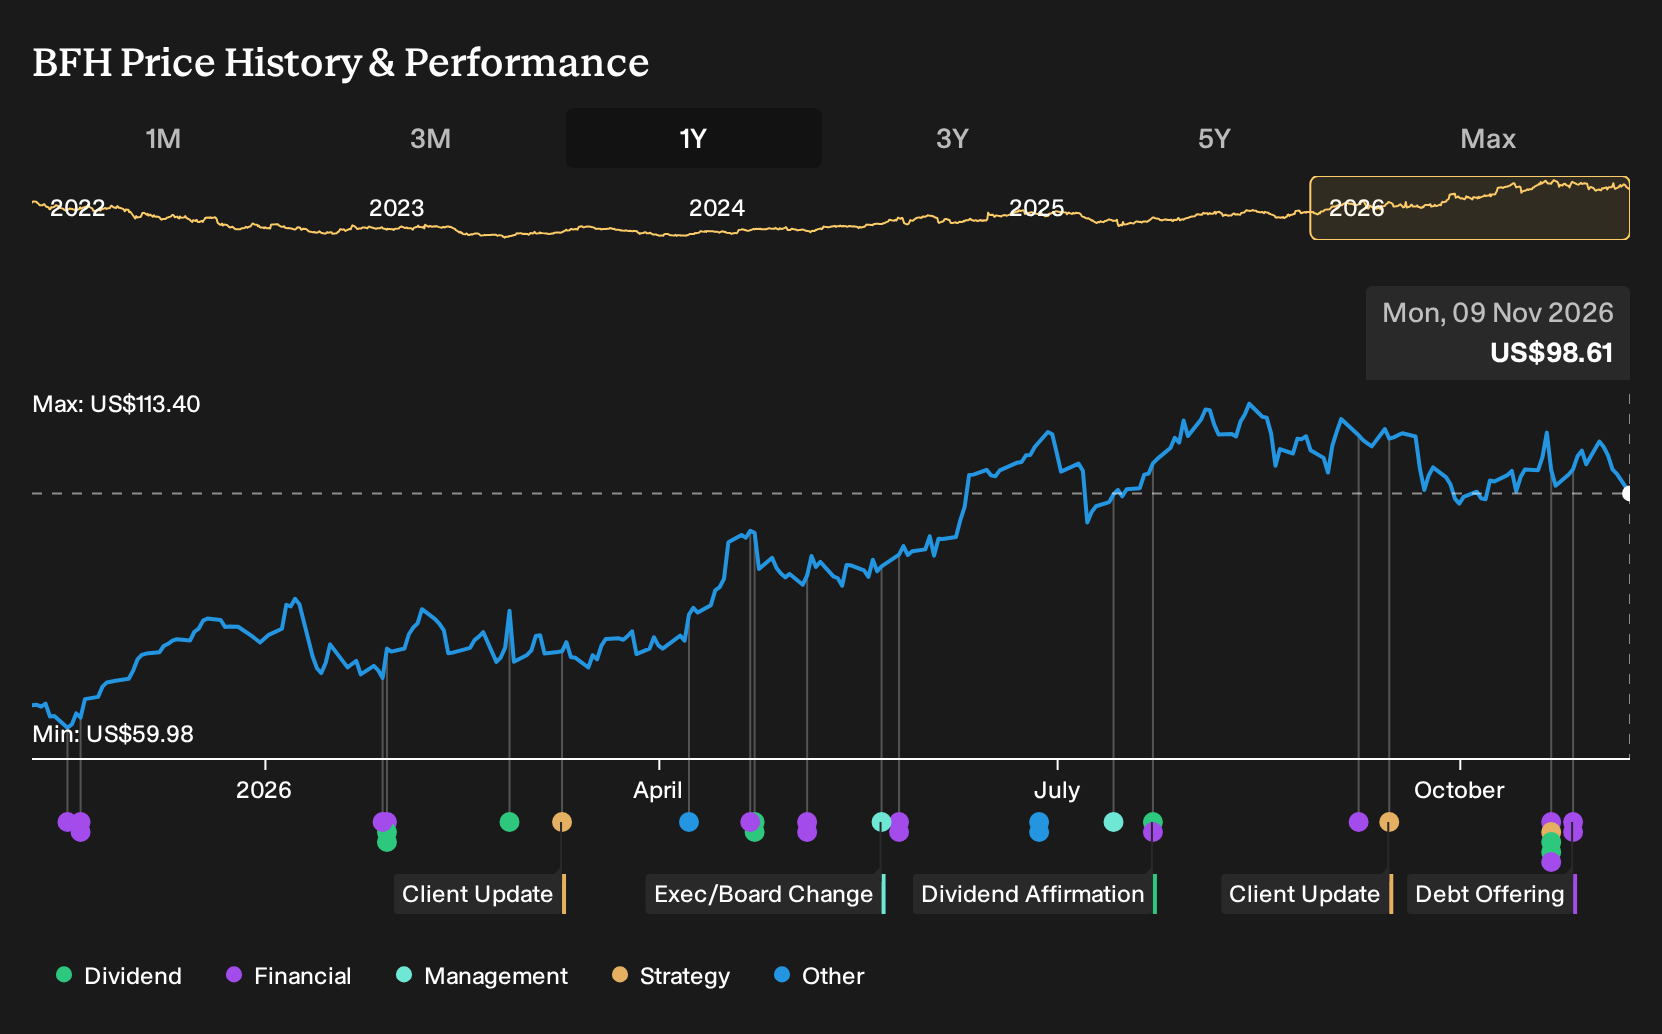
If you had looked only at Bread Financial’s latest headlines about tighter credit conditions, Preferred Stock offerings and mixed profit trends, a smooth ride would not have been the obvious expectation. Holding Bread Financial over the past year would have returned 55.9%, including dividends. If you were weighing up the bullish October 2025 report against the cautious May 2025 bearish view at the starting line, what exactly in the record might have justified accepting that risk?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Bread Financial has already moved. See which of 33 high quality undervalued stocks still trade below our estimates.
The Argument Investors Had To Settle On Bread Financial
The shares cost US$63.58 at the start of the period, and investors in Bread Financial were choosing between two very different written narratives that both looked plausible.
On the bullish side, the Fair Value sat at US$68.73, roughly 8% above the start price, built on ideas like AI driven credit assessment and co brand partnerships helping earnings stability.
The bearish Fair Value was US$51, about 20% below the start price, focused on regulatory pressure and the risk that digital wallets and BNPL would eat into traditional card volumes.
What The Results Changed For The Bread Financial Thesis
Bread Financial’s Q3 2026 figures gave the bullish case some support on activity, with total revenue at US$696 million versus US$672 million a year earlier, and multiple new and renewed partnerships in cards and installment loans. The cautious view gained fresh backing on profitability, as net income moved from US$188 million to US$150 million and net margin fell from 28.0% to 21.6%. The evidence cut both ways.
The key assumption under review was that tech and partner expansion would translate into stronger earnings quality. When you assess another lender with a growth story, check whether new deals and higher revenue show up in a stable or improving net margin rather than just a busier top line.
What Bread Financial's Price Now Assumes
Bread Financial shares now trade at US$98.61, and the bearish analyst Narrative on Simply Wall St places its Fair Value below that level rather than above it. The Narrative highlights a business where better credit quality and fresh products have to work hard just to counter mix shifts in loans and rising expense lines.
A buyer today is effectively assuming Bread Financial can keep earnings resilient while funding higher partner profit shares and heavier technology spending. The question is how that assumption holds up if retailer arrangements and lower fee income start to squeeze what each dollar of receivables delivers.
"While new co-brand and big-ticket retail programs and Bread Pay installment loans are contributing a growing share of loan growth, these products carry lower APRs and rely more heavily on retailer share arrangements. The shift in mix risks building a larger balance sheet that delivers weaker revenue per dollar of loans and puts structural pressure on earnings."
The price and this Narrative do not agree. → Uncover what this Narrative says Bread Financial is actually worth
Which Company Could Surprise You Next?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 38% below our estimate - solves intricate engineering and compliance challenges for heavily regulated client operations.
- Company 2 - 31% below our estimate - routes demanding AI computation onto an existing subscription-based enterprise cloud infrastructure.
- Company 3 - 26% below our estimate - links long-life mineral reserves to operations with meaningfully higher cost and margin uncertainty.
That is three of the list. See all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com