


EN
Should Market Driven AUM Growth Require Action From Cohen & Steers Stock Investors?
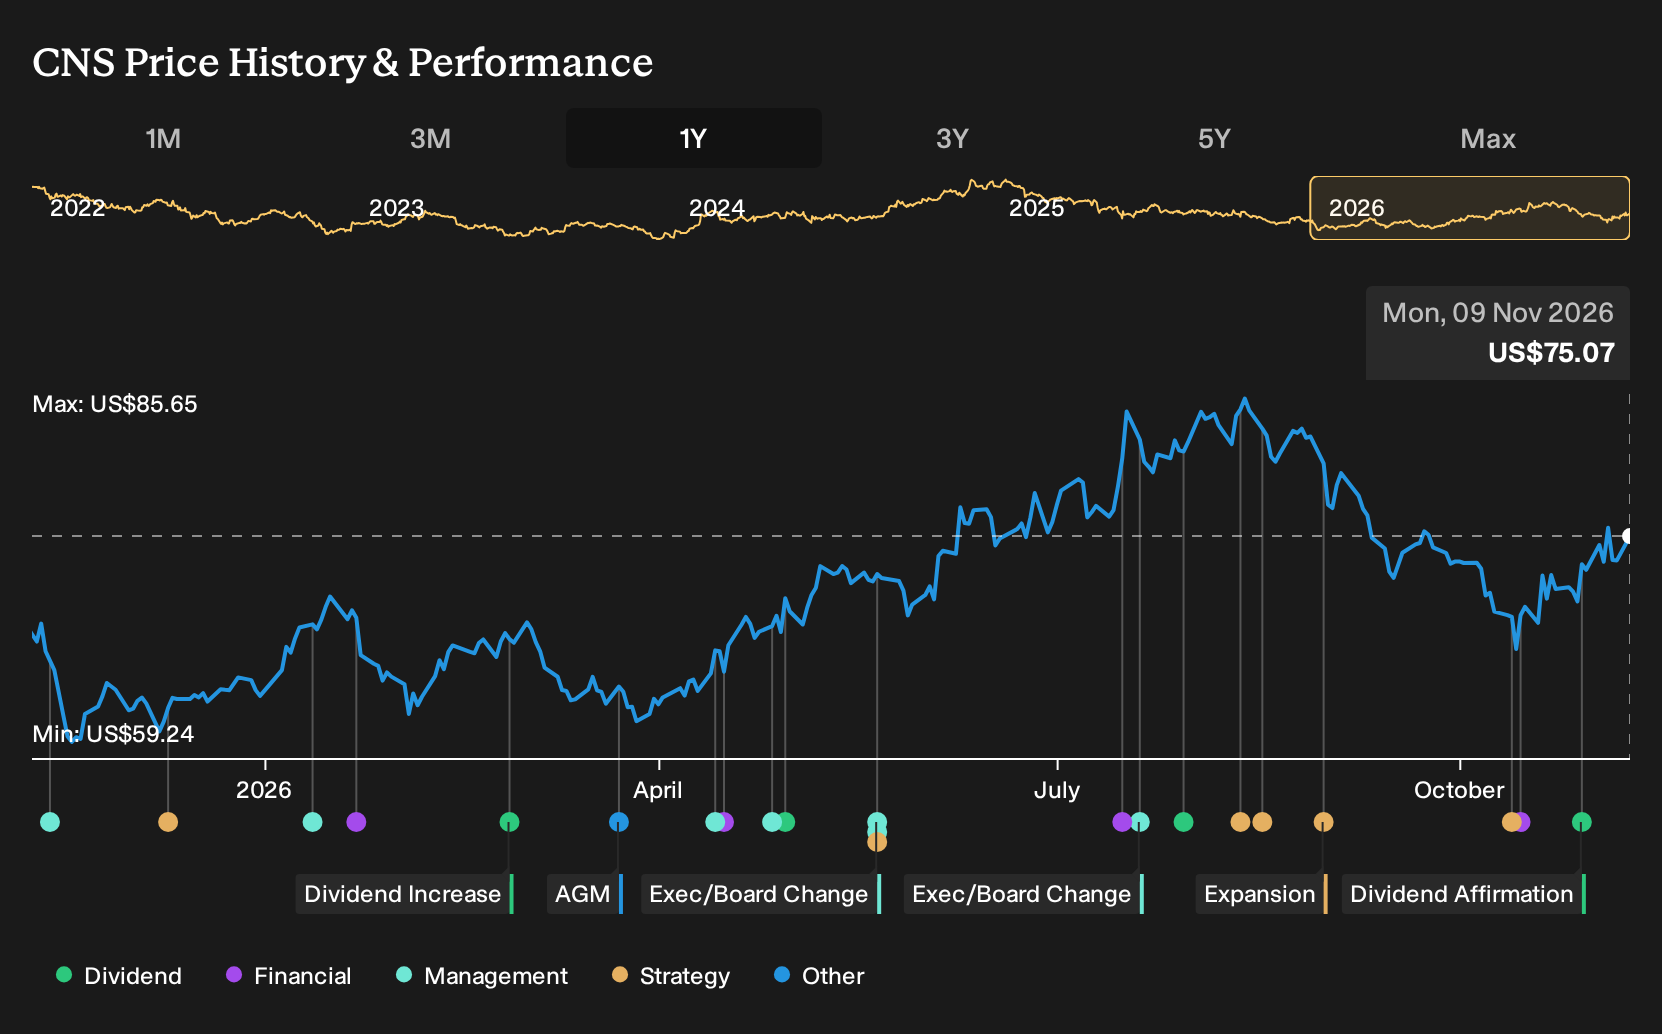
- Cohen & Steers declared a fourth quarter 2026 cash dividend of $0.67 per share, payable on November 19 to holders of record as of the close of business on November 9, with the regular ex dividend date also set for November 9.
- Preliminary assets under management were reported at $99.6 billion as of October 31, 2026, with the change primarily linked to market appreciation despite net outflows and distributions.
- The focus now turns to how Cohen & Steers' investment narrative around real assets and fee based earnings aligns with this assets under management update.
Scan how Cohen & Steers’ income profile compares by sizing up hand picked high yield opportunities in our 6 dividend fortresses with payout potential that could reshape your income mix.
Cohen & Steers Investment Narrative Recap
Cohen & Steers investors need to be comfortable with a business that lives and dies on real assets demand, fee rates and assets under management staying near the US$100b mark. The analyst consensus Narrative on Simply Wall St leans on expansion in active ETFs, private real estate vehicles and global distribution to keep that machine turning.
The latest AUM update to US$99.6b, mainly tied to market appreciation, does not really shift the short term picture. The key near term swing factor remains whether institutional outflows ease as the US$1.6b to US$1.7b mandate pipeline funds. Persistent redemptions would be the biggest drag on revenue and earnings.
The fresh US$0.67 per share cash dividend declaration matters most as a signal on how Cohen & Steers sees the durability of its fee stream. Management is keeping the payout running while AUM sits just under US$100b and while the firm absorbs higher spending on new products and distribution.
For you, that intersects directly with existing risks around cash coverage of the dividend and the heavy use of non cash earnings. If outflows accelerate or expenses tied to ETFs and private real estate stay elevated, the tension between funding the dividend and reinvesting in growth projects could become more visible in future updates.
Cohen & Steers' current analyst narrative points to forecast 2029 revenue of US$712.9 million and earnings of US$225.4 million. This is based on revenue growing at 5.9% a year and earnings rising by about US$56.6 million from US$168.8 million today.
Uncover why Cohen & Steers' fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One alternate view on Cohen & Steers treats the dividend as fragile rather than a confidence signal. The most bearish analysts were already building in about US$711.5m of 2029 revenue and US$225.5m of earnings before this announcement. You can treat that as a much harsher narrative and explore how the new dividend and AUM data might influence those assumptions in either direction.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cohen & Steers research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cohen & Steers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cohen & Steers' overall financial health at a glance.
Looking for more investment ideas beyond Cohen & Steers?
Once you have a view on Cohen & Steers, it can help to benchmark that thesis against other listed businesses with different income profiles, risk levels and balance sheet strength using the Simply Wall St Screener.
- For investors who want income without stretching too far on quality, scan a curated pool of dividend payers through 6 dividend fortresses. This can help you compare yields, payout histories and balance sheet support side by side.
- If capital preservation comes first for you, focus on resilience and balance sheet strength by filtering for companies in our 30 resilient stocks with low risk scores to see how their risk profiles stack up next to your current holdings.
- When you are hunting for underappreciated opportunities, cast a wider net with our 19 high quality undiscovered gems to spot stocks that combine solid fundamentals with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com