


EN
How Investors Are Reacting To Fifth Third Bancorp (FITB) Earnings Beat
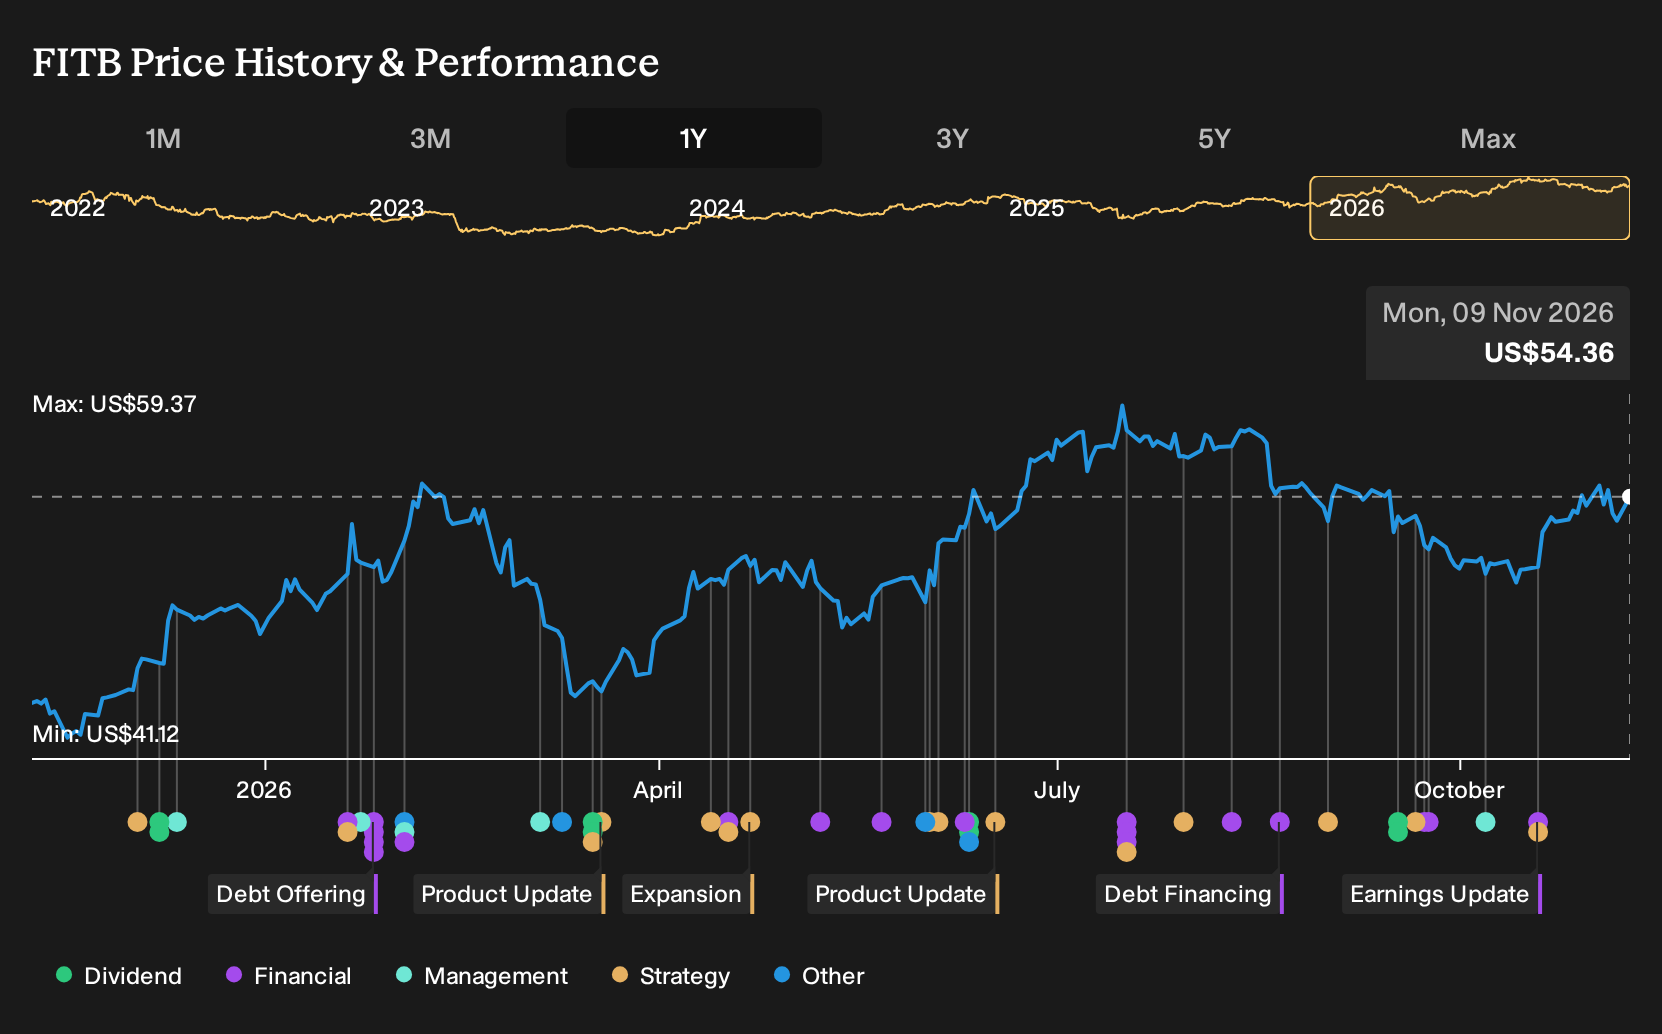
- Fifth Third Bancorp recently reported Q3 2026 adjusted EPS and revenue that came in ahead of expectations, supported by tight expense control and solid credit quality.
- The combination of better credit performance and disciplined costs suggests management is keeping asset risk and operating efficiency aligned with its broader growth ambitions.
- We will now look at how this focus on credit quality reshapes Fifth Third Bancorp's investment narrative after the latest quarterly results.
See how Fifth Third Bancorp's credit-focused playbook compares with other financially resilient banks by exploring our curated list of list of solid balance sheet and fundamentals (25 results)
Fifth Third Bancorp Investment Narrative Recap
For an investor to stay with Fifth Third Bancorp, the core belief is that its deposit led model, Comerica integration and technology investments can support earnings without taking on outsized credit risk. The latest Q3 2026 beat on adjusted EPS and revenue, helped by expense discipline and solid credit metrics, points in that direction but does not remove execution pressure.
The key near term swing factor remains how efficiently Fifth Third Bancorp converts the Comerica integration and Southeast and Southwest expansion into stable deposits and fee income while keeping service disruptions contained. The biggest immediate risk is still competitive and expensive deposit markets, where higher funding costs could eat into net interest margin even if credit quality stays resilient.
Among the moving pieces in the analyst consensus Narrative on Simply Wall St, Comerica integration looks most relevant to this latest quarter. Management is targeting at least US$850m of annual expense synergies and has already pushed through a core conversion, which ties directly into the tight cost control that supported the recent earnings surprise.
For you as a shareholder, the link to catalysts is straightforward. If Fifth Third Bancorp can keep extracting those Comerica savings, avoid recurring online banking glitches and hold on to low cost deposits, that would support the earnings trajectory analysts have outlined. If system issues or customer attrition build, the same deal that helps efficiency could quickly become the main drag.
Fifth Third Bancorp's current earnings are about US$2.2b, and analysts expect earnings to reach roughly US$4.3b by 2029, implying an earnings increase of about US$2.1b. Revenue is projected to rise to about US$16.4b by that same year based on a forecast annual revenue growth rate of 17.7%.
Uncover how Fifth Third Bancorp's fair value indicates a 13% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$61.54 to US$97.47, so you are seeing retail forecasts that stretch from cautious to very optimistic on Fifth Third Bancorp. Set those opinions against risks around deposit costs and Comerica related tech glitches, and the spread in expectations makes sense. Use that gap to explore several alternative viewpoints rather than rely on a single story.
Explore 2 other Fifth Third Bancorp fair value estimates, including one that suggests it could be worth just $61.54.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fifth Third Bancorp research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Fifth Third Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fifth Third Bancorp's overall financial health at a glance.
Looking For More Ideas Beyond Fifth Third Bancorp?
Once you have a view on Fifth Third Bancorp, widening the lens to other opportunities can help balance risk and return across your portfolio.
- For investors who want growth potential at lower share prices, review 11 elite penny stocks with strong financials that pair smaller market caps with stronger financial profiles.
- If value and balance sheet strength matter most to you, scan through 33 high quality undervalued stocks that combine resilient finances with attractive pricing.
- For readers who prefer stability and fewer shocks, consider 30 resilient stocks with low risk scores that score well on fundamental resilience and risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com