


EN
Earnings Update Could Be A Game Changer For Universal Display Stock (OLED)
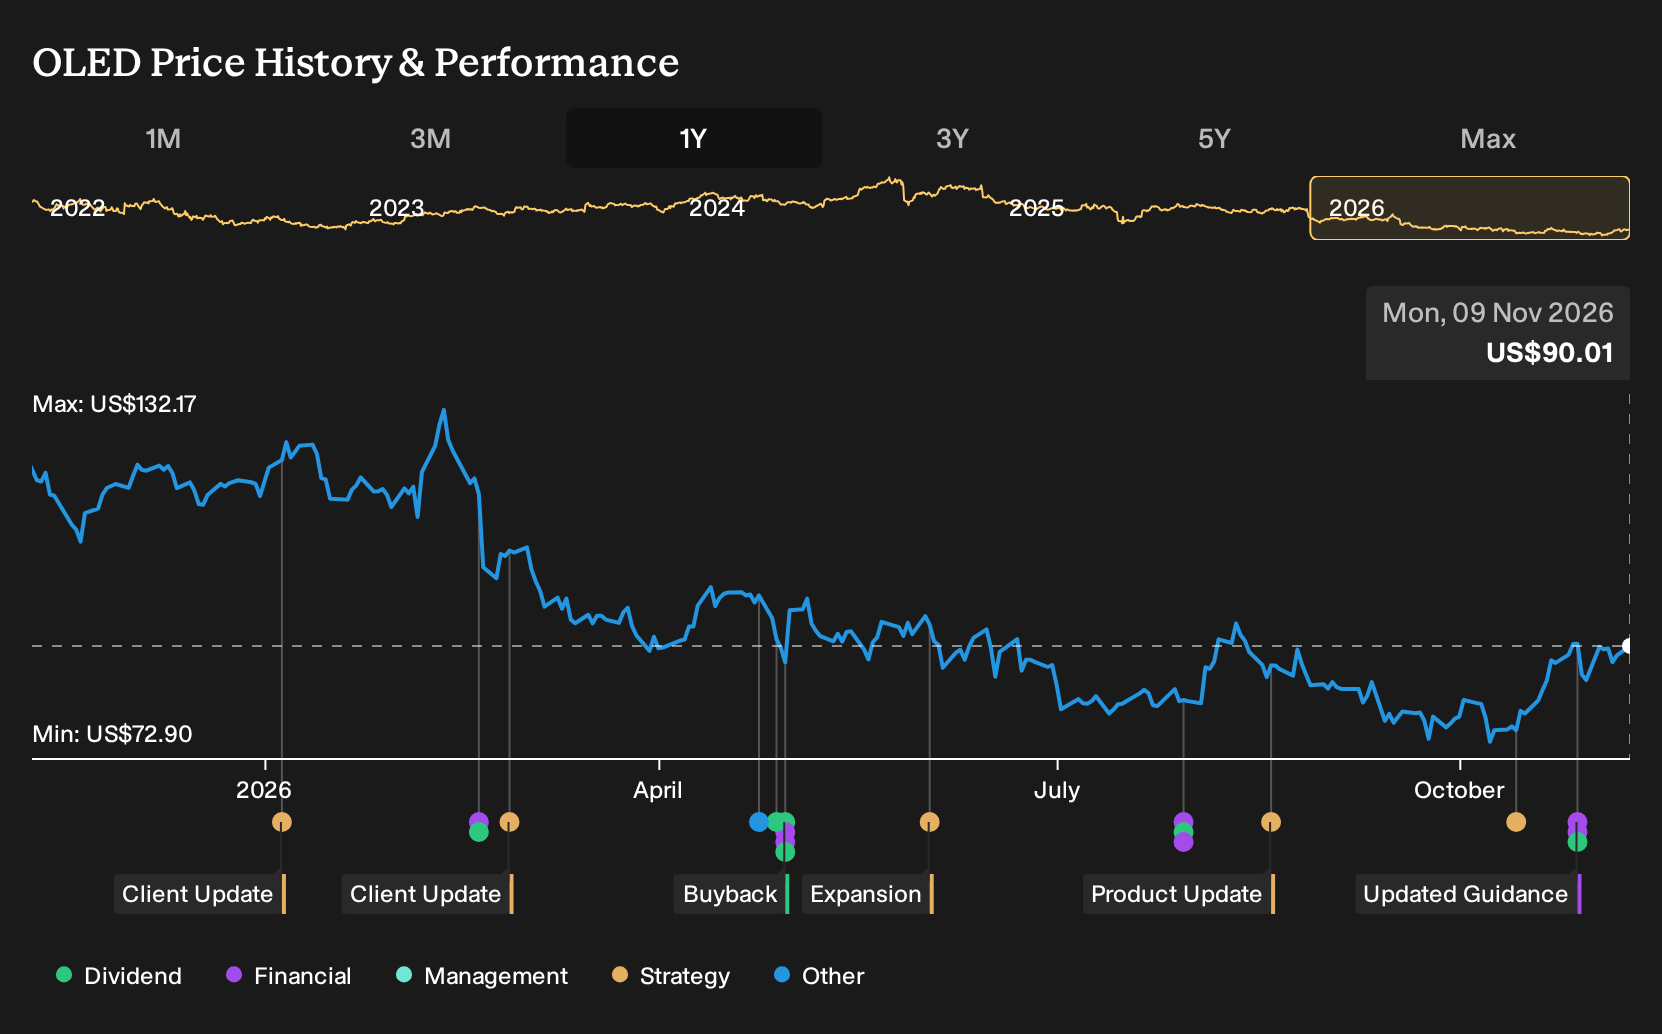
- Universal Display reported third quarter 2026 revenue of US$160.43 million and net income of US$78.95 million, reaffirmed full year 2026 revenue guidance toward the lower end of US$630 million to US$670 million, confirmed a US$0.50 fourth quarter dividend, and completed a US$127 million share buyback tranche.
- The mix of stronger quarterly profitability, steady capital returns and a guidance range that points to pressure on full year sales provides a clear snapshot of how Universal Display is balancing near term demand headwinds with an ongoing commitment to shareholder payouts and disciplined use of cash.
- This piece will examine how Universal Display's investment narrative is influenced by strong quarterly earnings alongside guidance toward the lower end of the full year range.
Scan how Universal Display’s mix of earnings strength, buybacks and dividends compares with other companies returning cash to investors by screening for 6 dividend fortresses in today's market.
Universal Display Investment Narrative Recap
To own Universal Display, you need to believe the OLED materials and licensing model remains attractive even when handset demand is soft and customer ordering is lumpy. The analyst consensus Narrative on Simply Wall St leans on wider adoption in IT, automotive and new architectures, while current 2026 guidance toward the low end keeps expectations for near term momentum in check.
The key near term catalyst is clearer evidence that demand for OLED materials stabilises as new Gen 8.6 capacity ramps and customer inventories normalise. The main risk is that weaker smartphones and erratic material volumes persist into 2027, which would keep revenue growth constrained and limit operating leverage from that installed capacity.
The clearest disclosure for this debate is management reiterating that 2026 revenue is tracking toward the lower end of the US$630 million to US$670 million range. That sits beside a third quarter where revenue reached US$160.43 million and net income was US$78.95 million. The concern is therefore less about one quarter and more about the run rate.
For catalysts, that guidance effectively pushes more of the OLED material volume story into later periods and focuses attention on adoption in laptops, monitors and cars, as well as the eventual commercial use of phosphorescent blue. For risk, it underlines that large announced fab spending and new architectures do not automatically turn into near term orders if end device demand stays uneven.
Universal Display's narrative projects US$807.3 million revenue and US$269.5 million earnings by 2029. This assumes 10.0% yearly revenue growth and an earnings increase of about US$73.9 million from US$195.6 million today.
Uncover why Universal Display's fair value indicates a 28% potential upside to its current price, a discount that could narrow more quickly than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Universal Display’s potential operating leverage. Before this guidance update, that group was mapping out 10.2% annual revenue growth and earnings of about US$294.6 million by 2029. You can treat this as one possible path, and then weigh how today’s guidance and dividend news might reshape those forecasts.
Explore 4 other Universal Display fair value estimates, including one that suggests as much as 28% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment results often come from independent thinking, so consider your own analysis carefully.
- A great starting point for your Universal Display research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Universal Display. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Universal Display's overall financial health at a glance.
Looking for more investment ideas beyond Universal Display?
If you want to put Universal Display in context, it helps to scan a broader watchlist of potential opportunities and compare business quality, balance sheet strength and income potential across the market.
- For investors who care most about financial resilience and clean balance sheets, start with a list of solid balance sheet and fundamentals (25 results) that can help you filter for companies with stronger fundamentals.
- If your priority is limiting downside risk, you may prefer a 30 resilient stocks with low risk scores that narrows the field to businesses with more stable risk profiles.
- Those hunting for mispriced opportunities can review a 19 high quality undiscovered gems that highlights lesser known stocks with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com