


EN
Cactus (WHD) Could Be 15% Undervalued After Middle East Expansion And Strong Earnings
Cactus (WHD) drew fresh attention after reporting third quarter revenue of $430.89 million and net income of $62.16 million, along with board approval for a $0.15 quarterly dividend on Class A shares.
The recent facility approval in the Middle East and strong quarterly results have come after a mixed stretch for Cactus. The share price has gained 28.98% year to date but declined 15.80% over 90 days, while the 1-year total shareholder return of 41.30% suggests longer term momentum has still been positive.
Power up your research beyond Cactus by scanning our hand picked 42 power grid technology and infrastructure stocks.Cactus has rallied hard over 12 months but slipped over the past quarter, and fresh Middle East expansion adds another layer of risk. Does the current valuation still compensate you for that trade off or not?
Most Popular Narrative: 15% Undervalued
Cactus closed at $60.66, while the analyst consensus Narrative on Simply Wall St puts fair value at $71.56 based on a 7.5% discount rate and long range cash flow and earnings assumptions. That framework views the stock as undervalued and ties a lot of the upside to how well Cactus executes outside the US.
The acquisition of a majority interest in Baker Hughes' Surface Pressure Control business is now being expressed through the Cactus International platform, which carries a backlog focused on the Middle East and is being repositioned toward Asia, Africa, and Latin America. Incremental contracts from these regions would feed directly into future Pressure Control revenue and earnings.
See why 9 investors see Cactus as 15% undervalued.
Result: Fair Value of $71.56 (UNDERVALUED)
Still, tariff shocks on imported steel and slower than planned Cactus International synergies could reverse the Cactus undervaluation story.
Find out about the key risks to this Cactus narrative.
Another View: What Cactus' P/E Is Telling You
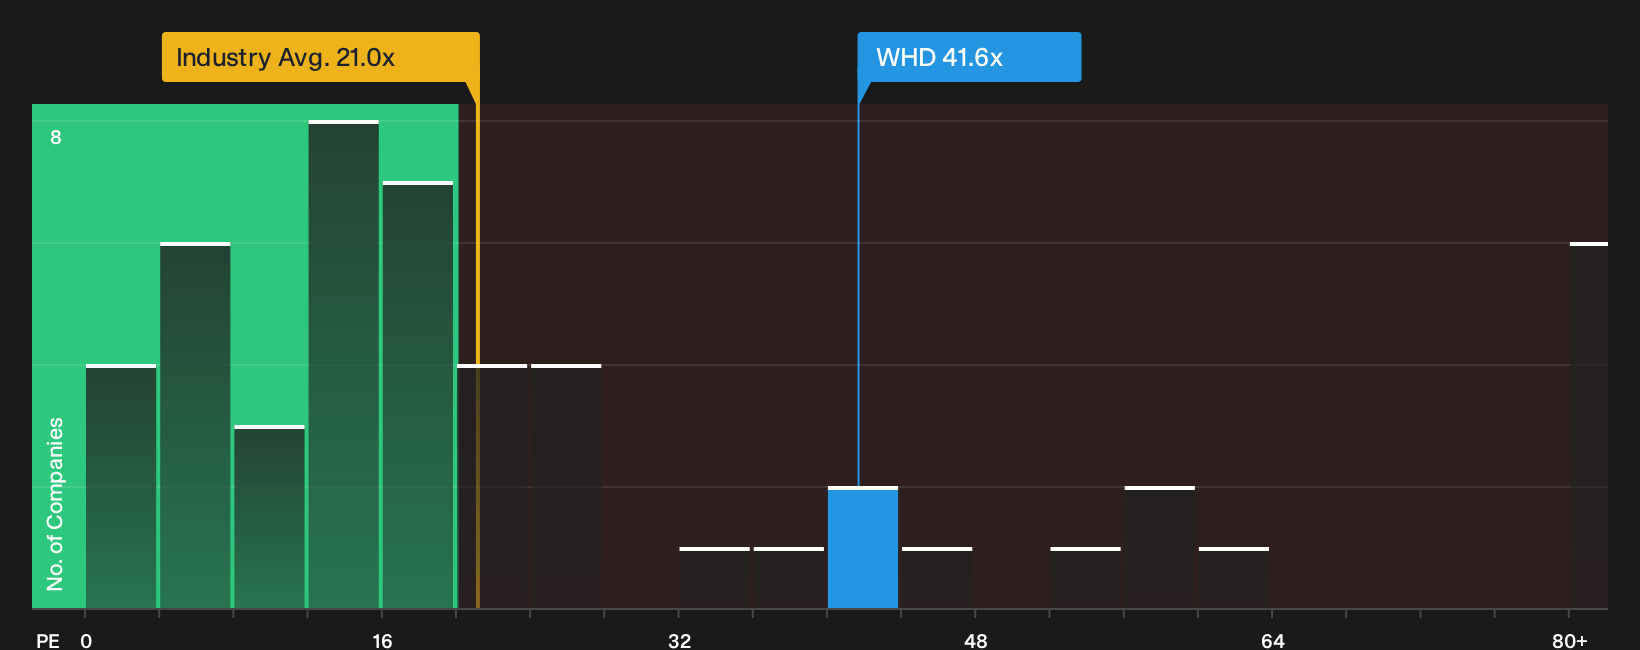
The DCF work on Cactus points to undervaluation, yet the current P/E of 41.6x tells a different story. That multiple is much higher than the US Energy Services industry on 21x, peers on 26.5x, and the fair ratio of 23.2x that the market could move toward. If sentiment cools and the P/E drifts closer to that fair ratio, how comfortable are you with the downside that would create even if the business keeps hitting its forecasts?
For a closer look at how the earnings multiple stacks up against fundamentals, valuation history, and peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Cactus has a bullish valuation story in parts and a punchy P/E that hints at real downside risk if sentiment cools. Act while the data is fresh and stress test the bullish and bearish angles for yourself by weighing the 2 key rewards and 2 important warning signs.
Looking for more Cactus investment ideas beyond this stock?
If you stop with Cactus, you risk missing other opportunities that fit your goals. Use the screener to quickly surface focused, data driven ideas.
- Zero in on potential value opportunities by checking companies that appear mispriced on quality and fundamentals through our 33 high quality undervalued stocks.
- Build a more resilient portfolio by filtering for businesses with stronger finances using the list of solid balance sheet and fundamentals (25 results).
- Spot potential future standouts early by scanning a 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com