


EN
Does Flat Third Quarter Earnings Change The Bull Case For Patrick Industries Stock (PATK)?
- Patrick Industries reported third quarter 2026 results with sales of US$975.28 million and net income of US$21.06 million, alongside lower basic and diluted earnings per share than a year earlier.
- Flat sales but weaker profitability point to pressure on Patrick Industries margins and cost structure. This raises questions about how efficiently the business is converting its broad end market exposure into earnings.
- We will now look at how Patrick Industries investment narrative may be affected by weaker third quarter earnings and compressed profitability.
Patrick Industries Investment Narrative Recap
To stay invested in Patrick Industries, you need to believe the business can turn a flat top line into healthier earnings through better cost control, product mix and the planned LCI merger synergies described in the analyst consensus Narrative on Simply Wall St. The latest quarter, with US$975.28 million of sales and softer earnings, keeps the focus squarely on margins rather than demand.
The key near term catalyst remains management execution on content per unit gains in RV and Marine, along with progress on working capital and debt. The biggest risk is that weaker RV retail, elevated inventories and pricing support to OEMs keep squeezing profitability. This would limit how quickly Patrick Industries can improve cash generation.
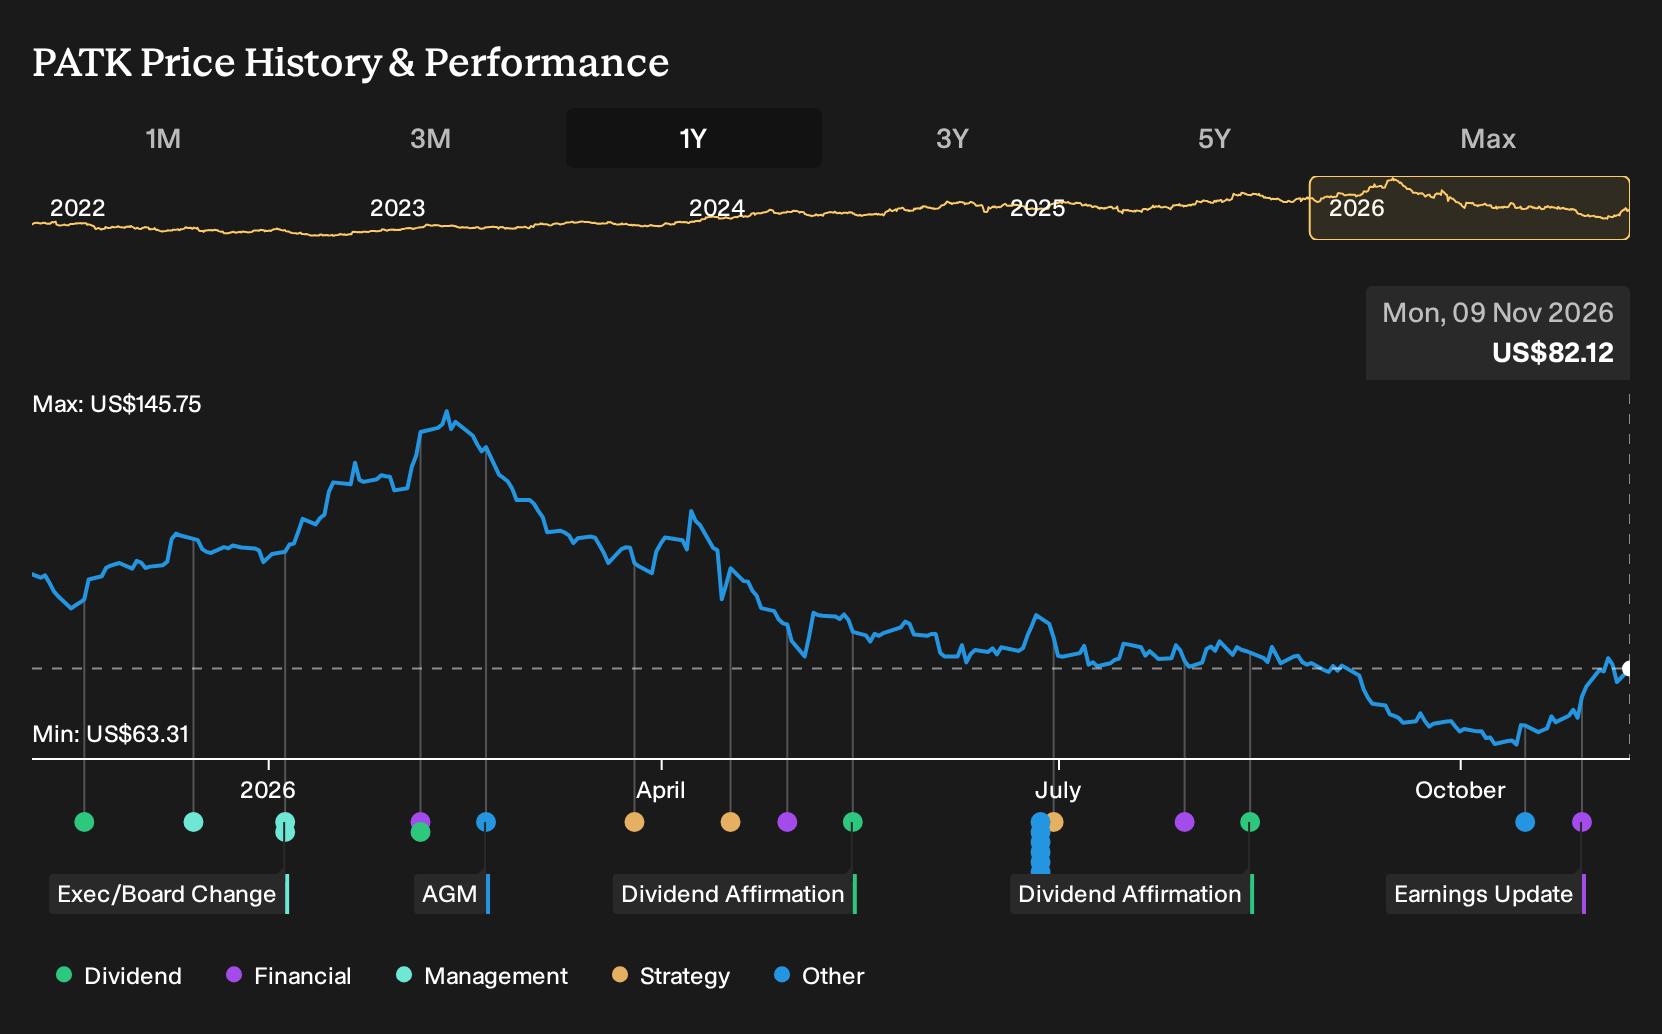
The third quarter earnings announcement on 29 October 2026 is the clearest reference point for these catalysts. Sales of US$975.28 million were broadly similar to a year earlier, while net income of US$21.06 million and both basic and diluted EPS from continuing operations were lower. This highlights the current profit squeeze at Patrick Industries.
That set of results connects directly to the merger and diversification story. Content per unit, aftermarket expansion and the targeted US$150 million of cost synergies with LCI sit against a backdrop of compressed earnings today. For you as a shareholder, the operational question is whether management can ease working capital and margin strain before those longer term benefits fully show up.
Patrick Industries' outlook projects US$4.4b in revenue and US$229.9 million in earnings by 2029. This is based on revenue increasing at 3.6% per year and an earnings rise of about US$82.6 million from US$147.3 million today.
Uncover why Patrick Industries' fair value indicates a 23% potential upside to its current price, before that discount closes.
Exploring Other Perspectives
One alternate view around Patrick Industries focuses on margin repair through automation and AI tools. The lowest analysts were already cautious before this earnings release, even while assuming revenue of about US$4.6b and earnings of roughly US$265.6 million by 2029. After a weaker quarter and upcoming conference appearances, that more pessimistic story could easily evolve.
Explore 3 other Patrick Industries fair value estimates, including one that suggests as much as 9% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Patrick Industries research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Patrick Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Patrick Industries' overall financial health at a glance.
Looking for more investment ideas beyond Patrick Industries?
Once you have a view on Patrick Industries, it can help to compare it with other businesses that score well on balance sheet strength, valuation, or income potential using the Simply Wall St Screener.
- If resilience matters most to you, start with companies that pair sturdy finances with measured risk by reviewing the 30 resilient stocks with low risk scores.
- If you care about price paid versus quality received, scan for businesses combining strong fundamentals with attractive pricing through the 33 high quality undervalued stocks.
- If consistent income is your focus, look at companies targeting higher yields that still aim for stability via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com