


EN
3 Indian Growth Stocks With Revenue Growth Over 24%
Asian technology shares have just bounced after a rough patch, reminding investors how quickly sentiment can swing when confidence returns. That kind of mood shift can shine a light on fast growing Indian businesses where insiders still own a meaningful slice of the equity. This article walks through three such stocks from a high growth, high insider ownership screen so you can see which traits long term focused management is backing with their own capital.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where both analysts and management see room for further progress. However, if you want the absolute best, these 45 high growth high conviction stocks are the cream of the crop.
Rubicon Research (NSEI:RUBICON)
Rubicon Research develops specialty pharmaceutical products across pain management, cardiovascular, central nervous system and other therapies, using its RubiReten and RubiSRL drug delivery platforms to create differentiated formulations. The business generates about ₹21 billion from pharmaceutical products and related services, and the stock carries a market value near ₹293.3 billion.
The fast growing formulation focus and high insider backing make Rubicon Research a natural fit for this screener. The analyst consensus Narrative on Simply Wall St highlights how current expansion plans could shape that trajectory.
"Expansion of US manufacturing capacity through the New Jersey facility and preparation of the Pithampur site in India is expected to support a higher own manufacturing share and can support gross margin resilience and operating EBITDA over time."
What investors need to weigh now is how one unresolved pressure on future cash generation might influence that margin story.
To see how that cash flow question could accelerate or stall Rubicon Research from here, read the full narrative for Rubicon Research to understand what management’s plans are really signalling.

Tonbo Imaging India (NSEI:TONBO)
Tonbo Imaging India builds electro optical and infrared sensors such as thermal imaging cores, weapon sights and missile guidance units that plug directly into fast growing defense and security programs worldwide. The stock is valued at about ₹86.7b.
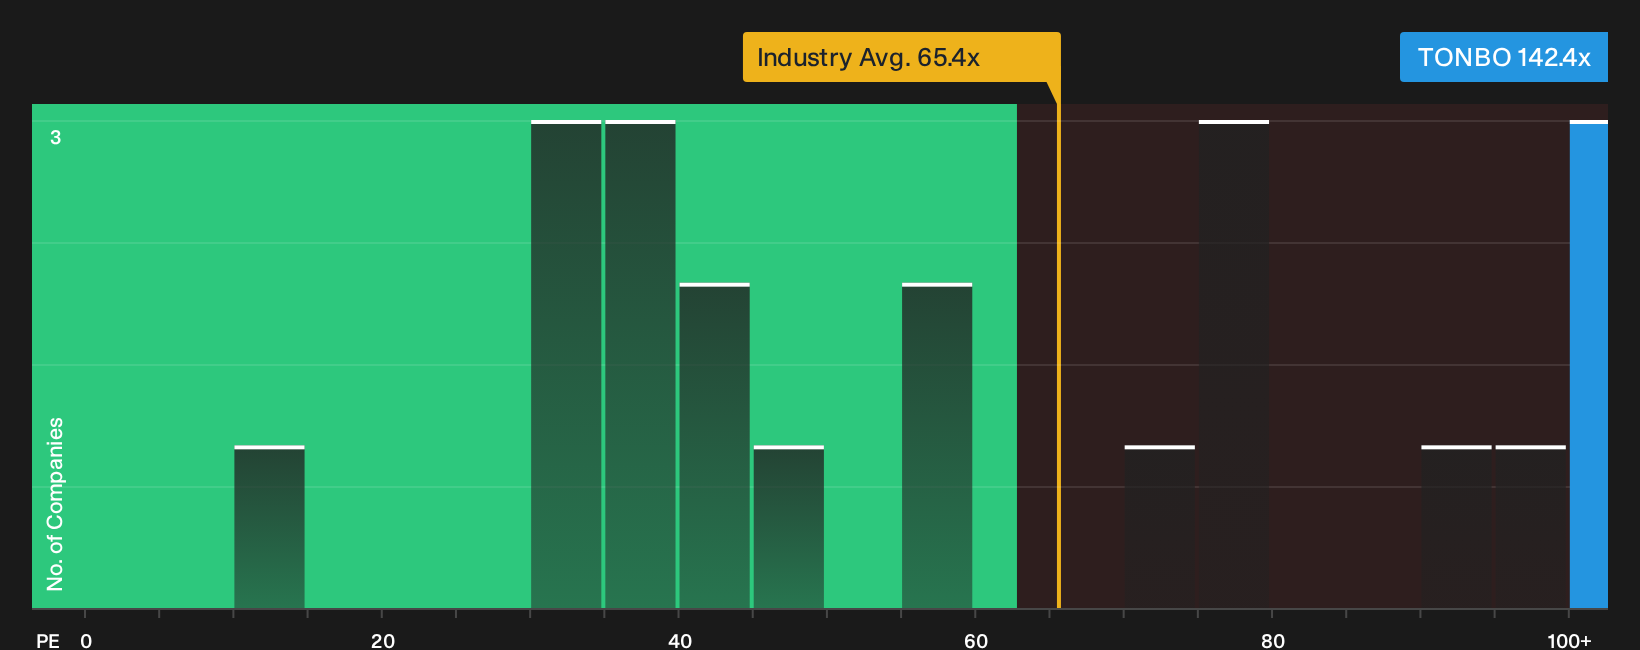
Forecast revenue growth of 31.8% a year and earnings growth of 45.7% place Tonbo Imaging India in the fast growing, high insider ownership camp. However, the rich 142.4x P/E means a lot already rides on how one less visible pressure shapes future cash conversion.
That kind of pressure is exactly what the 1 key reward and 2 important warning signs (2 are major!) could be masking for Tonbo Imaging India, especially if sentiment turns faster than cash flow.
Bajel Projects (NSEI:BAJEL)
Bajel Projects runs EPC work for power transmission and distribution, building EHV lines, substations, monopoles and underground cabling that tie directly into India’s electricity build out. The stock is valued at about ₹18.3b.
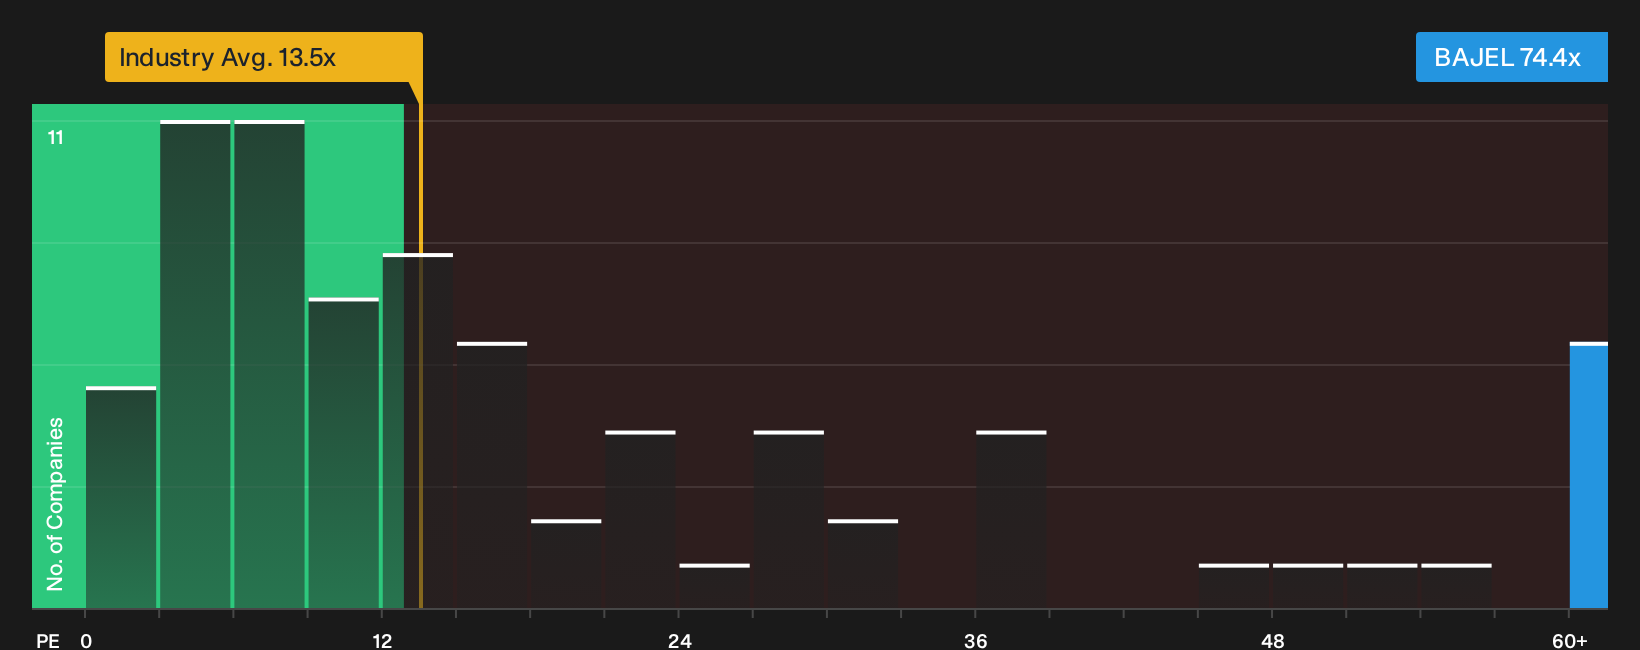
Bajel Projects links tightly to this fast growing, high insider ownership theme. Earnings grew 91.4% last year and analysts expect more than 60% annual profit expansion. However, the stock trades on a rich 74.4x P/E, which appears demanding given the current level of expectations.
With that kind of valuation tension already baked in, the analysis report for Bajel Projects shows where Bajel Projects earnings momentum could either validate the premium or start to lag expectations.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. By the time momentum is flying, early entries are gone and prices are already caught up. Scan these under the radar lists while it matters and get in early.
- Spot sturdier income plays before yields get compressed by latecomers by running the 222 dividend fortresses that focuses on payouts which the market has not fully crowded yet.
- Catch under followed opportunities while expectations stay modest by reviewing the 572 high quality undiscovered gems that highlights businesses screened for stronger fundamentals hiding in plain sight.
- Ride the shift toward electrification while many investors still watch from the sidelines by checking the 42 power grid technology and infrastructure stocks built around critical grid technology and infrastructure operators.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com