


EN
Rollins (ROL) Climbed, But What Is Behind The Fresh Attention?
Rollins (ROL) is back in focus after its third quarter 2026 report showed adjusted earnings of $0.34 a share and revenue of $1.09 billion, both coming in below consensus forecasts.
Despite the earnings miss, Rollins shares have bounced sharply in the short term, with a 1-month share price return of 21.14% and a 7-day move of 7.52%. However, the year-to-date share price return has fallen 34.35% and the 1-year total shareholder return has declined 32.75%, leaving longer term total shareholder returns over 3 and 5 years at 4.29% and 15.54% respectively.
Scan beyond Rollins and explore how other high quality businesses with supportive valuations are setting up right now through our curated 33 high quality undervalued stocks.
Rollins just bounced hard after a weak quarter, yet the stock is still well below where it started the year. Does that recent jump leave enough potential upside to justify taking on the current risks as the valuation section begins?
Most Popular Narrative: 139% Overvalued
On the narrative view, Rollins screens as expensive. Esteban assigns a fair value of $16.20 per share versus the latest close at $38.74, which frames the recent rebound as a move within what they see as an already stretched range.
Rollins is the dominant pure-play compounder in global pest control, a structurally necessary, recession-resistant service business that has grown revenue for 24 consecutive years and delivered ROIC of 23 to 31% for 12 consecutive years, without a single year of ROIC below 21% even through COVID-19. The investment thesis rests on three mutually reinforcing pillars: (1) a Wide Moat rooted in switching costs, commercial customers cannot switch providers without triggering compliance risk, and residential customers renew habitually at annual price increases of 3 to 4% above CPI without meaningful churn; (2) a proven M&A flywheel that converts a fragmented industry of 34,000+ U.S. operators into compounding route density and FCF, completing 30 to 45 bolt-on acquisitions annually at disciplined multiples with zero reported impairments; and (3) a capital-light business model with minimal reinvestment needs, generating FCF of $678M in FY2025 on $3.76B of revenue.
See why 10 investors see Rollins as 139% overvalued.
Result: Fair Value of $16.20 (OVERVALUED)
Still, the Rollins story carries pressure points, including any setback in acquisition pacing or a weaker return profile on those deals that challenges the wide moat narrative.
Find out about the key risks to this Rollins narrative.
Another View: Rollins Through a Cash Flow Lens
The narrative flags Rollins as sharply overvalued at a fair value of $16.20, yet our DCF model tells a different story. On those cash flow assumptions, the stock at $38.74 trades about 13.1% below an estimated value of $44.60, which frames the pullback as a potential discount rather than excess. Which set of assumptions do you trust more: the user fair value or the cash flow model.
Look into how the SWS DCF model arrives at its fair value.
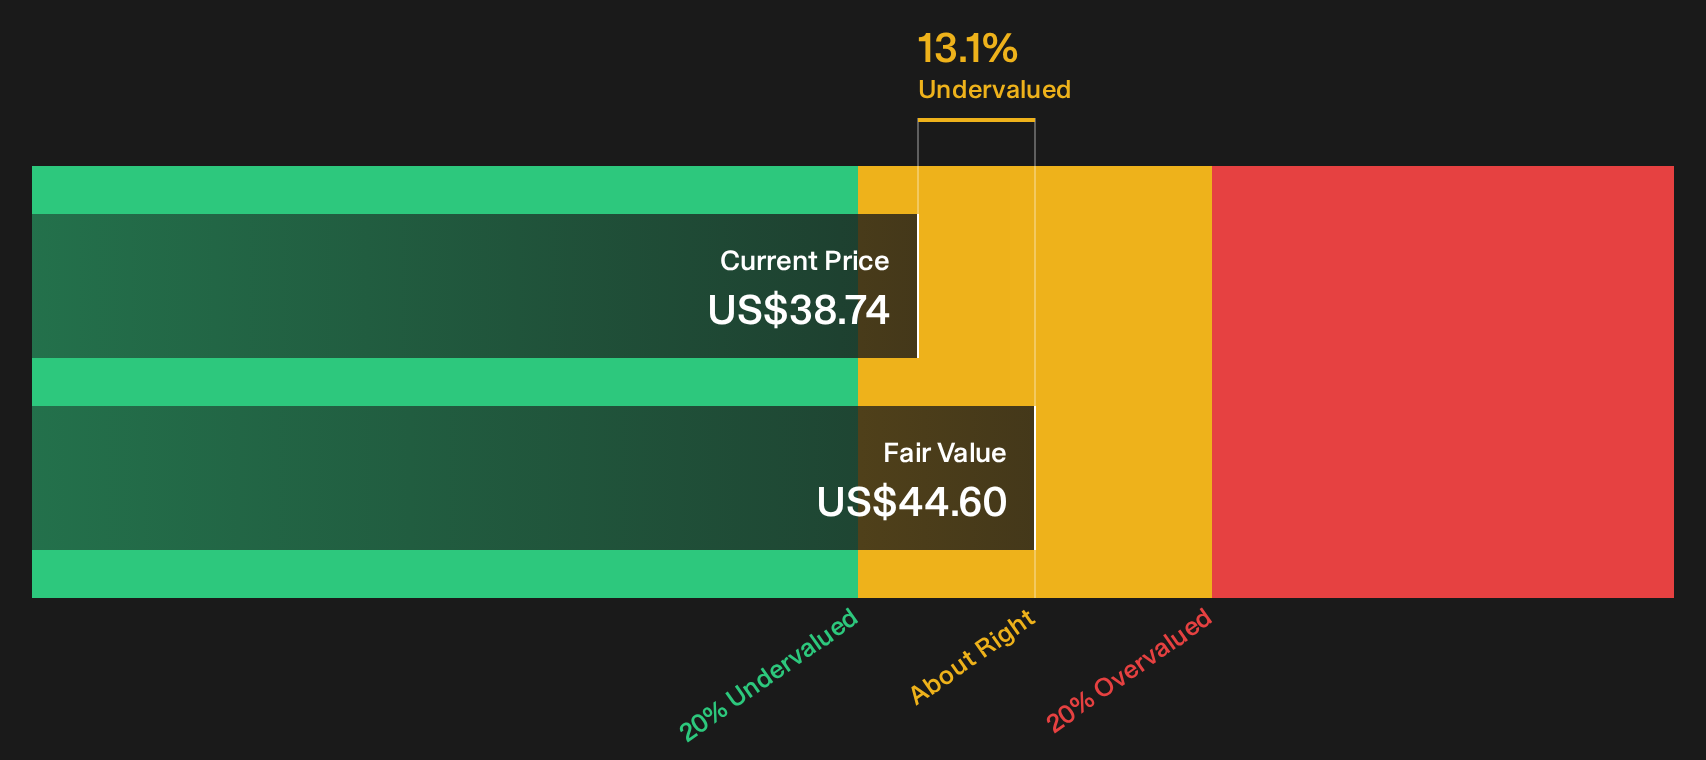
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rollins for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Rollins valuation and risk reward profile can be useful, as long as you interrogate the numbers yourself and move quickly to your own stance. To see the key positives and pressure points side by side, start with the 3 key rewards and 2 important warning signs.
Looking for more Rollins-sized investment ideas?
If Rollins has sharpened your focus, now is the moment to widen your watchlist and actively hunt for other opportunities before the next move leaves you behind.
- Target reliable cash generators by scanning a curated list of solid balance sheet and fundamentals (25 results) that filters for sturdier finances and cleaner fundamentals.
- Hunt for underfollowed potential by reviewing a 19 high quality undiscovered gems that highlights quality businesses investors often overlook.
- Dial down portfolio stress and search a 30 resilient stocks with low risk scores tailored to companies with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com