


EN
Did Earnings Guidance Lift Just Shift General Dynamics (GD) Stock Narrative?
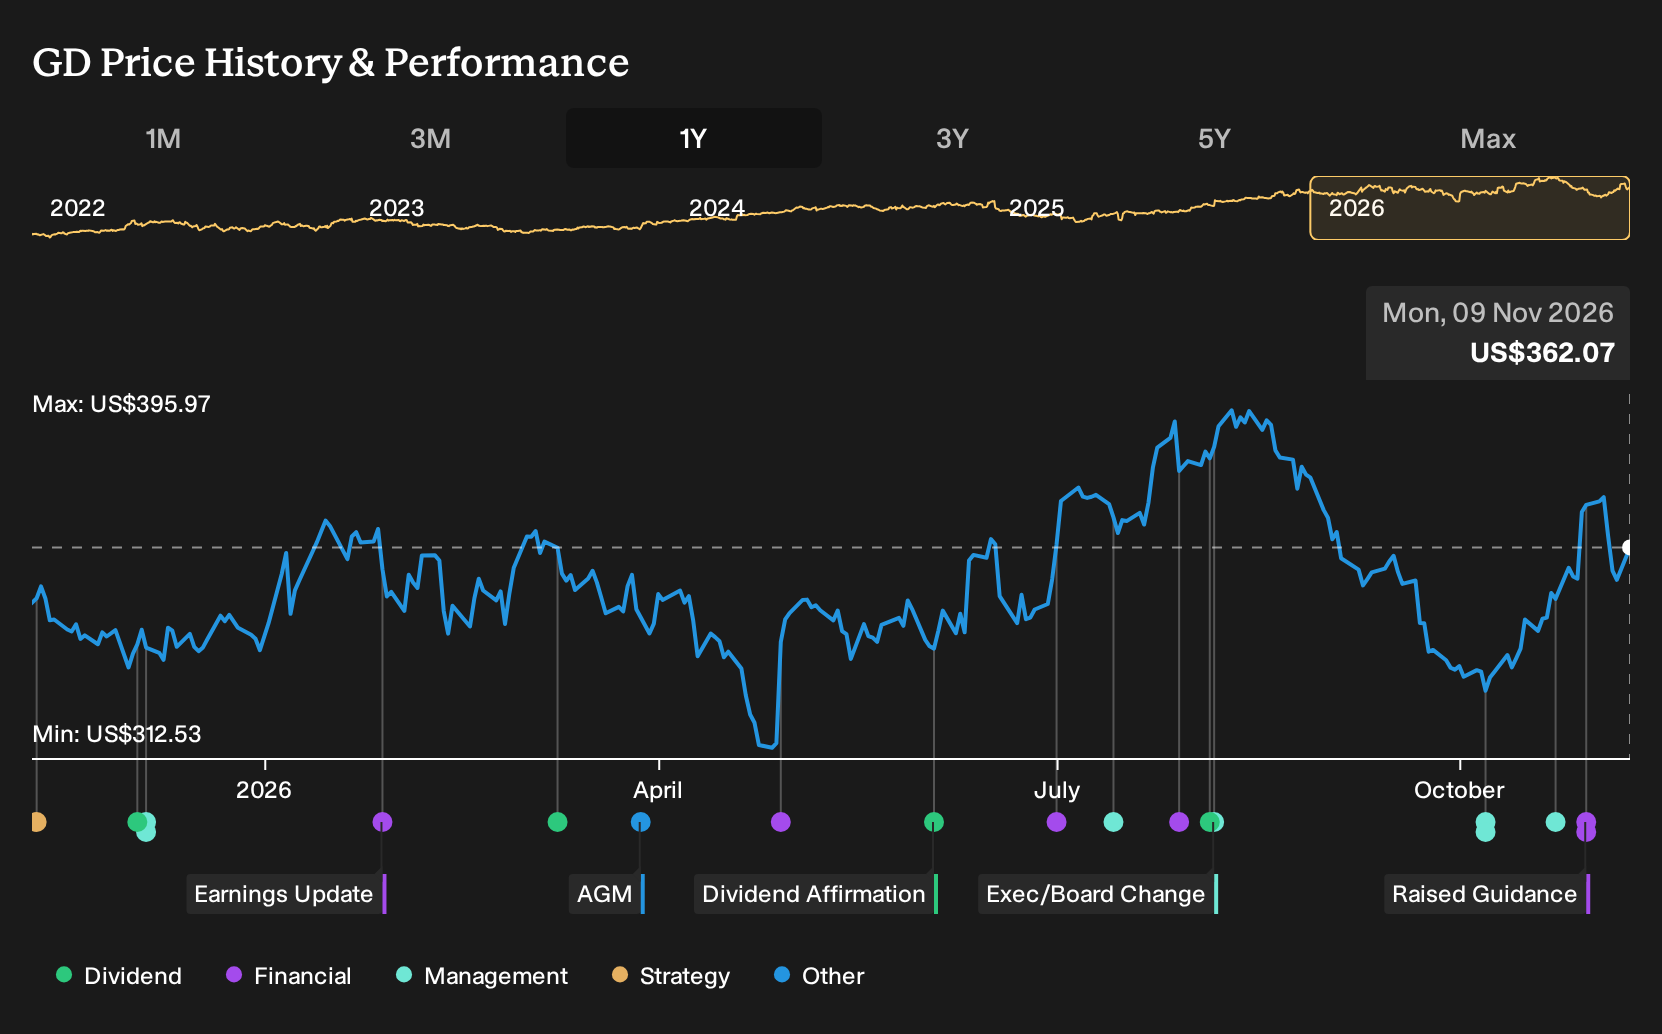
- General Dynamics raised its 2026 earnings outlook several times, most recently guiding to US$17.20 to US$17.30 diluted EPS on US$56.5b to US$56.8b revenue and about 10.5% operating margin, after reporting higher third quarter and year to date profit and sales compared with a year earlier.
- The pattern of repeated guidance increases, alongside higher quarterly EPS, suggests management sees current operational momentum as strong enough to support tighter, more ambitious full year financial targets.
- We will now look at how General Dynamics' higher full year EPS guidance could reshape the broader investment narrative around the business.
General Dynamics Investment Narrative Recap
To own General Dynamics, you need to believe in a long runway of contracted defense work and a steady aerospace and IT services engine that can absorb bumps in any one segment. The raised 2026 EPS guidance to US$17.20 to US$17.30 assumes management can keep execution tight and operating margin around 10.5%.
The key short term catalyst remains proof that programs like submarines and Gulfstream jets can be delivered on schedule while holding margins near current levels. The biggest near term risk is cost or supply chain pressure on large, complex defense contracts that could make higher revenue less attractive if profitability slips.
The latest quarterly earnings release is the clearest reference point for this upgraded outlook. For the third quarter, General Dynamics reported US$14.566b in revenue and US$1.229b in net income, with diluted EPS from continuing operations of US$4.49 compared with US$3.88 a year earlier. That gives you a concrete baseline for the higher full year EPS target.
Across the first nine months of 2026, revenue reached US$42.141b and net income was US$3.514b. According to CentryResearch, an investor in the Simply Wall St Community, the record submarine backlog and improving shipyard efficiency are key supports for the story, while fixed price contracts and supplier constraints remain the operational swing factors to watch as this guidance gets tested.
CentryResearch values General Dynamics at US$370.92 a share, based on revenue growing about 5.5% a year and future profit margin reaching 9.0%. Together, these factors support a higher earnings base that, in this framework, justifies that long-term fair value estimate.
Uncover why General Dynamics' fair value is essentially aligned with its current price.
Exploring Other Perspectives
Five fair value views from the Simply Wall St Community span roughly US$371 to US$466 a share for General Dynamics, with some holders seeing far more upside than others. Those opinions were formed before the latest guidance lift and earnings report, so you may want to reassess them in light of the tighter 2026 EPS outlook.
Explore 4 other General Dynamics fair value estimates, including one that suggests up to 29% potential increase from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own judgment.
- A great starting point for your General Dynamics research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for General Dynamics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate General Dynamics' overall financial health at a glance.
Looking for more investment ideas beyond General Dynamics?
Once you have a view on General Dynamics, it can help to compare that thesis with other companies that share some of the qualities you care about, whether that is value, resilience, or balance sheet strength. The Simply Wall St Screener is built for this kind of side by side work, so you can stress test your thinking instead of relying on a single story.
- If you want companies that trade below what their fundamentals may support, start with a focused set of value opportunities through the 33 high quality undervalued stocks.
- If capital preservation ranks high for you, tilt your search toward businesses with steadier profiles by running the 30 resilient stocks with low risk scores.
- If financial robustness is non negotiable in your process, filter for firms with stronger balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com