


EN
Record Occupancy Might Change The Case For Investing In Regency Centers Stock (REG)
- Regency Centers reported third quarter 2026 revenue of US$419.06 million and net income of US$78.54 million, while also declaring higher common and preferred dividends and updating full year earnings guidance to net income of US$2.31 to US$2.33 per diluted share.
- Management highlighted record leased occupancy, raised its same property NOI growth outlook and detailed over US$170 million of selectively funded acquisitions, indicating a focus on disciplined expansion in a competitive, higher rate transaction market.
- The focus now turns to how Regency Centers' updated earnings outlook and record occupancy may influence the longer term investment narrative.
Scan how Regency Centers' selective acquisitions and dividend profile compare with other income-focused real estate stocks by reviewing our curated 6 dividend fortresses.
Regency Centers Investment Narrative Recap
To own Regency Centers, you need to believe its grocery anchored suburban centers can stay full and productive, while the development pipeline and selective acquisitions add rentable space without stretching the balance sheet. The recent quarter showed record leased occupancy and higher same property NOI guidance, which supports that operating story even as headline EPS guidance was trimmed.
The near term swing factor is execution on the US$680 million plus development pipeline and the more than US$170 million of recent acquisitions in a higher rate world. The biggest risk is that funding costs and tenant stress chip away at returns before new projects and centers fully contribute.
The common dividend increase to US$0.800 per share a quarter sits at the center of this update. For an income focused REIT like Regency Centers, a higher payout right after lowering full year net income guidance puts more focus on how durable cash generation really is against the current rent roll and leasing activity.
For you as a shareholder, that dividend decision links directly to the catalysts in the analyst consensus Narrative on Simply Wall St, which leans on recurring free cash flow and a visible project pipeline. Execution on developments and acquisitions will now be judged against the higher cash commitment, especially if interest expenses or tenant issues start to pressure margins.
Regency Centers' narrative projects US$1.8b revenue and US$520.5 million earnings by 2029. This assumes 2.0% yearly revenue growth and an earnings decrease of about US$22 million from US$542.5 million today.
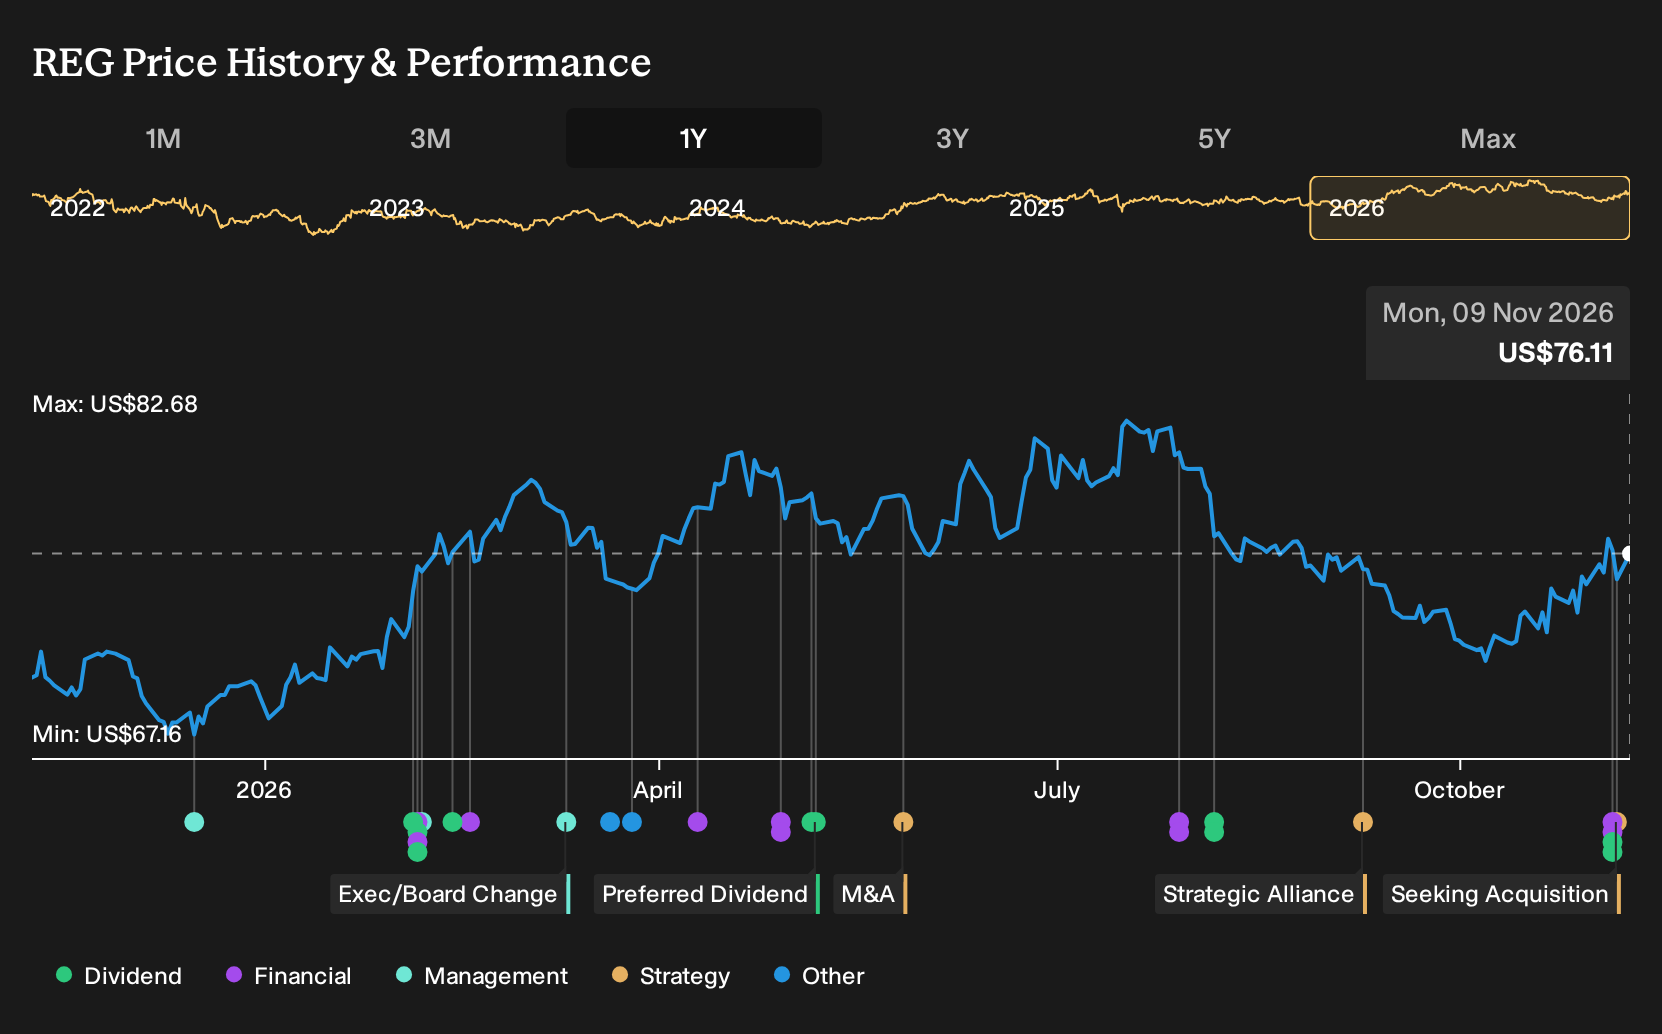
Uncover why Regency Centers' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$84 to US$105 per share, which already shows how far opinions on Regency Centers can stretch. When you set those views against the mix of higher dividends, a large development pipeline and interest rate pressure, you quickly see why you should compare several alternative viewpoints before deciding how its performance could evolve.
Explore 2 other Regency Centers fair value estimates, including one that suggests it could be worth just $84.28.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Regency Centers research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Regency Centers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Regency Centers' overall financial health at a glance.
Looking For More Investment Ideas Beyond Regency Centers?
Once you have a view on Regency Centers, it can help to line it up against other opportunities that fit similar goals, whether that is income, quality, or resilience in tougher conditions.
- If you want income without ignoring balance sheet strength, start by scanning our 6 dividend fortresses that aim to pair yield with financial robustness.
- For investors who care most about paying a fair price for quality, sort through the 33 high quality undervalued stocks and see which businesses match your risk and return preferences.
- If you prefer quieter opportunities that still have solid fundamentals, filter the 19 high quality undiscovered gems and compare those candidates with what you see in Regency Centers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com