


EN
Valero Energy (VLO) Could Be 16% Undervalued After Reaffirming Its Dividend
Valero Energy (VLO) just reaffirmed its shareholder payout, with the board declaring a regular quarterly cash dividend of $1.20 per share, payable on December 21, 2026, to holders of record on November 24.
Dividend reassurance is landing alongside mixed price action for Valero Energy, with the share price up 2.97% over the past day yet down 17.75% across 30 days, while a 115.81% year to date share price return and 103.32% one year total shareholder return suggest that longer term momentum has been strong even as shorter term sentiment cools.
Scan for other refiners with strong balance sheets and meaningful shareholder returns using our curated list of 6 dividend fortresses.
After a sharp pullback, yet with a share price still below both analyst targets and some fair value estimates, is the market simply cautious on Valero Energy or mispricing its refining strengths and dividend commitment?
Most Popular Narrative: 16% Undervalued
Valero Energy's last close at $356.75 sits below the analyst consensus Narrative fair value of $426.42, which points to a meaningful valuation gap while still baking in softer revenue and earnings forecasts. The analyst consensus Narrative on Simply Wall St leans heavily on refining conditions, capital discipline, and payout policy to support that fair value.
The main thing that has to go right is that Valero maintains strong refining and low carbon fuel profitability while keeping capital discipline and high shareholder payouts in the face of ongoing policy and regulatory uncertainty.
The numbers imply that Valero Energy’s current share price, after an 88.1% rise over the past year and new price targets in the $400 to $450 range, already reflects a full valuation with limited room for error.
See why 69 investors see Valero Energy as 16% undervalued.
Result: Fair Value of $426.42 (UNDERVALUED)
Still, the fair value story for Valero Energy can unravel quickly if refining margins reset lower or if large asset impairments hit reported earnings and balance sheet strength.
Find out about the key risks to this Valero Energy narrative.
Another View: Valero Energy Through The P/E Lens
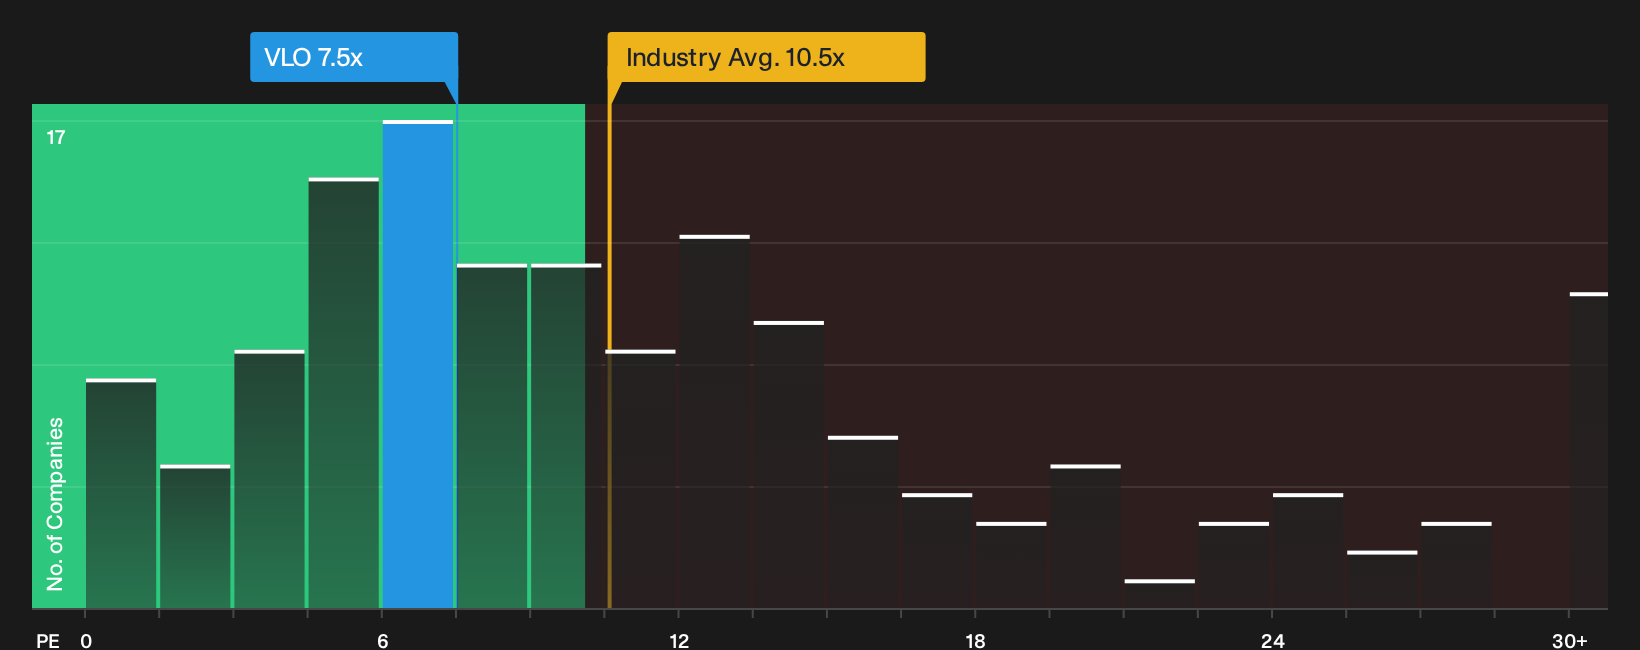
There is a very different message when you look at Valero Energy through its current P/E ratio of 7.7x. That level is lower than the US Oil and Gas sector at 10.5x and also below the fair ratio estimate of 10.4x, yet above the peer average of 5.8x. For investors trying to reconcile those gaps, the question is whether this reflects a margin of safety or simply richer pricing than closer comparables.
To see how this price tag lines up against earnings power in practical terms, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mixed tone on Valero Energy has you torn, do not wait for consensus to harden. Consider both sides of the debate with the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Valero Energy?
Do not park cash on the sidelines while you debate Valero Energy. Put it to work by lining up a watchlist of fresh, high conviction ideas.
- Target reliable income by reviewing mature businesses that prioritize cash returns through the 6 dividend fortresses.
- Hunt for quality at a discount and filter for potential bargains using the 33 high quality undervalued stocks.
- Spot future leaders early by scanning robust fundamentals with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com