


EN
Is New Earnings Guidance Altering The Investment Case For TriMas Stock (TRS)?
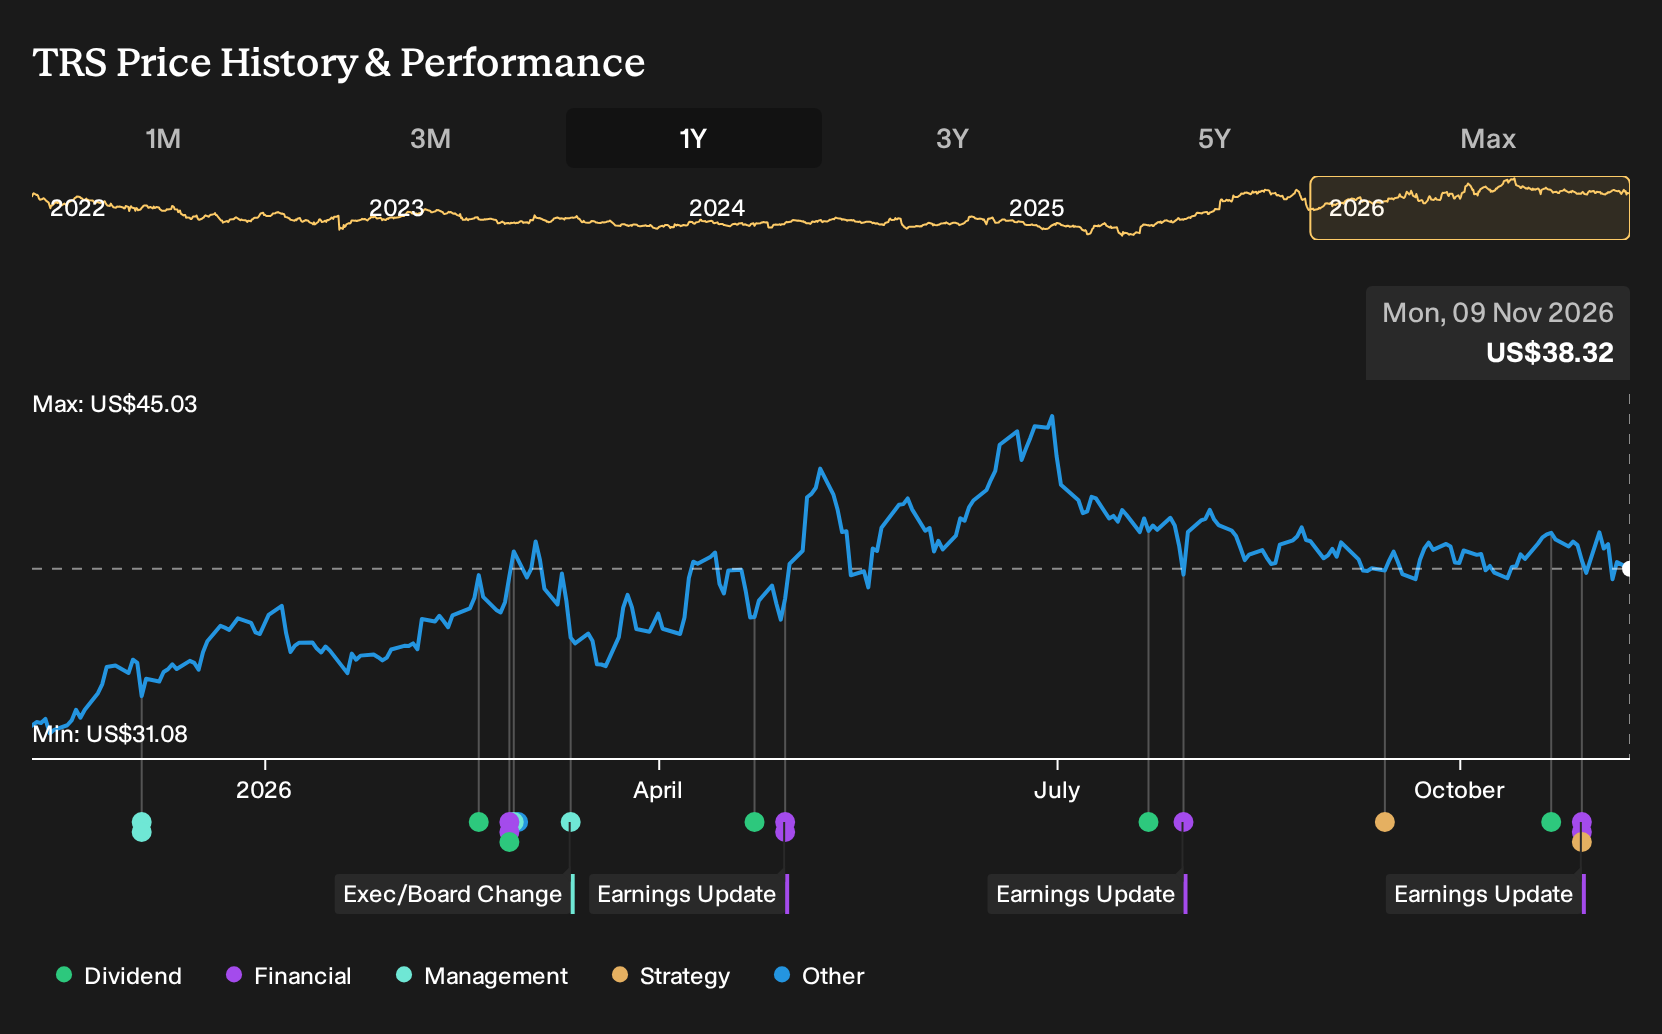
- TriMas Corporation reported third quarter 2026 sales of US$178.74 million and net income of US$19.36 million, and issued full year 2026 GAAP diluted EPS guidance of US$1.06 to US$1.13.
- The very large jump in nine month net income to US$833.56 million and diluted EPS of US$22.69 highlights how recent corporate actions and capital structure changes are now flowing through the income statement.
- We will assess how TriMas' sharp earnings shift and new 2026 EPS outlook relate to the existing investment narrative and assumptions.
Scan how TriMas’ sharp earnings reset compares with other companies that have strong balance sheets and fundamentals in our curated list of solid balance sheet and fundamentals (25 results).
TriMas Investment Narrative Recap
To own TriMas, you need to believe the Packaging and Specialty Products focus can support consistent earnings from dispensing systems, closures and steel cylinders, while the operational excellence program and cost savings actually reach the income statement. The new 2026 GAAP diluted EPS guidance of US$1.06 to US$1.13 provides a clearer near term anchor, but it does not fully settle the longer horizon debate in the analyst consensus Narrative on Simply Wall St.
The very large nine month net income and diluted EPS jump raises high quality earnings questions, particularly given the identified high level of non cash earnings. In the short term, the key catalyst is execution on integration and cost reduction, as well as resolving inefficiencies in Specialty Products. The main risk is that tighter packaging sustainability rules or weaker demand in parts of the portfolio gradually erode margins.
The most relevant announcement here is the 2026 GAAP EPS outlook. Management now expects diluted earnings per share of US$1.06 to US$1.13. This gives a reference point for comparing the longer term earnings projections and the current P/E multiples discussed earlier. That range also sits alongside the recent quarterly diluted EPS of US$0.53 and nine month diluted EPS of US$22.69.
This updated EPS band connects directly to the existing catalysts around cost savings and portfolio focus, because it converts those initiatives into a specific figure for the coming year. It also relates to the risk that a high valuation multiple may not develop, since any reassessment of earnings quality or sustainability exposure will now be evaluated against the new 2026 guidance.
TriMas' narrative projects US$730.4 million revenue and US$41.3 million earnings by 2029. This implies revenue growth of 3.2% a year and an earnings decline of US$42.2 million from US$83.5 million today.
Uncover why TriMas' fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for TriMas from the Simply Wall St Community span only 2 submissions, from US$4.52 at the low end to US$45 at the top. That spread sits beside management’s new 2026 EPS guidance and the planned cost savings program, which could change how you and other investors judge future earnings quality.
Explore another TriMas fair value estimate, including one that suggests as much as 88% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your TriMas research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TriMas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TriMas' overall financial health at a glance.
Looking For More Investment Ideas Beyond TriMas?
Once you have formed a view on TriMas, it can help to line that up against other opportunities that match your risk tolerance and style, using a structured screener rather than instinct alone.
- For investors hunting for underappreciated opportunities with solid business profiles, start with a focused set of companies that appear mispriced based on fundamentals through 33 high quality undervalued stocks.
- If capital preservation matters as much as upside, narrow your list to businesses with stronger balance sheets and resilient financial profiles by scanning the 30 resilient stocks with low risk scores.
- When you want quality but also like the idea of finding stories earlier in their journey, use the 19 high quality undiscovered gems to surface lesser followed stocks with promising fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com