


EN
Should ETF Buying Require Action From First Solar Stock Investors?
- First Solar reported Q3 2026 sales of US$1,230.94 million with net income of US$571.06 million and announced a US$500 million share repurchase alongside lower full year net sales and volume guidance.
- ETF inflows of US$10.9 million into First Solar across 33 buying funds indicate renewed institutional interest despite softer sales guidance and reduced 2026 volume targets.
- The focus now is on how First Solar's earnings, together with trimmed 2026 guidance and the new buyback program, shape the investment narrative.
First Solar Investment Narrative Recap
To own First Solar, investors need to believe that its thin film modules, paired with U.S. policy support and a long-term contracted book, can keep earnings power resilient even when sales are choppy. According to Andrei_Niculescu, an investor in the Simply Wall St Community, that policy-backed backlog is central to the story. The latest quarter fits that narrative, with net income of US$571.06 million on US$1,230.94 million of sales, even as full-year net sales and volume guidance were trimmed.
The key short-term swing factor looks like execution on volumes and pricing as 45X credits and domestic content rules flow through reported profitability. Lowered 2026 net sales guidance to US$4.6 billion to US$4.9 billion and volume guidance to 16.0 GW to 17.0 GW does not appear to break that thesis, although it keeps attention on risks Andrei_Niculescu flags around policy changes, SE Asia underutilization and any pause in U.S. utility scale demand.
The new US$500 million share repurchase plan is the announcement that ties closest to this earnings update. It sits alongside strong Q3 net income and higher earnings per share, with basic EPS from continuing operations at US$5.31 for the quarter and US$12.48 for the first nine months. For existing holders, the program means future earnings and 45X credits, if maintained, are spread over a potentially smaller share count.
For prospective investors, the buyback also sits next to operational catalysts and risks already in motion. The South Carolina facility that onshores finishing for Series 6 Plus modules may help cut tariff and freight drag, while the trimmed 2026 sales outlook keeps focus on whether U.S. bookings stay healthy and policy support like 45X and tariff regimes remain intact. Execution on CuRe technology and management’s ability to manage SE Asia underutilization remain central tasks.
On those figures, the US$263.00 fair value that Andrei_Niculescu sets for First Solar flows from an 18.3% annual revenue growth assumption, a future profit margin of 32.5%, and a mid-teens P/E multiple applied to earnings that the narrative views as already visible in the contracted backlog.
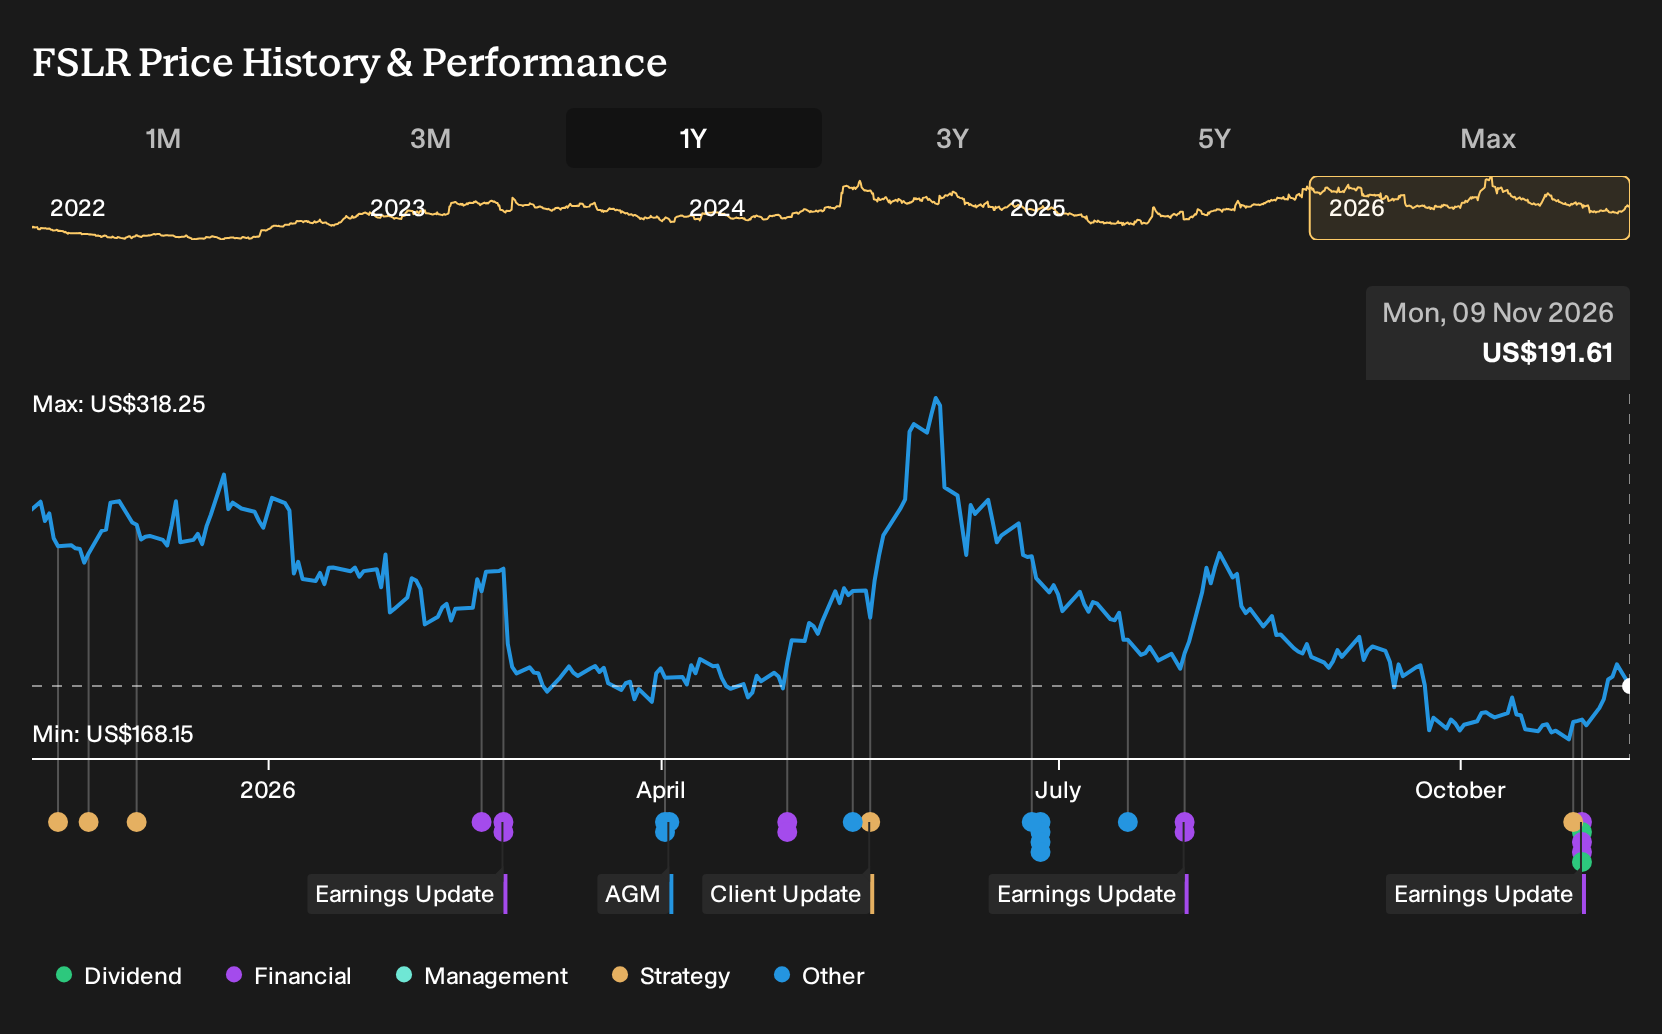
Uncover why First Solar's fair value indicates a 37% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One point the most cautious analysts watch is earnings quality at First Solar. Before this Q3 update, the lowest forecasts were for revenue of about US$5.6b and earnings of roughly US$2.3b by 2029, paired with an 11.3x P/E. That view assumes today’s strong profitability fades, so this new guidance cut and buyback may push those expectations to shift.
Explore 6 other First Solar fair value estimates, including one that suggests it could be worth just $254.70!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Solar research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for First Solar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate First Solar's overall financial health at a glance.
Looking for more First Solar investment ideas?
If First Solar has sharpened your interest in the wider market, it can help to line it up against a broader watchlist built around clear financial traits rather than headlines.
- If capital preservation is your first filter, start with companies screened for resilience through a 30 resilient stocks with low risk scores that score well on risk metrics and balance sheet strength.
- If you want income on top of potential capital gains, focus on businesses offering reliable payouts through a 6 dividend fortresses that highlights higher yielding candidates.
- If you are hunting for under-covered opportunities with solid fundamentals, broaden your radar with a 19 high quality undiscovered gems that may not yet be on most investors’ screens.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com