


EN
Will Raised Revenue Guidance Change ChemoMetec Stock Narrative
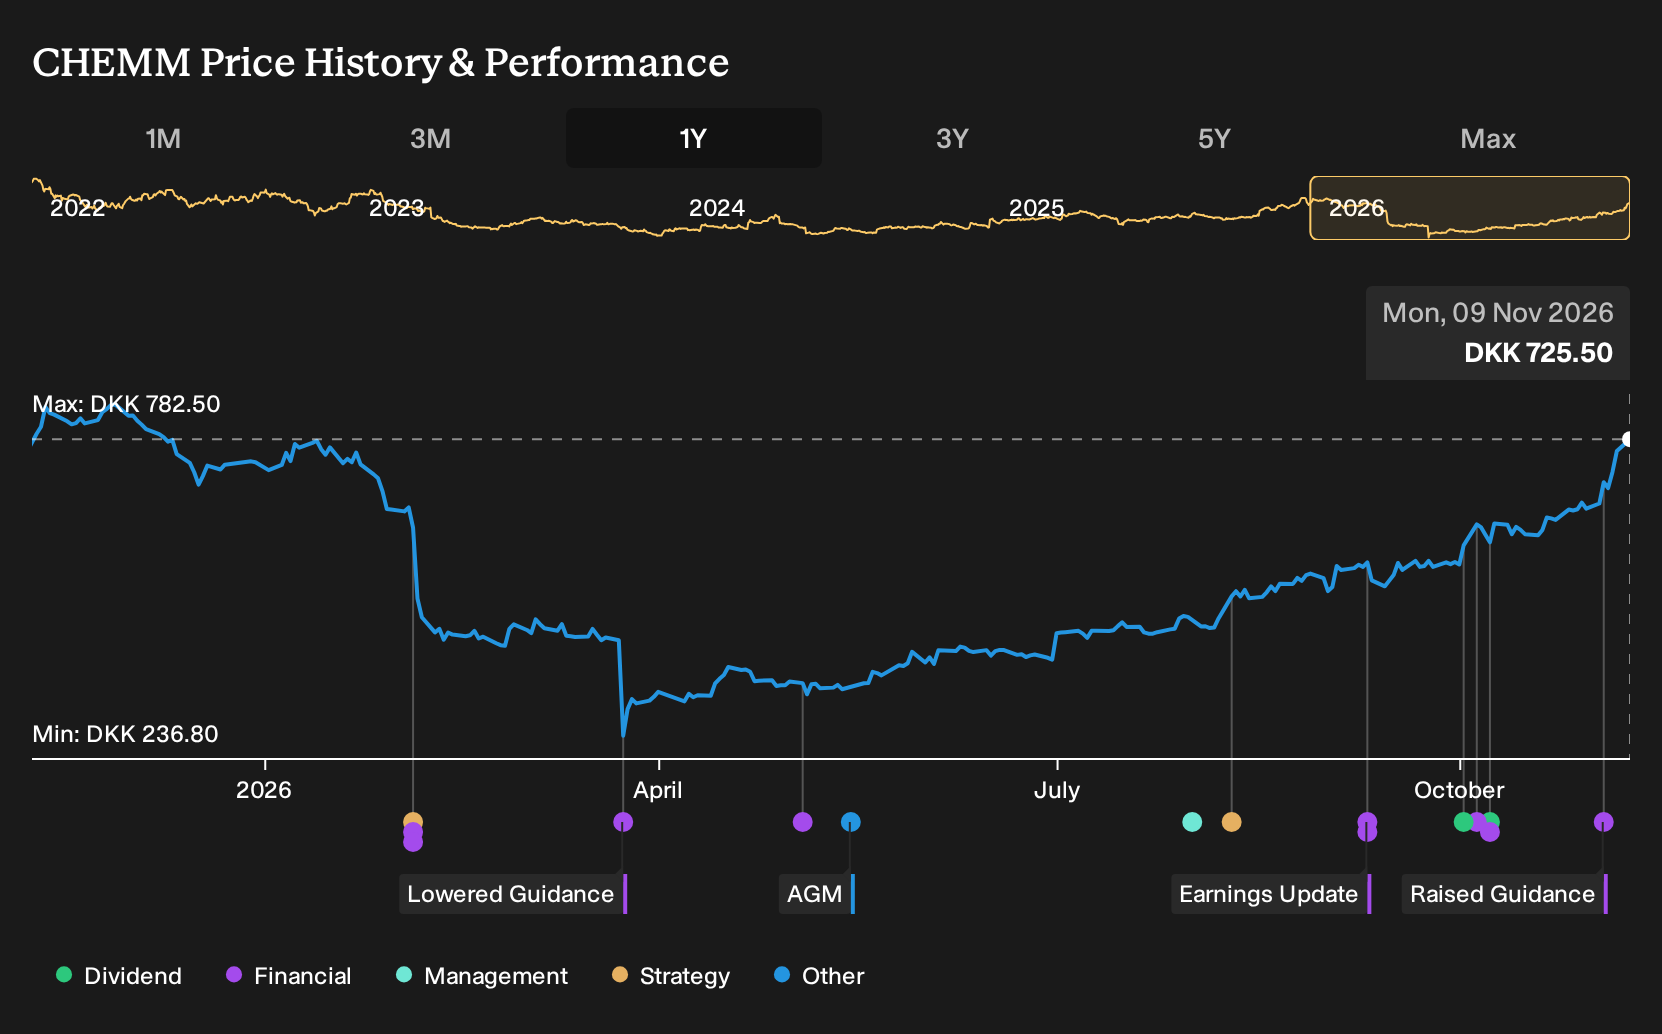
- ChemoMetec A/S raised its 2026/27 revenue guidance to a DKK 570 million to 605 million range, up from DKK 560 million to 590 million, reflecting updated expectations for the current financial year.
- The higher revenue outlook highlights how integration of ChemoMetec's XcytoMatic systems into automated workflows with partners such as Hamilton, Tecan and Roche is becoming a more central commercial focus.
- We will now look at how ChemoMetec's upgraded revenue guidance could influence the investment narrative built around automation and software.
Scan the wider automation theme by sizing up hand picked peers to ChemoMetec in our 91 robotics and automation stocks that plug hardware and software into end to end lab workflows.
ChemoMetec Investment Narrative Recap
For a shareholder in ChemoMetec, the core belief is that automation, software and higher value instruments in cell and gene therapy will keep drawing labs onto its platforms. The guidance lift is a small adjustment rather than a step change, so the key near term catalyst still sits with execution on XM systems and NC 200 replacement, not this upgrade on its own.
The biggest operational risk remains that heavy spending on product development and growth initiatives does not translate into broad adoption of XM Octopus, sample management or fleet software. If uptake disappoints, free cash flow and EBITDA margins could feel the strain just as the revenue mix leans further toward instruments over consumables.
The analyst consensus Narrative on Simply Wall St already framed the multiyear switch from NC 200 to NC 203 and XcytoMatic systems as a central driver. The new revenue outlook links directly to that idea, because it reinforces how management is leaning into automation, fleet management and integration with partners like Hamilton, Tecan and Roche as the main way to scale usage.
There is no fresh company announcement beyond the guidance change itself. The cleanest read through for you is on execution risk and timing. If XM placements, software attach rates and validation cycles for big biopharma customers track in line with that narrative, the guidance range looks achievable, but delays or weaker consumables usage per instrument would keep that the key swing factor.
ChemoMetec Forecasts, Earnings Path and Implied Execution Bar
ChemoMetec's narrative projects DKK 795.3 million revenue and DKK 351.1 million earnings by 2029. This assumes 15.9% yearly revenue growth and an earnings increase of about DKK 149.3 million from DKK 201.8 million today.
Uncover how ChemoMetec's fair value indicates a 12% potential downside to its current price, suggesting a premium that leaves little room for error.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community put ChemoMetec anywhere between DKK 478.31 and DKK 721.67, so retail views are already stretched before the latest guidance lift. When you factor in the heavier product development bill and automation push, you can see why opinions can diverge sharply. Explore several viewpoints before deciding how this updated story fits your portfolio.
Explore 3 other ChemoMetec fair value estimates, including one that suggests as much as 34% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ChemoMetec research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ChemoMetec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ChemoMetec's overall financial health at a glance.
Looking For More Ideas Beyond ChemoMetec?
Once you have a view on ChemoMetec, it can help to widen the lens and compare it with other opportunities that share some of the qualities you care about most. The Simply Wall St Screener lets you quickly scan different themes so you can pressure test your thesis and avoid anchoring on a single stock.
- Prefer to focus on strength and resilience first? Filter for businesses with sturdier finances using our list of solid balance sheet and fundamentals (194 results) so you can compare ChemoMetec with peers that also aim to keep balance sheets in good shape.
- Hunting for overlooked quality? Use the 572 high quality undiscovered gems to spot companies where the fundamentals and cash generation profile may not yet be fully reflected in market attention.
- Want to keep risk contained? Start with the 202 resilient stocks with low risk scores and scan for stocks that screen for lower risk scores before you decide where ChemoMetec fits on your personal risk ladder.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com