


EN
Did Raised Sales Guidance Just Shift Helios Technologies (HLIO) Investment Narrative?
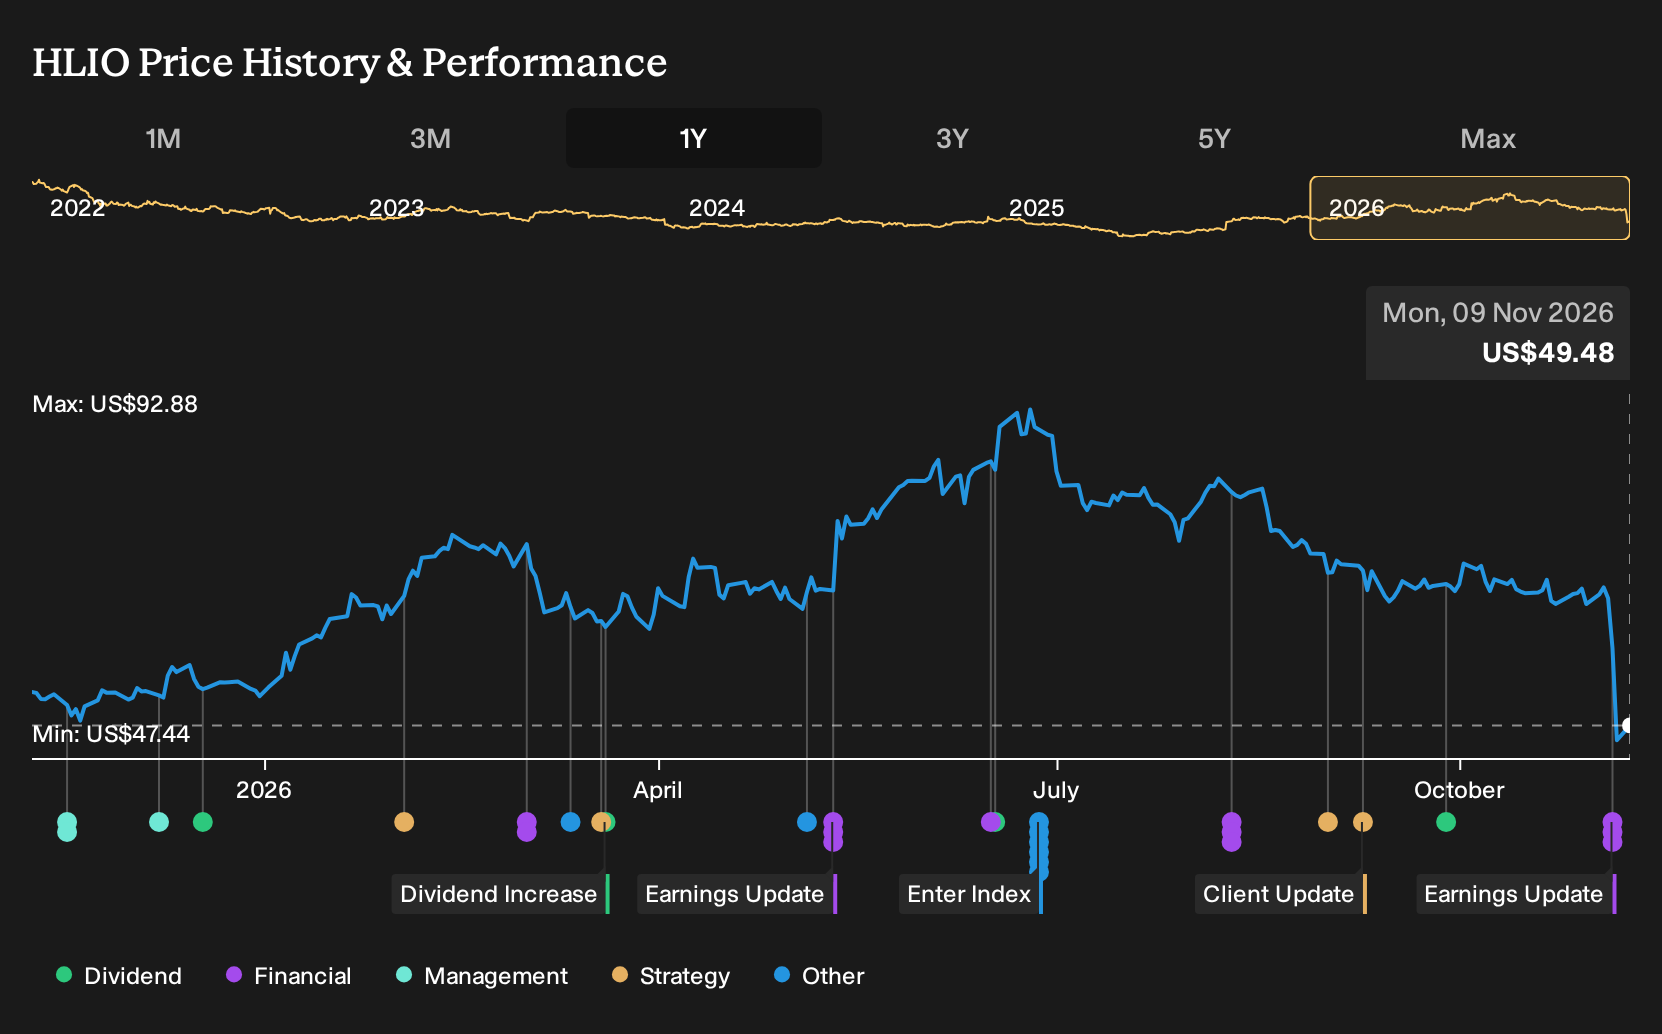
- Helios Technologies reported third quarter 2026 sales of US$229.7 million and net income of US$17.6 million, and then raised full year 2026 sales guidance to a range of US$895 million to US$902 million as of November 5, 2026.
- The combination of higher quarterly earnings and a tighter, slightly higher full year sales range suggests that management sees current demand and cost discipline as more resilient than previously signaled.
- This article examines how Helios Technologies' raised 2026 sales guidance fits into the existing investment narrative around margins and capital use.
Compare Helios Technologies' guidance lift with a curated set of industrial peers by reviewing list of solid balance sheet and fundamentals (25 results) that are also pairing earnings power with disciplined capital use.
Helios Technologies Investment Narrative Recap
To own Helios Technologies you need to believe the business can keep shifting its mix toward higher value electronics and electro hydraulics while holding margins that the analyst consensus Narrative on Simply Wall St links to recent efficiency gains. The guidance lift points to steadier demand and cost control, which supports that thesis but does not transform it.
The near term catalyst is execution on this higher sales range without giving up margin progress, especially as cyclical end markets like construction and recreational equipment remain exposed to softer demand. The biggest risk is renewed cost or macro pressure that squeezes gross margins just as the product mix transition remains in progress.
The most relevant announcement here is the raised 2026 sales outlook to US$895 million to US$902 million, alongside new fourth quarter guidance of US$205 million to US$212 million. That tighter range provides a clearer frame for testing whether Helios Technologies is converting product launches and footprint actions into consistent volume and pricing.
This update also matters because prior catalysts such as strong free cash flow, a 1.4x net debt to EBITDA ratio, and four quarters of adjusted EBITDA margin above 20% only create value if the underlying operations stay disciplined. Investors now have fresh benchmarks for how management balances growth, capex, and any future acquisitions against the risks from cyclical end markets and ongoing input cost pressure.
Helios Technologies' narrative projects US$1.0b revenue and US$112.0 million earnings by 2029. This is based on an assumed 3.8% yearly revenue growth and an earnings increase of about US$33.3 million from current earnings of US$78.7 million.
Uncover why Helios Technologies' fair value indicates a 77% potential upside to its current price and why that discount could close quickly.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between US$87.67 and US$109.35, so you are seeing tightly grouped yet still meaningfully different opinions on Helios Technologies. Those estimates do not factor in the recent guidance lift, while risks around electrification shifts and cyclical end markets keep the debate wide open.
Explore 2 other Helios Technologies fair value estimates, including one that suggests it could be worth just $87.67!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Helios Technologies research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Helios Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Helios Technologies' overall financial health at a glance.
Looking For More Helios Technologies Investment Ideas?
If Helios Technologies is on your radar, it can help to widen the lens and compare it with other companies that match different risk, quality, and income profiles using the Simply Wall St Screener.
- For investors hunting for potential mispricing, review a curated 33 high quality undervalued stocks that combine solid fundamentals with pricing that may not fully reflect them yet.
- If resilience matters more than excitement, focus on a 30 resilient stocks with low risk scores that screens for companies with stronger balance sheets and steadier risk profiles.
- For those who care about income as well as total return, scan a set of 6 dividend fortresses that offer higher yields backed by fundamental data.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com