


EN
Is Westshore Terminals Investment (TSX:WTE) Cheap After Strong Q3 2026 Earnings?
Westshore Terminals Investment (TSX:WTE) just reported third quarter 2026 earnings, with revenue of CA$106 million and net income of CA$28.99 million, drawing fresh attention to the coal terminal operator’s performance.
The earnings release has landed at a time when momentum in Westshore Terminals Investment’s shares is strong. The CA$45.96 price reflects a 1-day share price return of 6.61% and a year-to-date share price return of 76.57%, while the 1-year total shareholder return of 90.69% and 3-year total shareholder return of 130.02% point to a powerful longer-term re-rating as investors reassess both growth prospects and risk around the coal terminal operator’s cash generation.
Capitalize on the renewed attention around Westshore Terminals Investment by scanning a curated 7 high quality undiscovered gems that, like WTE, are starting to turn stronger financial results into market momentum.With Westshore Terminals Investment now at CA$45.96 after a sharp run, the real fork in the road is simple: pay up today, or wait and risk watching the valuation gap close without you.
Most Popular Narrative: 2.2% Undervalued
On the analyst consensus Narrative on Simply Wall St, Westshore Terminals Investment screens as slightly undervalued, with a fair value of CA$47 against the latest close at CA$45.96, which puts more weight on cash flows than short term share price swings.
The planned commissioning of the BHP Jansen potash project in 2027 introduces Westshore Terminals Investment to a new commodity stream that could add an additional source of terminal revenue once volumes begin to move through the facility.
The new dual commodity shiploader at Berth 2, expected to be installed in 2026, is intended to modernize loading infrastructure and may support higher long term throughput efficiency for both coal and potash. This may provide potential benefits for revenue capacity and operating margins.
See why 1 investors see Westshore Terminals Investment as 2% undervalued.
Result: Fair Value of CA$47 (UNDERVALUED)
Still, the thesis around Westshore Terminals Investment can wobble if handling rates weaken further or if the Berth 2 shiploader outage drags beyond the planned window.
Find out about the key risks to this Westshore Terminals Investment narrative.
Another Look At Westshore Terminals Investment’s Price Tag
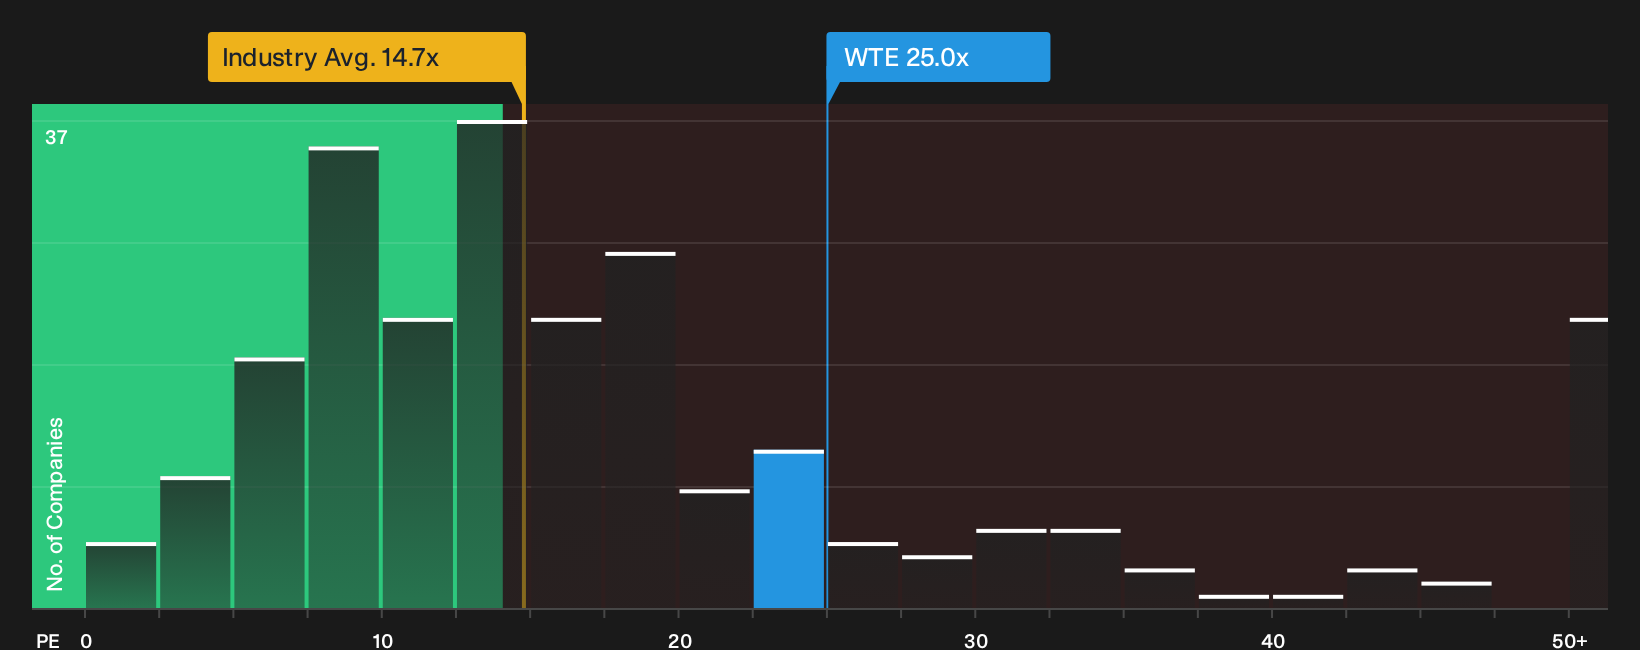
While Simply Wall St’s DCF model suggests Westshore Terminals Investment trades about 22.9% below an estimated future cash flow value of CA$59.60, earnings based signals tell a different story. A 25x P/E screens as rich against a fair ratio of 17.3x, which raises a simple question: Is this a margin of safety or a margin of risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Westshore Terminals Investment so far. To act with confidence, pressure test the numbers yourself and weigh both the downside and upside using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Westshore Terminals Investment?
Do not stop your research at one ticker. The best opportunities often sit just outside your current watchlist, waiting for investors who are willing to look a step further.
- Target resilient compounding potential by focusing on resilient stocks with lower risk profiles through the 9 resilient stocks with low risk scores.
- Hunt for value by zeroing in on companies that pair strong fundamentals with attractive pricing using the 7 high quality undiscovered gems.
- Build staying power in your portfolio by focusing on businesses with robust finances through a curated list of solid balance sheet and fundamentals (5 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com