


EN
Canadian National Railway (TSX:CNR) As Strong Q3 And Capital Returns Feed Its Valuation Case
Canadian National Railway (TSX:CNR) just delivered third quarter results with higher revenue and net income than a year ago, along with a fresh dividend affirmation and ongoing share buybacks that highlight current capital return decisions.
Canadian National Railway’s latest earnings update, dividend affirmation and CFO succession plan arrive with the share price at CA$179.45 and a 30.24% year to date share price return. The 1 year total shareholder return of 38.67% points to solid momentum rather than a short term spike.
Scan other rail and transport operators with similar earnings momentum and capital return stories by checking the hand picked 9 resilient stocks with low risk scores that combine resilient balance sheets with measured risk profiles.
Canadian National Railway now combines rising earnings, dividends and buybacks with a share price near its highs. The business looks strong. The open question is whether CA$179.45 already reflects that strength or not.
Most Popular Narrative: 5% Undervalued
Canadian National Railway’s analyst consensus Narrative on Simply Wall St places fair value at CA$189.32, which is above the latest close of CA$179.45. That view rests on specific volume, efficiency and tax assumptions being realised under a 7.8% discount rate.
The Fast Track efficiency program, which has already delivered about US$100m of realized savings in the first half of 2026, together with record fuel efficiency and better locomotive and crew productivity, creates room for Canadian National Railway to lower unit costs and support net margins and earnings power.
See why 130 investors see Canadian National Railway as 5% undervalued.
Result: Fair Value of CA$189.32 (UNDERVALUED)
Still, the narrative around Canadian National Railway can change quickly if lumber and overseas intermodal demand remain soft, or if higher capital spending fails to translate into broader free cash flow strength.
Find out about the key risks to this Canadian National Railway narrative.
Another View On Canadian National Railway
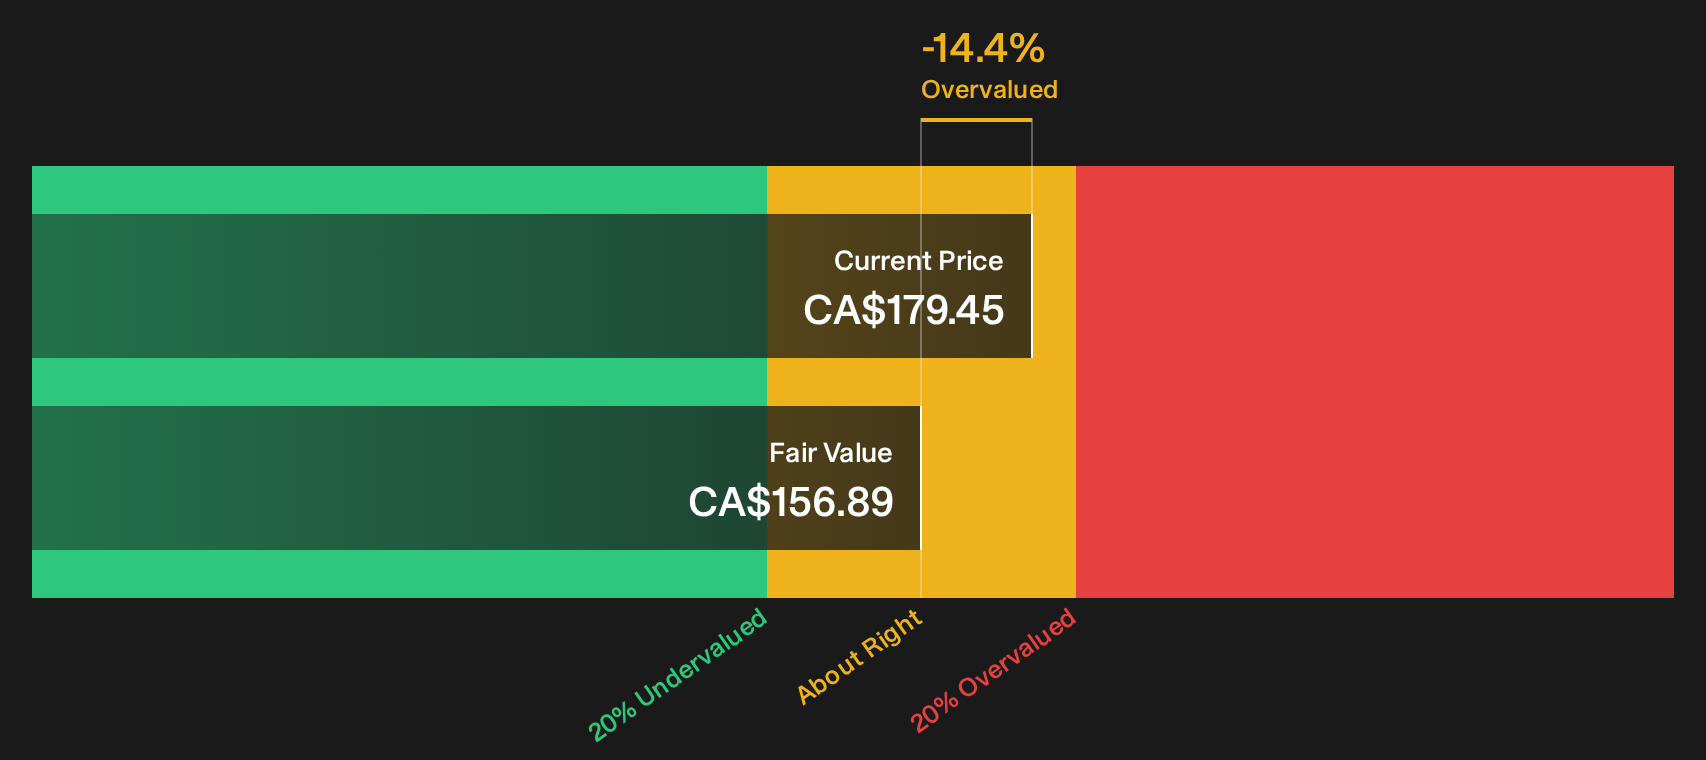
Analyst targets suggest Canadian National Railway trades below a CA$189.32 fair value, yet the Simply Wall St DCF model points to a future cash flow value of CA$156.89. One framework leans on earnings and multiples; the other on cash flows. Which lens do you trust most when money is at risk?
To understand how this cash flow based estimate is built and why it differs from the narrative fair value, take a closer look at the SWS DCF workup for Canadian National Railway, starting with the Look into how the SWS DCF model arrives at its fair value..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Canadian National Railway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed about whether Canadian National Railway looks cheap, fully priced or somewhere in between right now? Act while the facts are fresh and weigh both sides of the ledger by digging into the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Canadian National Railway?
Ready to broaden your watchlist with other potential opportunities that match your style? Use the Simply Wall Street Screener to surface focused ideas quickly and confidently.
- Target reliable income streams by scanning for companies that feature 3 dividend fortresses and may appeal if you want yield with substance behind it.
- Spot potential mispricings by reviewing a curated 6 high quality undervalued stocks that align strong fundamentals with prices that might not fully reflect them.
- Prioritise financial resilience by filtering for a list of solid balance sheet and fundamentals (5 results) so you can focus on businesses built to handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com