


EN
Higher Earnings Guidance Might Change The Case For Investing In Cheniere Energy Stock
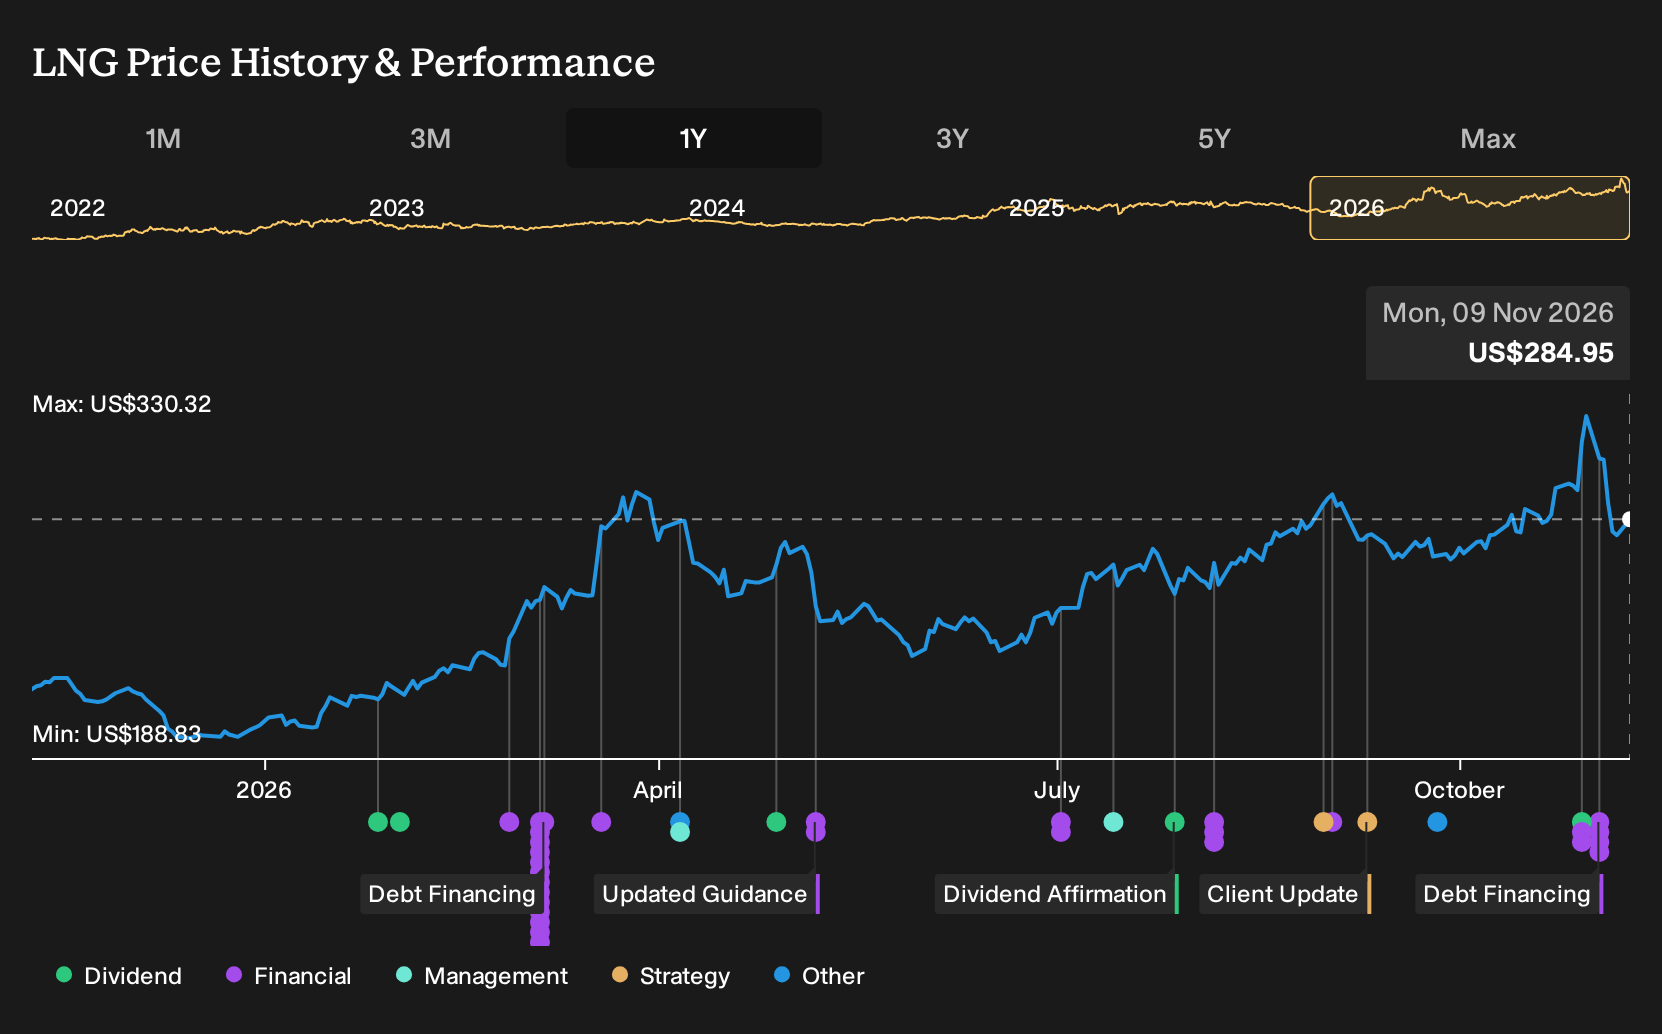
- Cheniere Energy raised full year 2026 net income guidance to a range of US$2.1b to US$2.5b, reported higher third quarter revenue and net income than a year earlier, and lifted its quarterly dividend to US$0.625 per share for the third quarter of 2026, payable on November 17.
- The combination of stronger reported earnings, a higher earnings outlook and a more than 12% dividend increase indicates that Cheniere Energy is prioritising cash returns while still funding its liquefied natural gas growth projects and balance sheet plans.
- This article examines how Cheniere Energy's investment narrative is affected by the higher 2026 earnings guidance and dividend increase.
Cheniere Energy Investment Narrative Recap
To own Cheniere Energy, you need to believe its LNG terminals, long term contracts and debottlenecking projects can keep generating substantial cash flow even as reported earnings move around. The analyst consensus Narrative on Simply Wall St leans on that contracted profile. The higher 2026 net income guidance and larger dividend speak to that cash confidence, but the core thesis still hinges on reliable LNG operations.
The biggest short term swing factor is how derivative fair value movements and any operational hiccups affect reported profit against those guidance ranges. The largest live risk remains regulatory and legal scrutiny around the US$370m tax credit investigation plus Cheniere Energy’s high debt load. The latest news does not remove either issue.
The fresh US$1.2b Senior Notes due 2037, with a 5.8% coupon, appear most relevant here because they plug directly into Cheniere Energy’s balance sheet and funding of LNG projects. Management has flagged broad uses that include refinancing nearer term bonds, capital spending and working capital. All of these link back to execution on Corpus Christi and Sabine Pass plans.
For you as a shareholder, the key question is how this extra borrowing interacts with cash returns and risk. Refinancing older 5.125% secured notes due 2027 would extend maturities but at a higher coupon. This keeps the focus on maintaining strong contracted volumes and disciplined costs. That funding mix remains central to whether guidance, dividend ambitions and the analyst catalysts can hold together.
Cheniere Energy's narrative projects US$25.0b revenue and US$3.1b earnings by 2029. This implies 3.3% yearly revenue growth and an earnings increase of about US$0.1b from US$3.0b today.
Uncover why Cheniere Energy's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community cluster between about US$319 and US$414 per share, so some retail analysts see Cheniere Energy as materially mispriced in both directions. When you combine that with the recent 5.8% 2037 Senior Notes and the tax credit investigation, you get sharply different narratives that are worth comparing.
Explore 3 other Cheniere Energy fair value estimates, including one that suggests it could be worth just $318.71.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Cheniere Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cheniere Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Cheniere Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cheniere Energy?
Cheniere Energy may sit at the center of your thesis today, but you can widen your opportunity set quickly by using the Simply Wall St Screener to filter for other businesses that fit your approach to risk, income and balance sheet strength.
- If you want income that can potentially withstand tougher conditions, you can look at stocks that combine higher yields with sturdy fundamentals through our screener of 6 dividend fortresses.
- For investors who care most about financial resilience and staying power, you can narrow the field to companies with robust finances using the list of solid balance sheet and fundamentals (25 results).
- If you are hunting for underfollowed opportunities rather than well covered large caps, the screener of 19 high quality undiscovered gems can surface ideas that many portfolios may not hold yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com