


EN
Should Breakup Plan Require Action From National Fuel Gas Stock Investors?
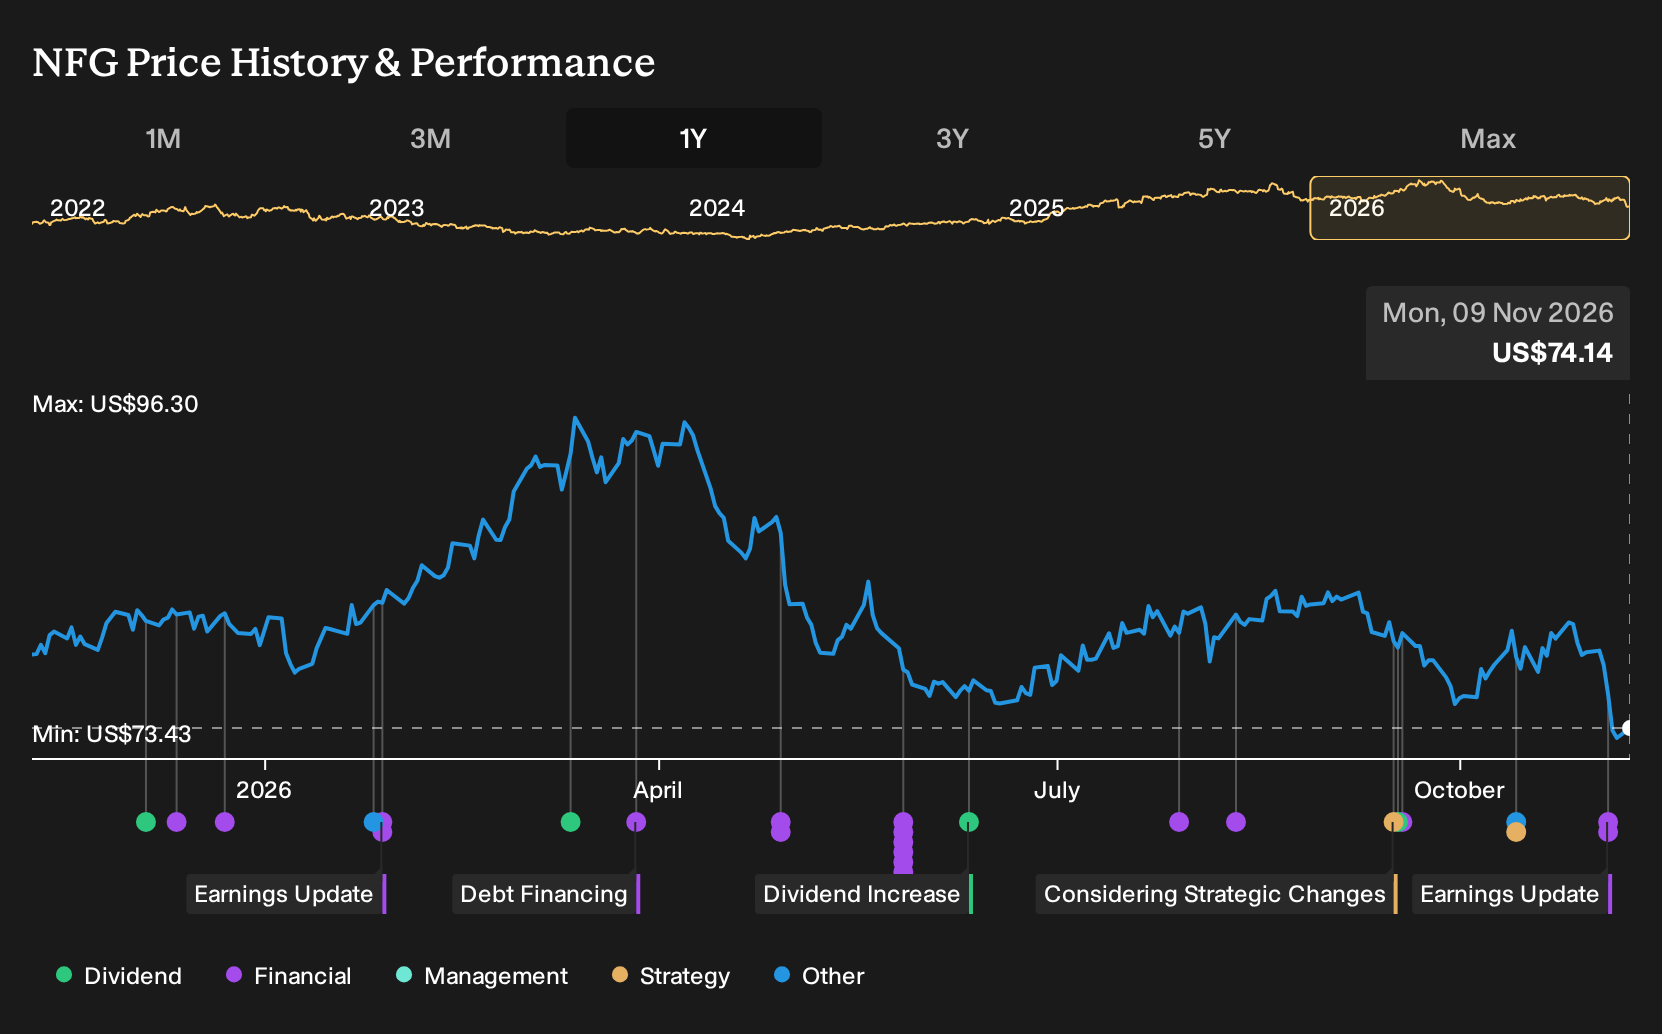
- National Fuel Gas reported fourth quarter 2026 revenue of US$467.85 million and net income of US$97.51 million, and issued fiscal 2027 Integrated Upstream and Gathering production guidance of 400 to 435 Bcf that reflects price related marketing curtailments in October.
- The company paired higher full year 2026 earnings, including diluted EPS from continuing operations of US$7.02, with plans to separate into two publicly traded entities, while signalling softer fiscal 2027 performance tied to lower natural gas pricing and flat production.
- We will now look at how National Fuel Gas's planned business separation and softer 2027 outlook could reshape its investment narrative.
Compare how National Fuel Gas stacks up against peers facing the same commodity headwinds by scanning our hand picked 33 high quality undervalued stocks for potential alternatives.
National Fuel Gas Investment Narrative Recap
To own National Fuel Gas, you need to be comfortable with a story built on regulated pipelines and utilities, paired with more cyclical upstream exposure. The latest update points to softer fiscal 2027 earnings as natural gas prices ease and Integrated Upstream and Gathering production flattens, with 400 to 435 Bcf guidance already assuming some price related curtailments.
The key near term swing factor is execution through that weaker commodity patch while keeping pipeline projects and the pending separation on track. The biggest risk is that upstream under delivery or further curtailments squeeze earnings more than expected, which could matter given existing debt levels and dividends not being fully covered by free cash flow.
The most relevant update for this catalyst discussion is fiscal 2027 production guidance from the Integrated Upstream and Gathering segment. Management is signalling 400 to 435 Bcf, already trimmed for October price related marketing curtailments. That frames a year where volumes are not doing much of the heavy lifting for earnings.
Against that backdrop, the analyst consensus Narrative on Simply Wall St leans heavily on regulated pipelines, storage and utilities, plus the Ohio gas utility acquisition, to carry more of the load. Your focus now is on whether National Fuel Gas can deliver those expansion and integration projects cleanly while riding through a year where upstream margins and output look more constrained.
National Fuel Gas' current earnings are quoted at US$675.3 million, with analyst consensus pointing to US$773.4 million of earnings on US$3.2b of revenue by 2029. This implies forecast annual revenue growth of 8.8% and an earnings increase of about US$98 million by that year.
Uncover why National Fuel Gas' fair value indicates a 25% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$93 and about US$120, with one end implying heavier undervaluation than the other. That spread sits alongside risks such as decarbonization policy shifts and Ohio acquisition integration, so you are seeing sharply different views on how National Fuel Gas might perform.
Explore 2 other National Fuel Gas fair value estimates, including one that suggests potential upside of up to 62% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your National Fuel Gas research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for National Fuel Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Fuel Gas' overall financial health at a glance.
Looking For More Investment Ideas Beyond National Fuel Gas?
If National Fuel Gas has sharpened your thinking about risk, income and growth trade offs, it can help to compare it with a wider mix of companies that share some of the qualities you care about most.
- For investors who want income that might hold up through different market conditions, consider screening for dividend payers described as 6 dividend fortresses.
- If capital preservation and steadier business profiles matter most to you right now, filter for companies in the 30 resilient stocks with low risk scores and see which ones fit your comfort level.
- When you are hunting for quality beyond the usual watchlists, broaden your search with the 19 high quality undiscovered gems that pair fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com