


EN
How Investors Are Reacting To Williams (WMB) Strong Quarterly Earnings
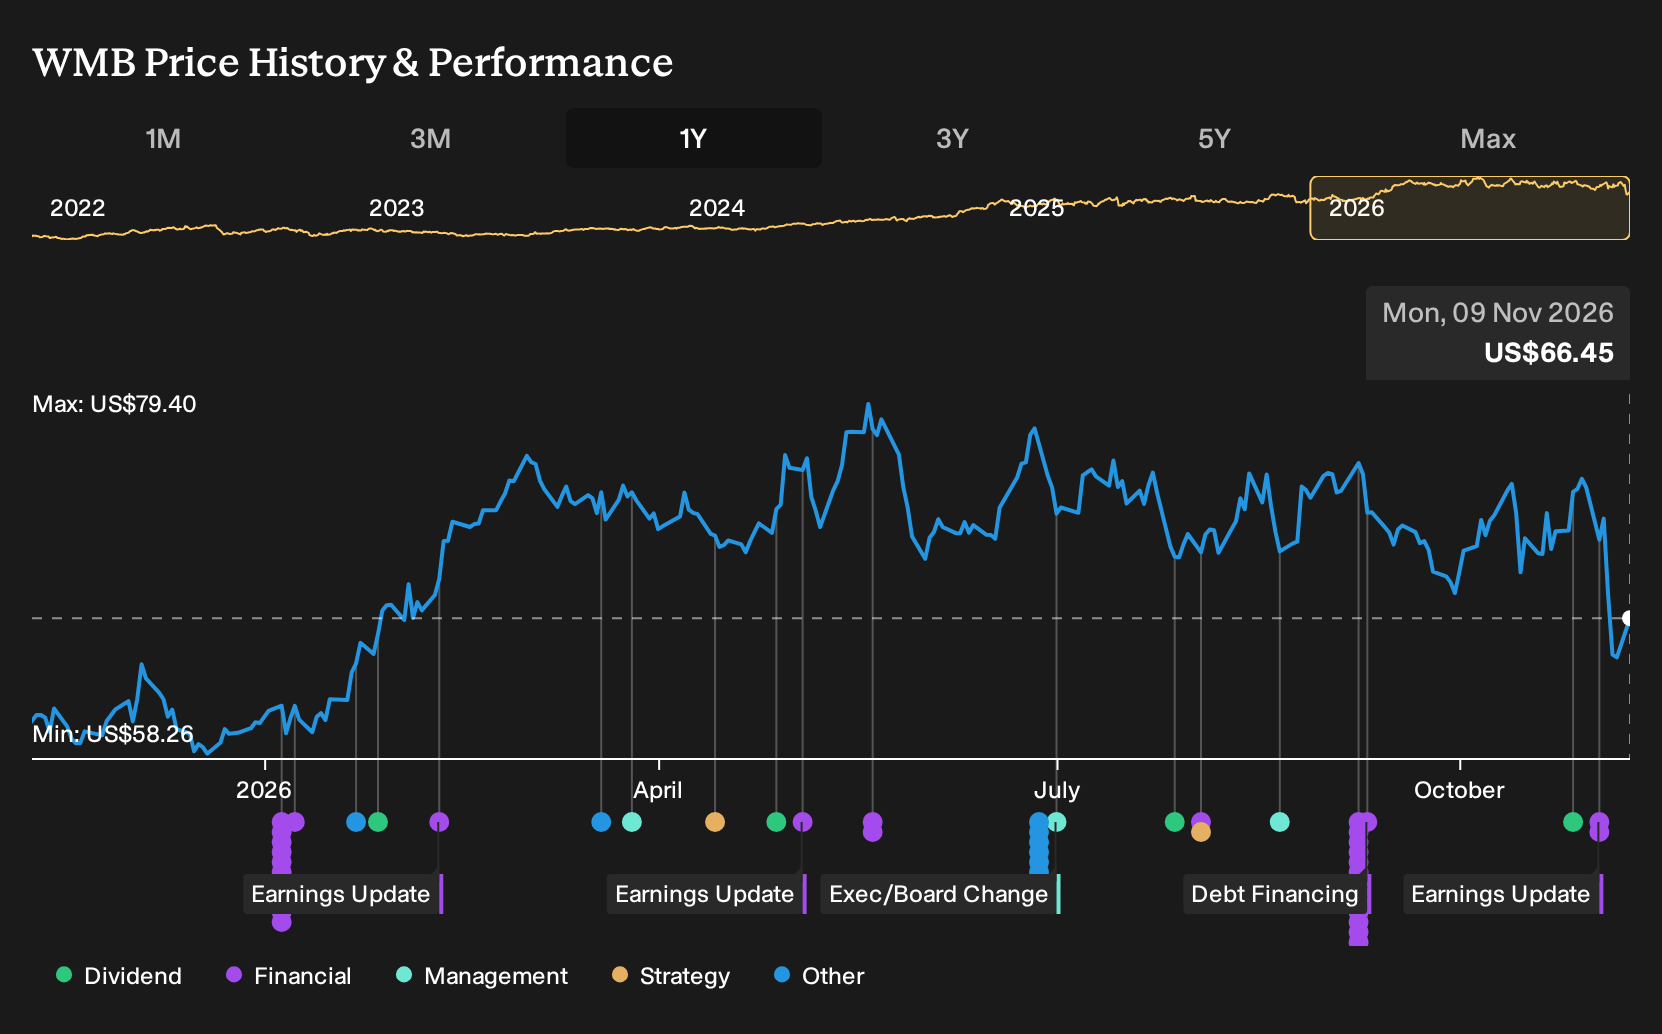
- Williams Companies reported third quarter 2026 results with revenue of US$3,223 million and net income of US$700 million, alongside a regular quarterly dividend of US$0.525 per share approved for payment on December 28, 2026.
- The universal shelf registration covering debt, preferred and common equity, warrants, units and purchase contracts gives Williams Companies additional flexibility to fund projects or manage its balance sheet in line with its existing gas infrastructure footprint.
- Next, the focus will be on how this higher quarterly net income shapes Williams Companies' broader investment narrative around gas infrastructure.
Scan Williams Companies alongside a curated 6 dividend fortresses that, like WMB, pairs regular cash payouts with substantial infrastructure footprints and sizable capital needs.
Williams Companies Investment Narrative Recap
To own Williams Companies, you need to be comfortable with a large, capital intensive gas infrastructure operator that leans on long term volume contracts and steady throughput rather than big price swings. The analyst consensus narrative on Simply Wall St focuses on continued execution of projects in places like Haynesville and the Gulf Coast. The latest quarter shows revenue of US$3,223 million and net income of US$700 million, which supports that thesis without significantly changing it.
The short term swing factor still sits with project execution and keeping leverage in check while capex runs high. Debt not being well covered by operating cash flow and a dividend that is not well covered by free cash flows remain the key pressure points. Recent results and the dividend affirmation appear incremental rather than thesis changing for Williams Companies.
The most interesting update linked to that thesis is the universal shelf registration. It gives Williams Companies pre cleared room to issue debt, preferred stock, common equity, warrants, units or purchase contracts as funding needs emerge across projects such as Shelby Connector, Delta Access or the Power Innovation platform.
For you as a shareholder, that flexibility can cut both ways. It can support build out of Neo and other long duration contracts that the analyst consensus narrative on Simply Wall St highlights as potential earnings drivers. It can also mean more leverage or equity issuance if internal cash generation and existing borrowing capacity do not fully cover Williams Companies growth plans.
Williams Companies' narrative projects US$17.2b revenue and US$4.4b earnings by 2029. This assumes 11.9% yearly revenue growth and an earnings increase of about US$1.3b from US$3.1b today.
Discover why Williams Companies' fair value points to a 29% potential upside from its current price, which could diminish rapidly.
Exploring Other Perspectives
One alternate view around Williams Companies emphasizes the risk that big data center and AI related power demand disappoints. The most cautious analysts were only penciling in about US$16.7b of revenue and US$3.6b in earnings by 2029. That is a materially lower path and shows how far opinions can stretch. These forecasts all came before the latest earnings and shelf registration, so you may want to compare several narratives and decide which assumptions you find more realistic.
Explore 4 other Williams Companies fair value estimates, including one that suggests it could be worth just $73.34.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Williams Companies research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Williams Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Williams Companies' overall financial health at a glance.
Looking for more Williams Companies style ideas?
If you want to put Williams Companies in context, the next step is to compare it with other stocks that match your own preference for income, resilience or upside potential. The Simply Wall St Screener can help you quickly narrow the field so you spend time weighing the trade offs, not just hunting for tickers.
- If capital preservation is a priority, start with sturdier balance sheets and a simple filter built around a 30 resilient stocks with low risk scores can help surface candidates that may better match your risk tolerance.
- If you are hunting for quality at a reasonable entry point, aim your search at companies trading on more modest valuations and scan through a focused 33 high quality undervalued stocks to see which ones line up with your checklist.
- If you want to go off the beaten track, concentrate on lesser known opportunities with stronger fundamentals and see what turns up in a targeted 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com