


EN
Did Earnings And Buyback Plan Just Shift Ameriprise Financial's (AMP) Investment Narrative?
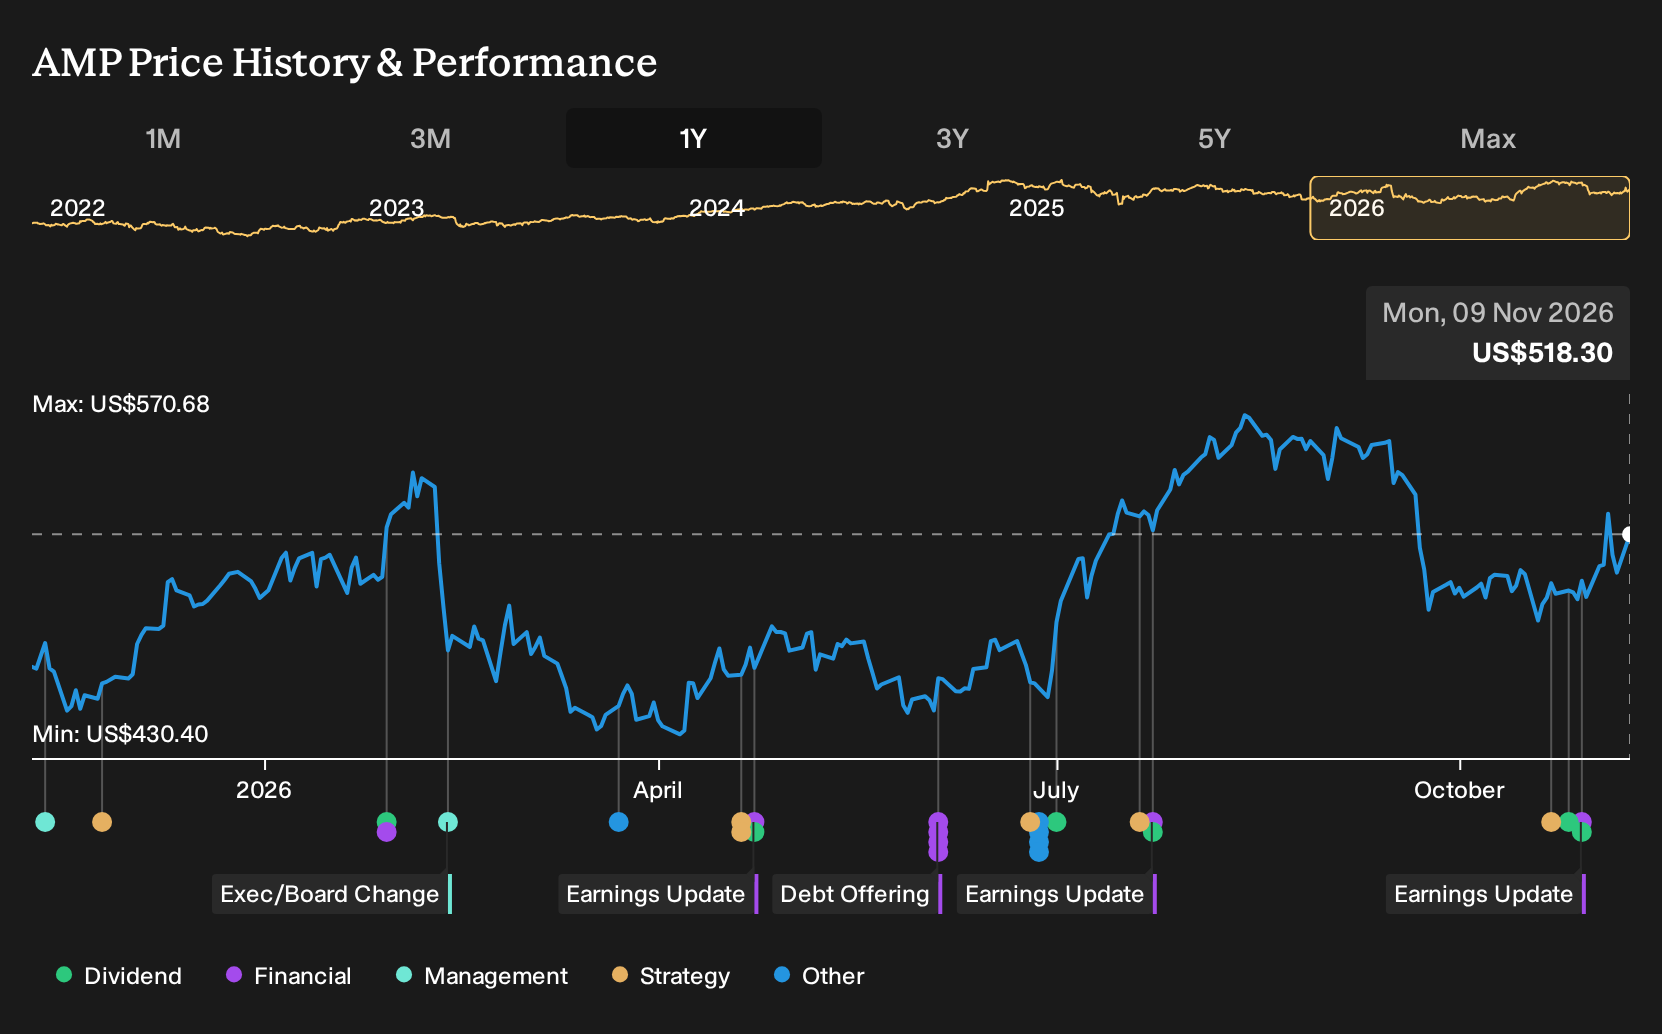
- Ameriprise Financial reported third quarter 2026 revenue of US$5,191 million, net income of US$1,126 million and diluted EPS from continuing operations of US$12.32, while also outlining past share repurchases of 8,677,426 shares for about US$4.32b through September 30, 2026.
- The company paired these earnings with a fresh US$5.5b share repurchase authorization running through September 30, 2028, which reflects a continued emphasis on capital return alongside its fee based advice, asset management and insurance focused business model.
- This raises the question of how Ameriprise Financial's new US$5.5b buyback program could influence the existing investment narrative around capital return.
Scan how Ameriprise Financial's capital return story compares with other companies actively using buybacks in our curated list of 19 high quality undiscovered gems.
Ameriprise Financial Investment Narrative Recap
To own Ameriprise Financial, you need to be comfortable with a fee based wealth and asset management model that leans heavily on adviser productivity, net client flows and disciplined cost control. The analyst consensus narrative on Simply Wall St leans on those factors, plus a tilt toward advisory earnings and a growing bank book. The recent quarter showed higher revenue, net income and EPS, so the near term earnings story remains tied to whether adviser retention and client flows hold up against tough recruiting conditions.
The biggest swing factor in the short run is how Advice & Wealth Management and Asset Management handle prior outflows and institutional redemptions. Those issues do not vanish with one strong quarter, so the key operational risk is that weaker flows or further adviser departures keep pressuring assets under management and related fees. If flows stabilize or improve as Huntington Bank advisers and assets are onboarded, that could support the existing earnings narrative rather than redefine it.
The new US$5.5b repurchase authorization through September 30, 2028, following US$4.32b of completed buybacks, is the announcement that matters most for this story. It aligns with management’s history of returning a high share of operating earnings to investors and with analysts expecting the share count to decline over time. For someone following Ameriprise Financial, this keeps capital return firmly in focus without changing the core reliance on fee based advice and asset management profits.
Operationally, this fresh buyback capacity adds another lever alongside AI enabled adviser tools, the expanding bank book and Huntington Bank onboarding. The analyst consensus narrative on Simply Wall St views these factors as key supports for margins and earnings. The main execution risk is that if Advice & Wealth Management flows or Asset Management outflows soften earnings more than expected, there is less flexibility to use repurchases at the same pace while also funding technology, distribution and regulatory needs.
Ameriprise Financial's narrative projects US$22.6b revenue and US$4.8b earnings by 2029. This implies forecast revenue growth of 4.5% per year and an earnings increase of about US$0.9b from current earnings of US$3.9b.
Uncover why Ameriprise Financial's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Ameriprise Financial story around adviser and bank partner growth, not just buybacks. Before this earnings and US$5.5b repurchase news, they were penciling in around US$23.2b of revenue and US$5.0b of earnings by 2029. You can compare that more upbeat path with other viewpoints and decide which story fits your own expectations.
Explore 2 other Ameriprise Financial fair value estimates, including one that suggests there may be as much as 93% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ameriprise Financial research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Ameriprise Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ameriprise Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ameriprise Financial?
Once you have a view on Ameriprise Financial, it often helps to line it up against other opportunities using the Simply Wall St Screener. A few focused stock shortlists can quickly show you how different business models, balance sheets and income profiles compare side by side.
- If you want income to play a bigger role in your portfolio, check out a set of potential high yield payers screened as 6 dividend fortresses.
- If capital preservation sits high on your list, consider companies filtered for resilient fundamentals through a 30 resilient stocks with low risk scores.
- If you are hunting for quality at a price that still looks reasonable, review a curated pool of potential value ideas in our 33 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com