


EN
OPENLANE (OPLN) Could Be 24% Below Fair Value On Raised 2026 Guidance
OPENLANE (OPLN) has drawn fresh attention after updating full year 2026 earnings guidance and releasing third quarter results that showed higher revenue and earnings per share compared with the prior year period.
Over the past week the OPENLANE share price has pulled back, with a 7 day share price return of down 11.87% and a 30 day return of down 4.93%, even though the stock still shows a year to date share price gain of 19.48% and a 1 year total shareholder return of 40.10%. This suggests longer term momentum has been stronger than the latest reaction to raised 2026 guidance and the third quarter update.
Spot opportunities like OPENLANE by scanning our hand picked 33 high quality undervalued stocks that combine cash generation with balance sheet strength.OPENLANE is posting higher earnings guidance and stronger recent revenue, yet the share price has slipped in the short term. Does that mix leave the stock attractively priced, or already full for what you are getting?
Most Popular Narrative: 24% Undervalued
On the analyst consensus Narrative on Simply Wall St, OPENLANE is framed as undervalued, with a fair value of $46.22 against a last close of $34.90. The argument leans heavily on digital scale and cash generation rather than short term earnings noise. That view also rests on a structured model that discounts future cash flows back at a 7.68% rate and ties them to explicit revenue and margin forecasts.
The accelerating move by dealers from physical auctions to OPENLANE’s digital marketplace, highlighted by roughly 31% growth in U.S. dealer to dealer volumes while physical dealer auctions were slightly negative, points to further mix shift toward higher volume digital transactions that can support revenue and adjusted EBITDA.
See why 1 investors see OPENLANE as 24% undervalued.
Result: Fair Value of $46.22 (UNDERVALUED)
Still, the OPENLANE story can break if competition squeezes auction pricing, or if high net debt and rising costs cap the benefit of digital scale.
Find out about the key risks to this OPENLANE narrative.
Another View: What OPENLANE’s Sales Multiple Is Saying
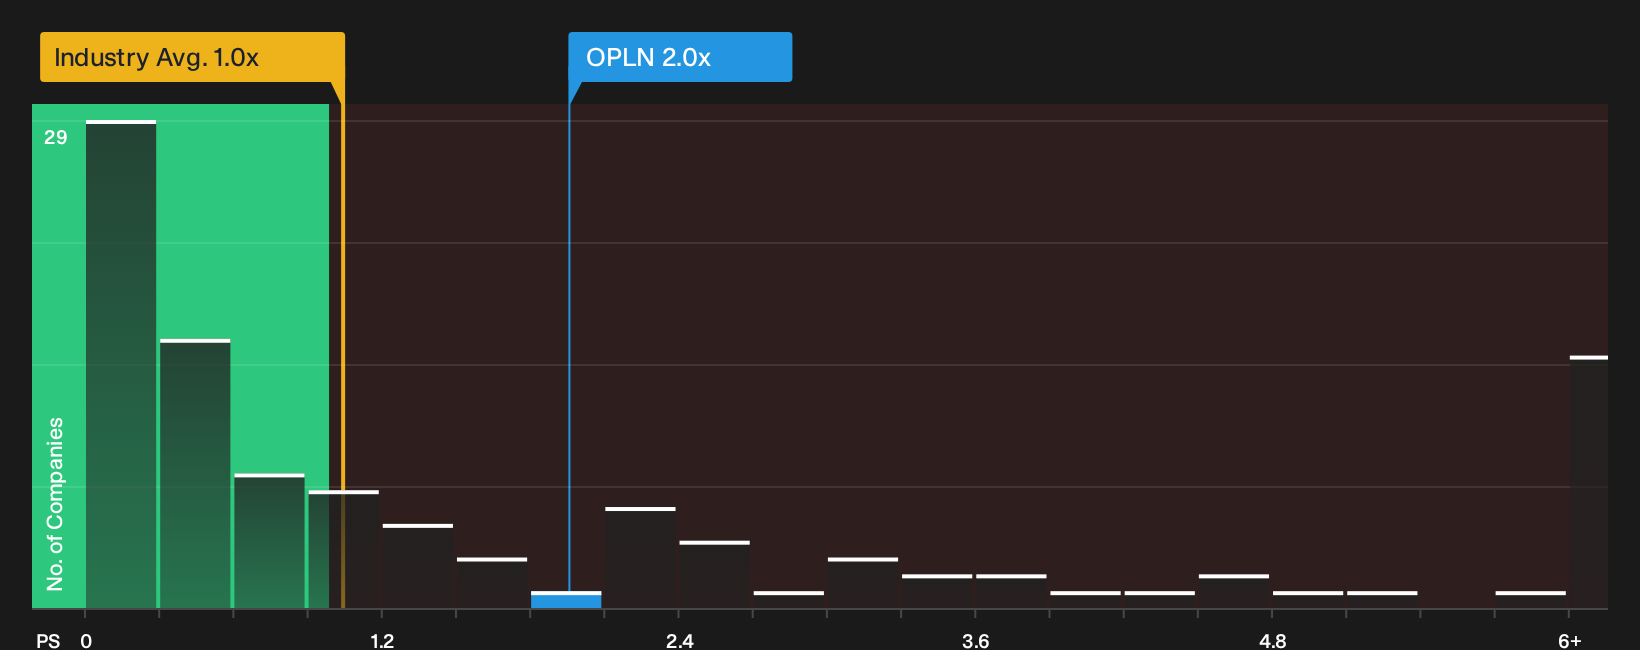
The DCF narrative presents OPENLANE as cheap, yet a simple P/S check tells a tighter story. The stock trades around 2x sales, compared with 1x for the US Commercial Services group and a fair ratio of 1.9x. That gap is small relative to the fair ratio but wide relative to peers, which raises the question of how much mispricing is really on the table.
For a closer look at how that sales multiple compares with peers and where the fair ratio might pull it over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like this around OPENLANE tend to split opinion, so treat this as a prompt to review the numbers directly and test the story for yourself, then weigh the upside and downside risks through the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond OPENLANE?
You have seen how OPENLANE stacks up, so now is the time to widen your watchlist and line up a few fresh contenders.
- Target potential bargains by scanning a curated pool of cash generative opportunities through the 33 high quality undervalued stocks.
- Strengthen your downside protection by focusing on companies with sturdy finances using the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by searching for lesser known prospects with strong underlying metrics via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com