


EN
How Investors Are Reacting To Capital Power Stock (TSX:CPX) Weaker Earnings Results
- Capital Power reported third quarter 2026 results with sales of C$806 million and net income of C$67 million, alongside full year to date net income of C$38 million.
- The gap between higher year to date sales of C$2,698 million and much lower net income of C$38 million highlights pressure on profitability relative to the prior year.
- We will now look at how Capital Power's weaker year to date net income influences the longer term investment narrative around contracted growth.
Capital Power Investment Narrative Recap
To stay invested in Capital Power, you need to be comfortable with a contracted growth story that currently sits beside thinner profitability. The analyst consensus narrative on Simply Wall St points to embedded EBITDA potential and long term data centre agreements as key drivers, yet the sharp gap between year to date sales and net income keeps execution on cash generation front and centre.
Right now, the main short term catalyst is whether management can convert existing assets and recontracting opportunities into cleaner earnings, despite heavier sustaining capex, financing costs and taxes. The biggest risk is that ongoing maintenance outages and weaker margins linger, which would leave free cash flow and dividend cover under more pressure.
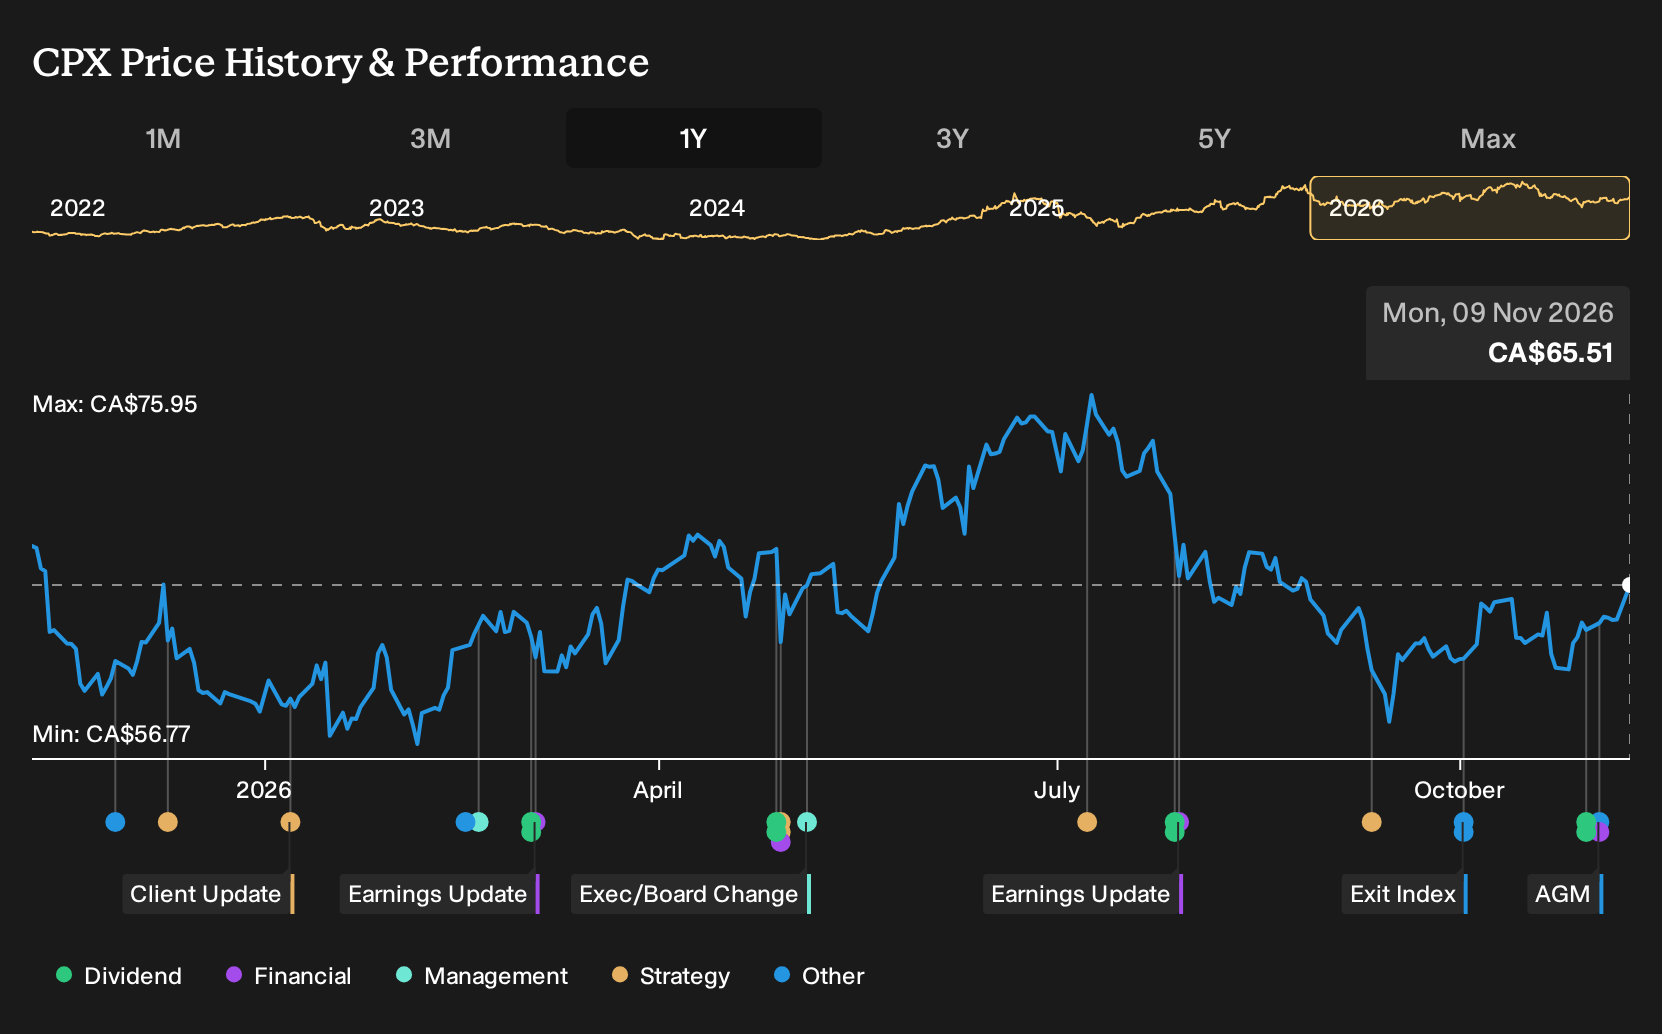
The recent decision to declare a C$0.7048 common dividend for the December quarter is the clearest operational signal linked to these results. With nine month net income at C$38 million and profit margins sitting well below last year, that payout keeps the question of dividend sustainability very live for income focused holders.
For investors tracking catalysts, the dividend affirmation ties directly into the guardrails around a 30% to 50% AFFO payout ratio that analysts highlight. If free cash generation catches up with those commitments, it may support the contracted growth narrative. If earnings and cash flow coverage stay tight, the dividend itself becomes a key risk rather than a comfort.
Capital Power Earnings Path Versus Current Profitability Strain
Capital Power's narrative projects C$4.7b revenue and C$581.6 million earnings by 2029, based on analyst estimates. This is built on 4.6% yearly revenue growth and an earnings increase of about C$471.6 million from current earnings of C$110.0 million.
Discover why Capital Power's fair value suggests an 18% potential upside to its current price that could materialize sooner than income investors expect.
Exploring Other Perspectives
Capital Power attracts only 2 fair value estimates from the Simply Wall St Community, yet they span a wide band from C$77.46 to C$200.16 per share. That kind of spread shows how far opinions can diverge, especially before the latest earnings and dividend declarations. Consider exploring several viewpoints before forming your own stance.
Explore another Capital Power fair value estimate, including one that suggests it could be worth just CA$77.46.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Capital Power research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Capital Power. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capital Power's overall financial health at a glance.
Looking for more Capital Power investment ideas?
If the Capital Power story has you rethinking portfolio balance, it can help to scan a wider field of income and quality plays that share some of the same themes but sit at different points on the risk and balance sheet spectrum.
- For readers who want income but do not want to rely on a single utility, broaden your watchlist with 3 dividend fortresses that couple yield with more robust fundamentals.
- If capital preservation is front of mind, shift attention to 9 resilient stocks with low risk scores that score well on resilience so you can compare Capital Power with companies that have steadier risk profiles.
- Those hunting for fresher opportunities can scan 7 high quality undiscovered gems where underlying quality and fundamentals may not yet be widely appreciated.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com