


EN
How Lowered Revenue Guidance Will Impact Cummins Stock
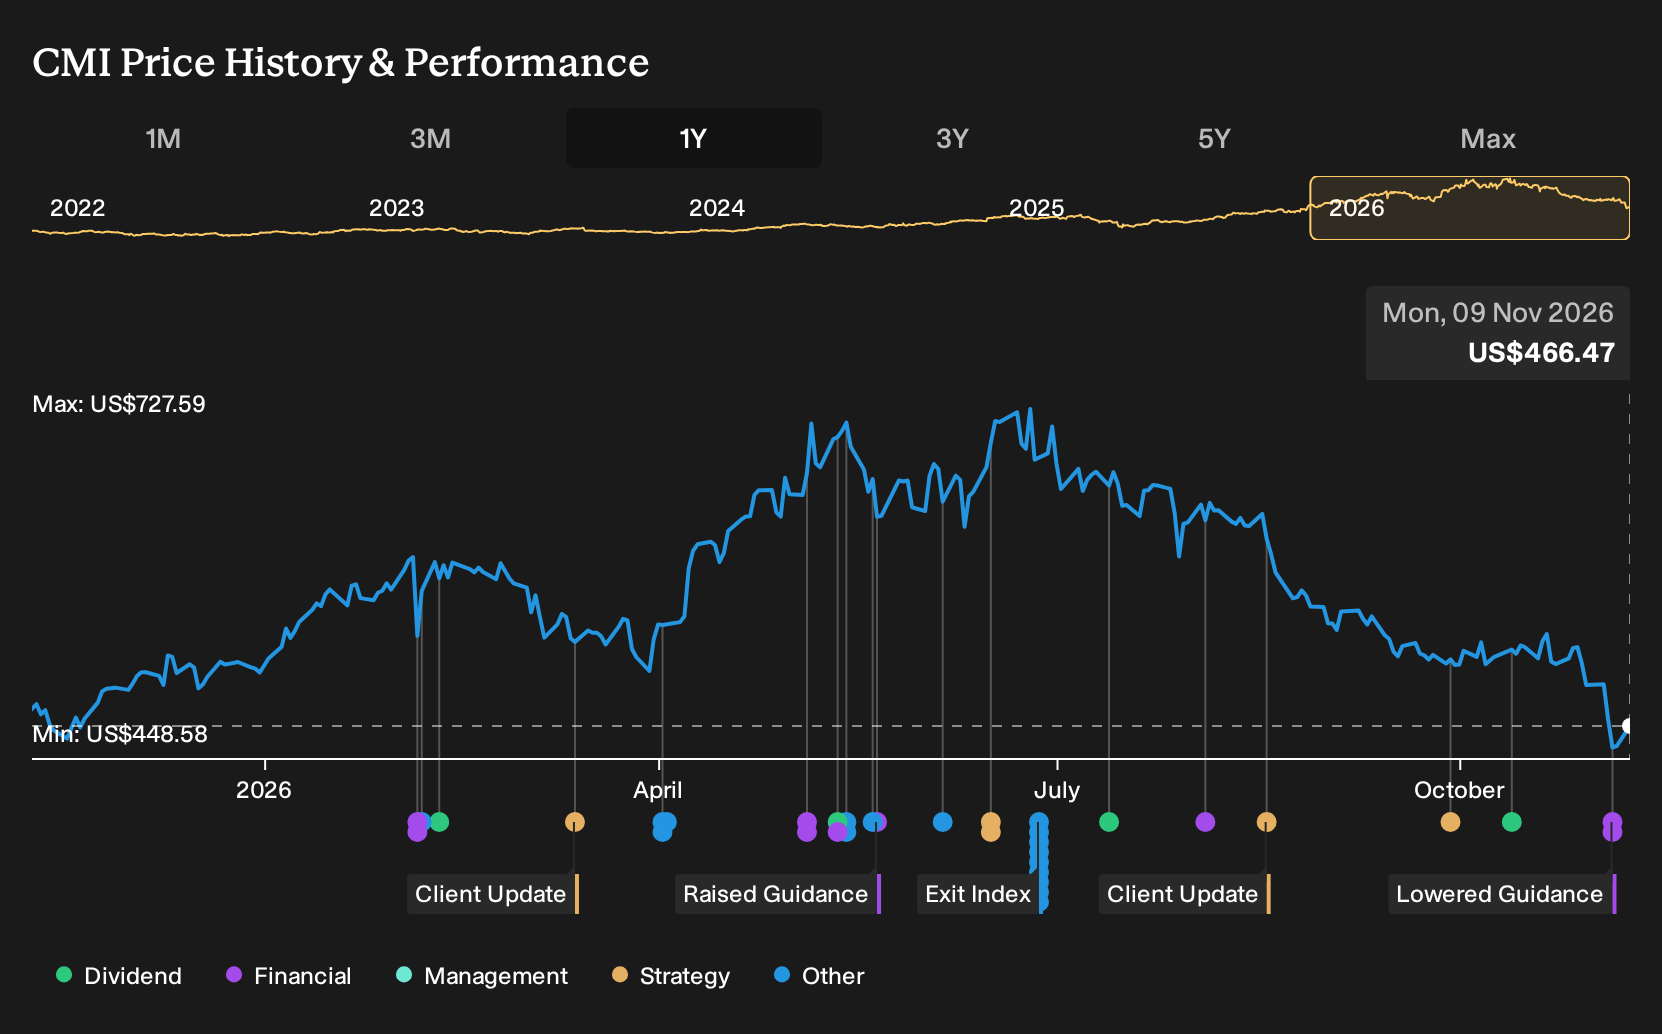
- Cummins reported third quarter 2026 sales of US$9,438 million and net income of US$1,140 million, then reduced full year 2026 revenue growth guidance to approximately 10% from a prior range of 10% to 13%.
- The results highlighted softer North American pickup engine demand and supply chain constraints, while data center power solutions and heavy duty truck engines provided important support to Cummins' overall performance.
- This raises the question of how Cummins' investment narrative holds up when full year revenue guidance tightens to about 10% growth.
Cummins Investment Narrative Recap
To own Cummins, you need to be comfortable with an engine and power solutions business that is leaning on data center demand and upcoming emissions driven engine refreshes while absorbing volatility in trucks and newer technologies. The lowered 2026 revenue growth guidance to about 10% narrows the near term range but does not fundamentally change that mix of drivers.
The short term swing factor is whether data center power systems and heavy duty engines can offset softer North American pickup demand and supply chain friction. The biggest risk is margin pressure if costs, tariffs and Accelera losses stay sticky while pricing or mix does not move in Cummins’ favor.
The clearest data point to anchor this around is the third quarter 2026 earnings release. Cummins reported US$9,438 million of quarterly sales and US$1,140 million of net income, with nine month sales of US$27,293 million and net income of US$2,726 million. Those figures set the starting line for how management now frames its approximately 10% full year revenue growth outlook.
That report also highlighted where the operational tension sits. Supply constraints and weaker North American pickup engines are pulling in one direction, while data center power solutions and heavy duty truck demand support the other. The analyst consensus Narrative on Simply Wall St leans on multi year data center orders and capacity expansion as core catalysts, and this quarter’s mix of results provides a current test of how resilient that thesis appears in practice.
Cummins' narrative projects US$47.3b revenue and US$5.9b earnings by 2029. This rests on analysts using 9.7% yearly revenue growth and an earnings increase of about US$2.6b from US$3.3b today.
Uncover why Cummins' fair value indicates a 42% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view treats Cummins’ data center exposure as a risk rather than a cushion. Those more cautious analysts were only baking in about US$41.9b of 2029 revenue and US$5.2b of earnings, so they already saw slower growth. With guidance now tightened, that camp may adjust again. This is why you should compare several narratives before deciding what this reset means for you.
Explore 3 other Cummins fair value estimates, including one that suggests it could be worth just $662.35!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cummins research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Cummins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Cummins' overall financial health at a glance.
Looking for more investment ideas beyond Cummins?
Once you have a view on Cummins, it can help to line that up against other opportunities with different risk and income profiles. The Simply Wall St Screener lets you quickly filter for themes that match how you like to invest, instead of scrolling through tickers one by one.
- If you want potential mispricing with stronger fundamentals, start with a focused set of 33 high quality undervalued stocks that combine quality metrics with a discounted entry point.
- If capital preservation and steadier profiles matter more to you, filter for 30 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- If income is your priority, use the screener to surface 6 dividend fortresses that pair higher yields with more robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com