


EN
Is ArcelorMittal (ENXTAM:MT) Undervalued On Q3 Results Despite Its Net Loss?
ArcelorMittal (ENXTAM:MT) has come under fresh scrutiny after third quarter results showed higher sales and iron ore output, yet a net loss for the period and sharply lower earnings over the first nine months.
At a share price of €56.84, ArcelorMittal has seen a strong year to date, with a 42.6% share price return and a 69.62% total shareholder return over the past 12 months. However, momentum has faded, with a 90 day share price decline of 11.44% following recent earnings headlines.
Pressure test ArcelorMittal against peers by scanning a curated list of solid balance sheet and fundamentals (194 results) that could handle heavy investment cycles and earnings swings like those just seen in its latest quarter.
The share price surge in ArcelorMittal followed by a recent pullback leaves investors with a practical choice: lean into the weakness now or wait for a clearer valuation cushion to emerge as the numbers are unpacked next.
Most Popular Narrative: 18% Undervalued
ArcelorMittal's last close at €56.84 sits below the analyst consensus Narrative fair value of €69.59, which frames the current pullback as a discount to their cash flow and earnings assumptions in the analyst consensus Narrative on Simply Wall St.
Major expansion in India, where ArcelorMittal plans to lift AMNS India capacity to over 40mtpa through the Hazira upgrade and a greenfield plant in Andhra Pradesh, along with further downstream growth in Brazil, is described as being aimed at capturing structurally rising steel consumption and is reported as having the potential to lift shipped volumes, revenue and normalized profitability.
See why 26 investors see ArcelorMittal as 18% undervalued.
Result: Fair Value of €69.59 (UNDERVALUED)
Still, the bullish ArcelorMittal story can be knocked off course if disruptions in Ukraine drag on or environmental disputes in Liberia trigger fresh penalties and project delays.
Find out about the key risks to this ArcelorMittal narrative.
Another View on ArcelorMittal’s Valuation
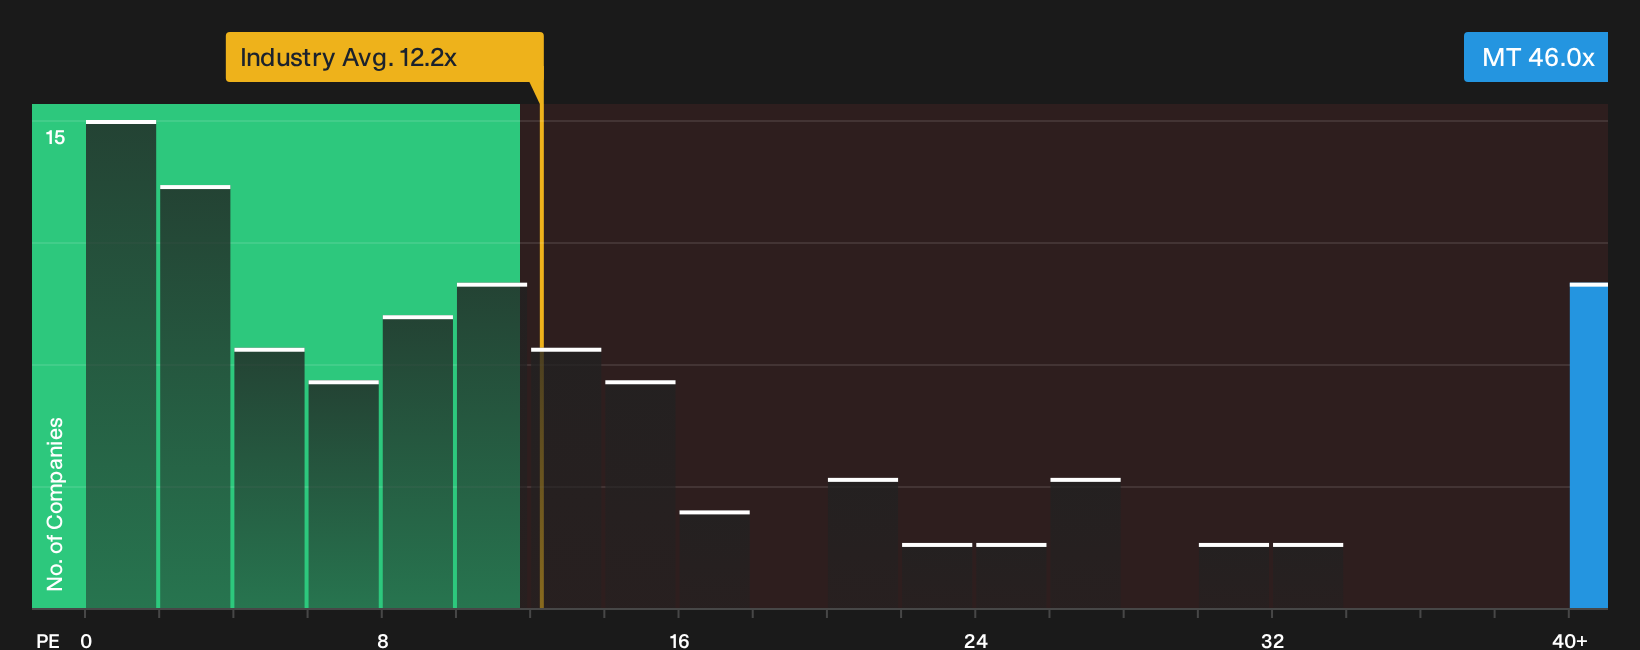
The earlier narrative leans on future earnings and cash flow to argue that ArcelorMittal looks undervalued. On plain P/E though, the picture is less straightforward. The stock trades at 46x earnings, above its 40.6x fair ratio and well above the European Metals and Mining average of 12.2x, although below a 59.7x peer group level, which leaves investors asking whether they are paying up for quality or just paying up.
To unpack where that gap could close from, either through price or earnings, it is worth digging into the full valuation breakdown and how the fair ratio has been derived in practice, not just on headline multiples, in See what the numbers say about this price — find out in our valuation breakdown.
Context on how ArcelorMittal’s current P/E stacks up visually against its sector and the market comes through clearly in the latest chart. This helps frame whether today’s premium looks stretched or simply aligned with its risk and return profile, in
Next Steps
If the mix of risks and rewards around ArcelorMittal feels finely balanced, now is the moment to test the numbers yourself and decide where you land. To weigh both sides in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond ArcelorMittal?
Do not stop at ArcelorMittal. Use the screener to quickly surface fresh ideas that match your risk comfort and return goals before the market moves on.
- Target resilient income with companies that prioritize dependable payouts by scanning a curated set of 222 dividend fortresses built to support long term cash returns.
- Hunt for quality at a discount by checking a focused group of 210 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect their financial profile.
- Prioritize capital preservation by reviewing a hand picked pool of 202 resilient stocks with low risk scores designed to keep overall risk scores on the lower side of your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com