


EN
ONEOK (OKE) Lifts Guidance After Strong Results But Is The Valuation Already Priced In
ONEOK (OKE) just posted third quarter results that show higher revenue and net income than a year earlier, and the company lifted its 2026 earnings guidance, putting fresh attention on the stock.
Even with the upgraded 2026 guidance, ONEOK’s recent trading tells a mixed story. The share price is down 7.07% over the past week and 6.05% over the last three months, yet the year to date share price return is 15.66% and the 1 year total shareholder return is 32.91%. This suggests longer term holders have seen momentum build even as short term sentiment cools around the latest move to US$85.98.
Scan how ONEOK compares with other midstream and energy plays showing strong cash generation and balance sheets through the list of solid balance sheet and fundamentals (25 results).
The latest jump in ONEOK’s earnings guidance landed just as the share price slipped back, raising a simple question: Are you seeing a business catching up to the valuation, or sentiment cooling ahead of the numbers?
Most Popular Narrative: 15% Undervalued
On the analyst consensus Narrative on Simply Wall St, ONEOK’s fair value sits at $101.50, compared with the latest close at $85.98. That gap frames the current pullback as a valuation question rather than just a mood swing.
The main thing that has to go right is that ONEOK successfully executes its Brazos Midland integration, planned Permian processing and takeaway expansions, and Texas City LPG export buildout while holding to its capital discipline framework and targeted leverage around 3.25x.
The current valuation implies that the market is not fully crediting ONEOK for its raised 2026 earnings and EBITDA guidance, the expected earnings and free cash flow accretion from Brazos at around a 6x to 7.5x EBITDA multiple, and the future uplift from the self amortizing Apollo interest that gradually increases the share of cash flows to common equity.
See why 84 investors see ONEOK as 15% undervalued.
Result: Fair Value of $101.50 (UNDERVALUED)
Still, the ONEOK narrative can crack if Natural Gas Pipelines deliver weaker spreads for longer or if Brazos Midland returns lag the extra Cassidy II spend.
Find out about the key risks to this ONEOK narrative.
Another View: ONEOK Through The P/E Lens
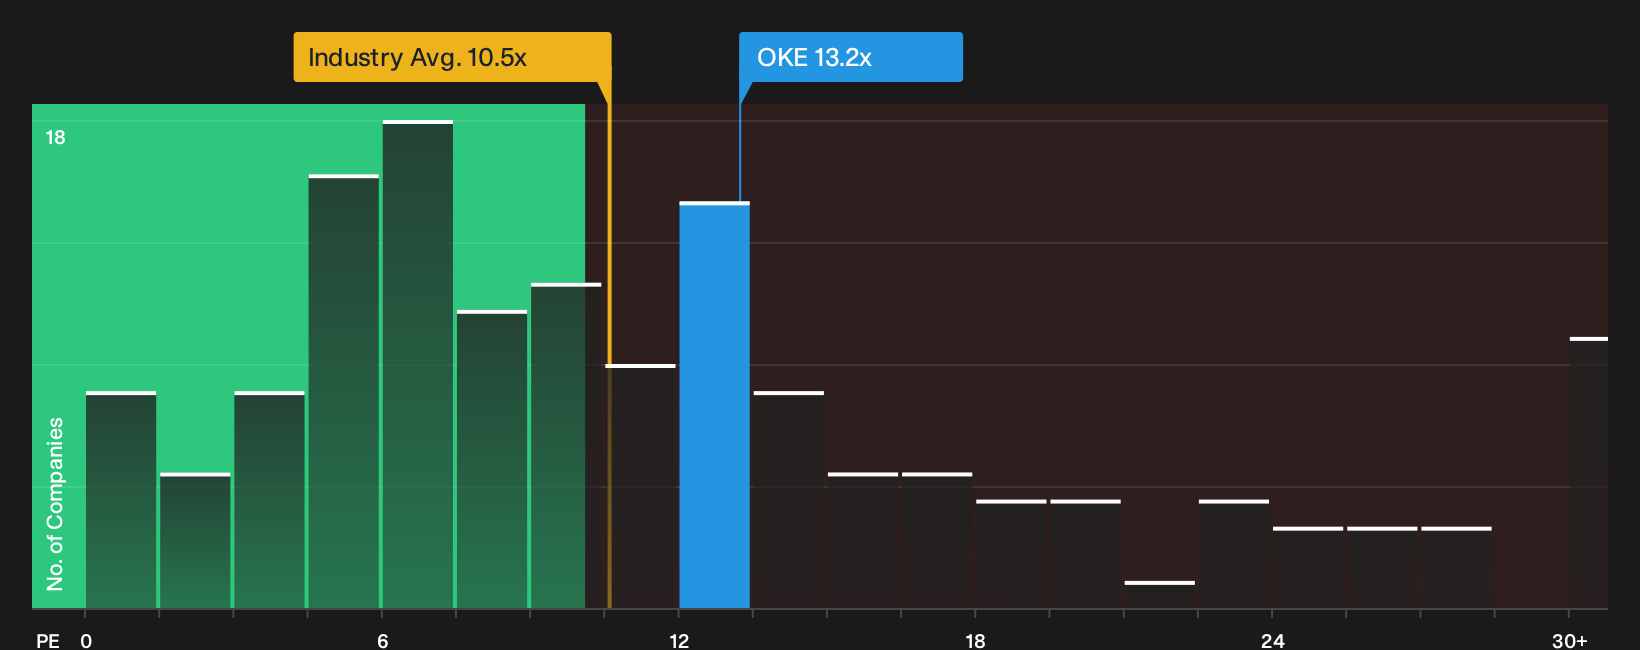
There is a very different message when ONEOK is viewed through its P/E ratio. The stock trades on 13.3x earnings, below the peer average of 17.3x, yet above the broader US Oil and Gas group at 10.5x. The fair ratio sits higher again at 19.4x. That mix of discount and premium raises a simple question: Is the market underestimating company specific strengths or already baking in the key risks?
See what the numbers say about this price in more detail through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on ONEOK can be a prompt or a distraction. If you want to move fast but think clearly, start by weighing both sides through the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond ONEOK?
If the ONEOK story has you thinking about what else might deserve a spot on your watchlist, use this momentum to widen your opportunity set with a few focused screens.
- Target resilient cash generators by scanning a 6 dividend fortresses that combine income potential with business models designed to keep paying through different market conditions.
- Hunt for mispriced opportunities by reviewing a curated 33 high quality undervalued stocks where strong fundamentals meet prices that do not fully reflect underlying business strength.
- Protect your downside by concentrating on a 30 resilient stocks with low risk scores focused on companies with steadier risk profiles that can help balance more volatile positions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com