


EN
Record Earnings Could Be A Game Changer For Texas Pacific Land (TPL)
- Texas Pacific Land reported record third quarter 2026 results, with revenue of US$273.39 million and net income of US$167.37 million, and declared a US$0.60 per share quarterly dividend payable in December 2026.
- Oil and gas royalty production, stronger natural gas price realizations, and a sharp jump in surface lease and materials revenue, together with incremental Midland Basin acreage acquisitions, highlight how Texas Pacific Land is converting its land position into higher cash generation while maintaining a net cash balance and no debt.
- This article will examine how Texas Pacific Land's record free cash flow and debt-free balance sheet relate to the existing investment narrative.
Scan beyond Texas Pacific Land and compare other asset rich, cash generative owners with strong balance sheets using our curated list of solid balance sheet and fundamentals (25 results).
Texas Pacific Land Investment Narrative Recap
To own Texas Pacific Land, you need to be comfortable with a concentrated bet on Permian activity and royalty cash flows, while the water and surface businesses add a second leg of income. The analyst consensus Narrative on Simply Wall St leans on ongoing earnings growth and very high margins. The latest quarter reinforces that the operating engine is working, so the near term story does not really change.
The key short term swing factor remains how operator activity and commodity prices feed through to royalty volumes and pricing. The biggest live risk is regulatory and environmental pressure on both Permian drilling and water usage in Texas, which could slow water services momentum and raise compliance costs even if the balance sheet stays clean.
The most relevant fresh data point is the record third quarter 2026 earnings print, with US$273.39 million of revenue and US$167.37 million of net income, plus record free cash flow and no debt. For a business built on royalties, water services, and fixed fee surface income, that combination supports the view that the current asset base is throwing off substantial cash.
That said, the same update also highlighted regulatory reviews that may delay some data center related projects on Texas Pacific Land acreage. Those assets sit inside the longer term catalyst bucket alongside transmission and industrial water opportunities. Any timing slippage is a reminder that while the core royalty and water operations are already scaled, newer monetization avenues still depend on permitting, infrastructure build out, and consistent execution.
Texas Pacific Land's analyst narrative centers on forecast revenue of US$1.3b and earnings of US$837.1 million by 2029. These projections are based on an assumed 17.2% yearly revenue growth and an earnings increase of about US$333.5 million from current earnings of US$503.6 million.
Uncover why Texas Pacific Land's fair value indicates a 60% potential upside to its current price, which could narrow quickly.
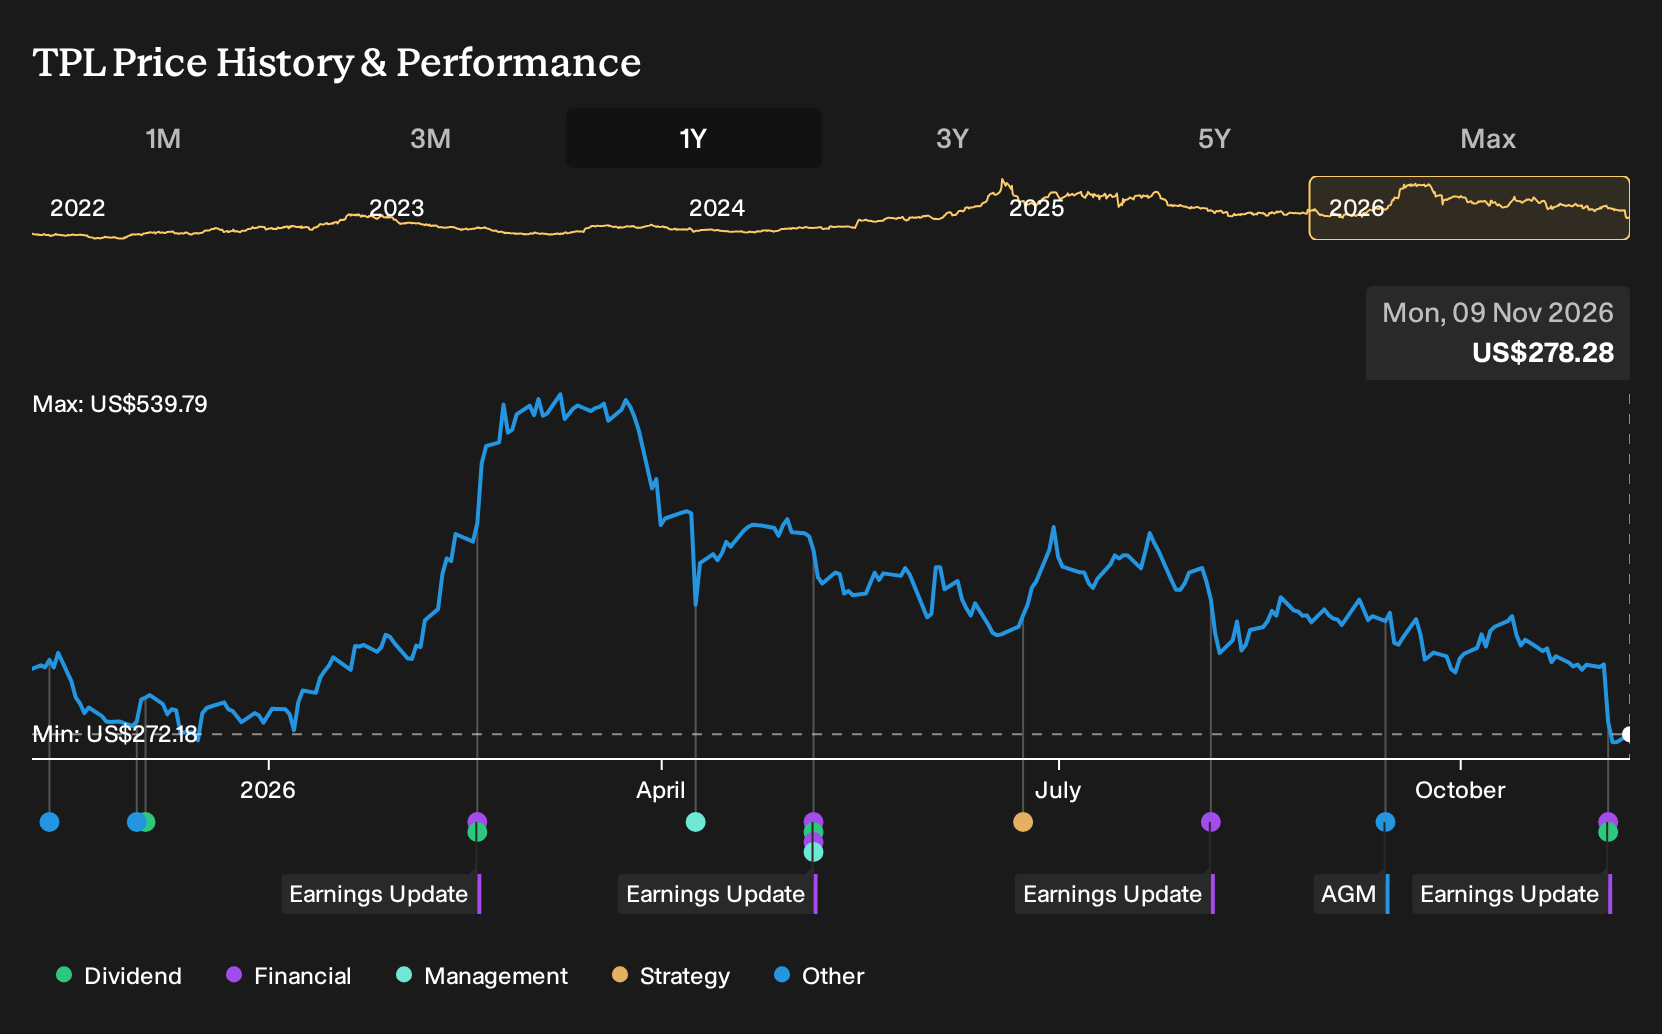
Exploring Other Perspectives
Here is where Texas Pacific Land looks different through the most pessimistic lens. The lowest analysts focus on the risk that big AI and power projects never fully materialize, even though they were assuming revenue of about US$1.5b and earnings near US$924.8 million by 2029 before this earnings surprise. That gap in expectations shows how widely opinions can diverge, so it makes sense to compare several narratives and see which one best matches your own view.
Explore 5 other Texas Pacific Land fair value estimates, including one that suggests as much as 11% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Texas Pacific Land research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Texas Pacific Land. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Texas Pacific Land's overall financial health at a glance.
Looking For More Investment Ideas Beyond Texas Pacific Land?
If Texas Pacific Land has sharpened your focus on resilient balance sheets and strong cash generation, it can be useful to broaden the watchlist with companies that share similar qualities but operate in very different niches. The Simply Wall St Screener helps you quickly filter the market down to a manageable set of stocks that line up with your own risk tolerance and return expectations.
- If capital preservation is a priority, start with businesses that score well on financial strength through our 30 resilient stocks with low risk scores to see which ones combine resilience with measured upside potential.
- For readers hunting for mispriced opportunities, check out companies flagged as attractively valued on fundamentals using the curated 33 high quality undervalued stocks to see which ideas deserve a closer look next.
- Income focused investors who care about both yield and staying power can scan for established payers supported by solid metrics through the targeted 6 dividend fortresses to line up candidates for deeper dividend research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com