


EN
How Investors May Respond To Bunge Global Stock Stronger Quarterly Earnings
- Bunge Global reported third quarter 2026 sales of US$23,804 million and net income of US$318 million, with basic earnings per share from continuing operations of US$1.65, compared with US$22,155 million, US$166 million and US$0.86 a year earlier.
- For the first nine months of 2026, Bunge Global's sales reached US$69,706 million with net income of US$1,064 million, and basic earnings per share from continuing operations that were higher than the prior year, highlighting how recent execution affected both revenue and per share results.
- Attention now turns to how Bunge Global's stronger quarterly earnings and higher year-to-date profitability interact with the existing investment narrative.
Scan beyond Bunge Global and line up other large, cash generating businesses using the hand picked list of solid balance sheet and fundamentals (25 results).
Bunge Global Investment Narrative Recap
Bunge Global appeals to investors who buy into a simple idea: a scaled agribusiness with processing, merchandising and food ingredients that can turn volume and integration into resilient earnings through cycles. The analyst consensus Narrative on Simply Wall St focuses on Viterra integration, crush expansions and renewable fuel demand as the key engines. The latest quarter shows the business still generating profit and per share earnings from that platform.
The more immediate swing factor remains how quickly weaker refined and specialty oils and grain merchandising can stabilise against that processing base. Third quarter and nine month earnings confirm the core engine is working, but they do not remove the risk from underperforming Grain Merchandising and Milling or from debt that is not yet well covered by operating cash flow.
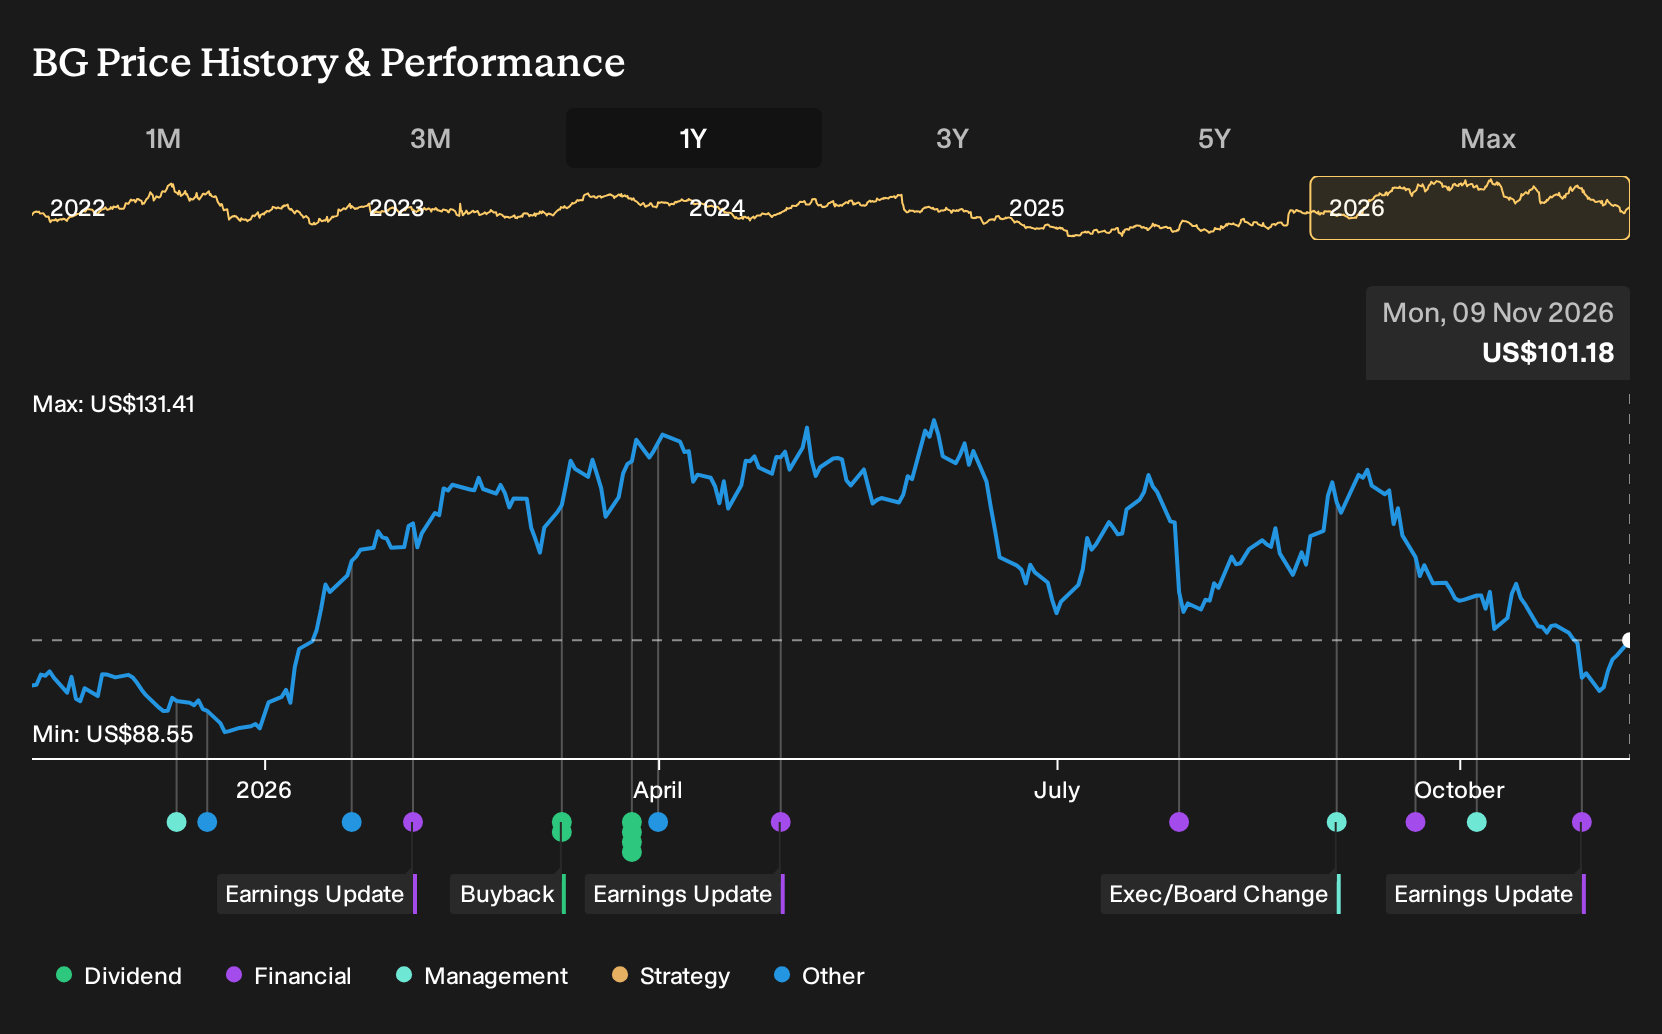
The fresh data point that matters most here is the third quarter and year to date 2026 earnings release on 29 October 2026. Sales of US$23,804 million and net income of US$318 million for the quarter, alongside US$69,706 million of revenue and US$1,064 million of profit over nine months, keep attention on execution rather than storytelling.
Compared with the existing catalysts around Viterra synergies and new capacity ramp ups, these figures give you something concrete to weigh. Stronger profitability per share supports the idea that integration and project spending are feeding through. At the same time, segment softness and leverage, already flagged as key risks, still sit in the background as constraints on how much this momentum can help Bunge Global in the near term.
Bunge Global's narrative projects US$95.3b revenue and US$3.4b earnings by 2029. This assumes 1.2% yearly revenue growth and an earnings increase of about US$2.4b from US$1.0b today.
Uncover how Bunge Global's fair value indicates a 40% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts anchor their story in Bunge Global’s renewable fuels partnerships in Brazil, which they saw as a key route to higher crush economics even before this earnings release. They were already modelling revenue of about US$106.7b and earnings of roughly US$3.5b by 2029. You can now weigh those pre news expectations against the latest profit print and decide which narrative feels closer to your own view, knowing both camps may rethink their forecasts after these results.
Explore 3 other Bunge Global fair value estimates, including one that suggests as much as 182% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bunge Global research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bunge Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bunge Global's overall financial health at a glance.
Looking For More Bunge Global Investment Ideas?
If this Bunge Global update has sharpened your view but you still want a broader watchlist, it can help to line up a few different types of opportunities side by side using the Simply Wall St Screener.
- If you are hunting for quality at a discount, start with a focused set of 33 high quality undervalued stocks that combine strong fundamentals with more modest price tags.
- For readers who care most about stability, filter for 30 resilient stocks with low risk scores that aim to keep balance sheets and volatility in check.
- If income is your priority, zero in on 6 dividend fortresses that offer higher yields while still aiming to keep payouts supported by underlying cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com