


EN
Profit Rebound Could Change The Case For Trekor Metals Stock
- Trekor Metals reported third quarter 2026 sales of C$342.22 million with net income of C$33.61 million, reversing a loss a year earlier and delivering C$0.09 in basic earnings per share from continuing operations.
- Across the first nine months of 2026, Trekor Metals generated C$909.87 million in sales and C$72.67 million in net income, reflecting the impact of higher output and operating leverage from Florence Copper and Gibraltar on the earnings profile.
- This raises the question of how Trekor Metals' investment narrative is affected by the sharp swing to profitability on significantly higher quarterly sales.
Trekor Metals Investment Narrative Recap
To own Trekor Metals, you need to be comfortable with a copper focused story built on Gibraltar and a ramping Florence Copper operation. The analyst consensus Narrative on Simply Wall St hinges on Florence eventually becoming a lower cost, higher volume asset. The latest swing back to profit, with C$72.67 million in nine month net income, supports that operating thesis but does not remove execution risk.
The main short term catalyst still sits with how reliably Florence can move toward higher output while Gibraltar manages cost pressure from diesel, explosives and ore mix. The biggest risk remains that Florence’s cost structure and volume ramp fall short of expectations, which could keep consolidated margins and debt reduction capacity under strain.
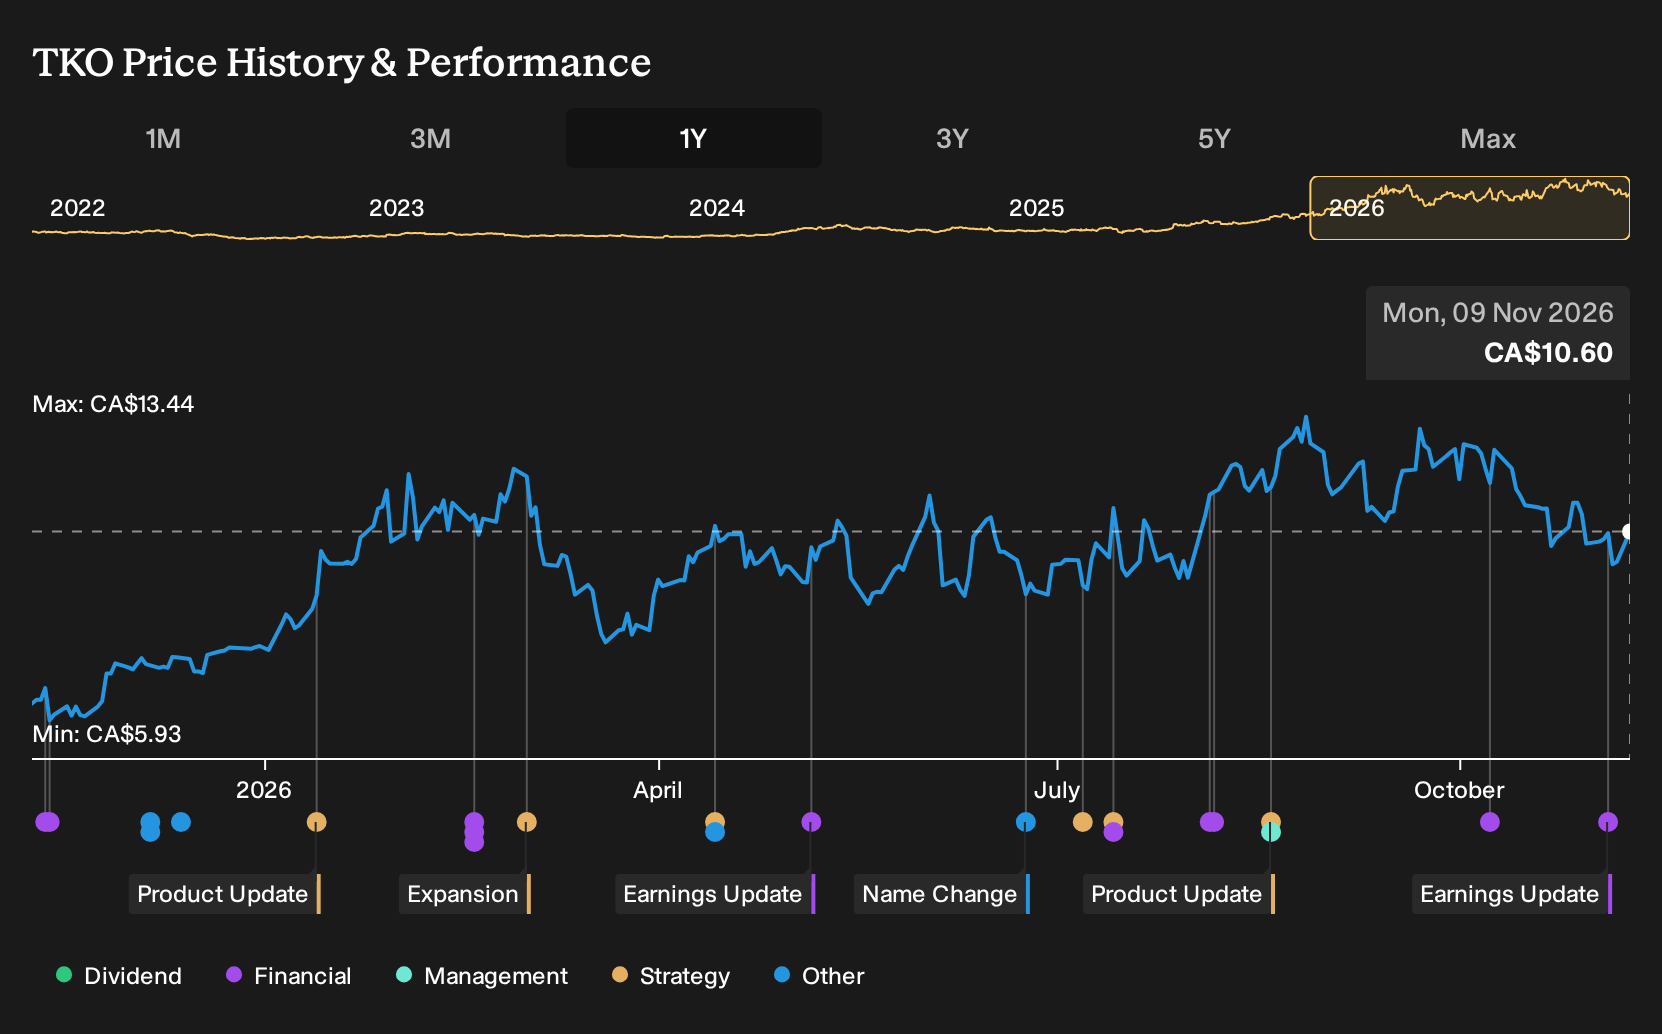
The most relevant recent announcement is Trekor Metals’ third quarter 2026 earnings release on November 4. Management reported C$342.22 million in quarterly sales and C$33.61 million in net income, after a loss a year earlier. That kind of inflection makes it easier for you to focus on whether current production assets are generating the cash required to support the balance sheet.
Those figures, alongside C$909.87 million in nine month revenue, tie directly into the catalysts in the analyst consensus Narrative on Simply Wall St that rely on improving operating leverage as Florence Copper and Gibraltar scale. The print also brings debt and cost risks into sharper focus, because a higher earnings base raises the bar for future quarters to support planned project spending at Yellowhead and Aley.
Trekor Metals’ current earnings are reported at CA$15.7 million, with analyst consensus pointing to CA$450.9 million of earnings on CA$1.6b of revenue by 2029, which implies forecast revenue growth of 16.9% a year and an earnings increase of roughly 29 times today’s level.
Uncover why Trekor Metals' fair value indicates a 38% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Trekor Metals leans hard into Florence Copper ramp up risk. The most cautious analysts were only pencilling in around C$1.1b of revenue and C$519.8 million of earnings by 2029 before this earnings release. That is a far more pessimistic story than the consensus, so treat this quarter as a fresh data point that could shift both narratives and explore the full range of estimates for yourself.
Explore 4 other Trekor Metals fair value estimates, including one that suggests it could be worth just CA$13.50!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your Trekor Metals research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Trekor Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trekor Metals' overall financial health at a glance.
Looking for more investment ideas beyond Trekor Metals?
If Trekor Metals has sharpened your focus on where to put fresh capital to work, it can help to scan a broader watchlist built around clear financial filters. The Simply Wall St Screener lets you filter for balance sheet strength, income potential, or mispriced quality so you can build a shortlist that fits your own risk and return preferences.
- For investors who care most about staying on the front foot with risk, start with companies that score well on stability using a 9 resilient stocks with low risk scores.
- If dependable income is your priority, concentrate on businesses with robust yields and resilient payouts by reviewing a curated 3 dividend fortresses.
- To look for quality that the market might be overlooking, focus on fundamentally strong opportunities using a targeted 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com