


EN
How Weaker Q3 Earnings At Fairfax Financial Holdings (TSX:FFH) Has Changed Its Investment Story
- Fairfax Financial Holdings reported Q3 2026 net income of US$929.6 million, with basic EPS from continuing operations at US$46.45 and diluted EPS at US$43.32, compared with higher levels a year earlier.
- The business also detailed nine month 2026 net income of US$3,018 million and continued to deploy capital through fixed income offerings and share repurchases, underscoring an ongoing balance between funding growth and returning cash to investors.
- Investors will now be watching how Fairfax Financial Holdings' softer Q3 earnings per share figures could influence the investment narrative built around underwriting discipline and investment income.
Compare Fairfax Financial Holdings' latest bond moves and buybacks with a curated set of resilient balance sheet plays by scanning our list of solid balance sheet and fundamentals (5 results) for potential ideas in the same vein.
Fairfax Financial Holdings Investment Narrative Recap
To own Fairfax Financial Holdings, you need to be comfortable with a business that leans heavily on investment income and associate earnings while trying to keep underwriting tight. The analyst consensus Narrative on Simply Wall St already factors in softer profit expectations over the next few years, so the latest dip in quarterly EPS mainly reinforces that cautious earnings path rather than changing it.
The more immediate swing factor remains execution on big capital commitments like IDBI Bank and Boots while keeping combined ratios under control. The fresh fixed income offerings and ongoing buyback program adjust the funding mix but do not materially shift that central risk, which is earnings volatility from large, non insurance exposures.
The CAD 350m and CAD 300m senior fixed rate note offerings announced in early November are the clearest operational link to this story right now. Fresh long dated funding can influence how Fairfax Financial Holdings supports its insurance balance sheet and finances associate investments, in turn affecting flexibility around underwriting capacity and deal timing.
For you as a shareholder, that financing step connects directly to the same catalysts that analysts have been watching. Stable interest income from Fairfax Financial Holdings’ sizeable bond portfolio and disciplined insurance results already underpin the narrative. The new bonds add another layer of term funding, and the main execution risk still sits with how efficiently that capital is put to work in associates and the core underwriting engine.
Fairfax Financial Holdings’ current earnings of $4.4b are expected to decline to $2.6b by the 2029 forecast year, with analysts projecting revenue of $44.6b by 2029 and assuming 4.8% yearly revenue growth. This implies an earnings decrease of $1.8b from earnings today to the consensus estimate.
Uncover why Fairfax Financial Holdings' fair value indicates that Fairfax Financial Holdings is in line with its current price.
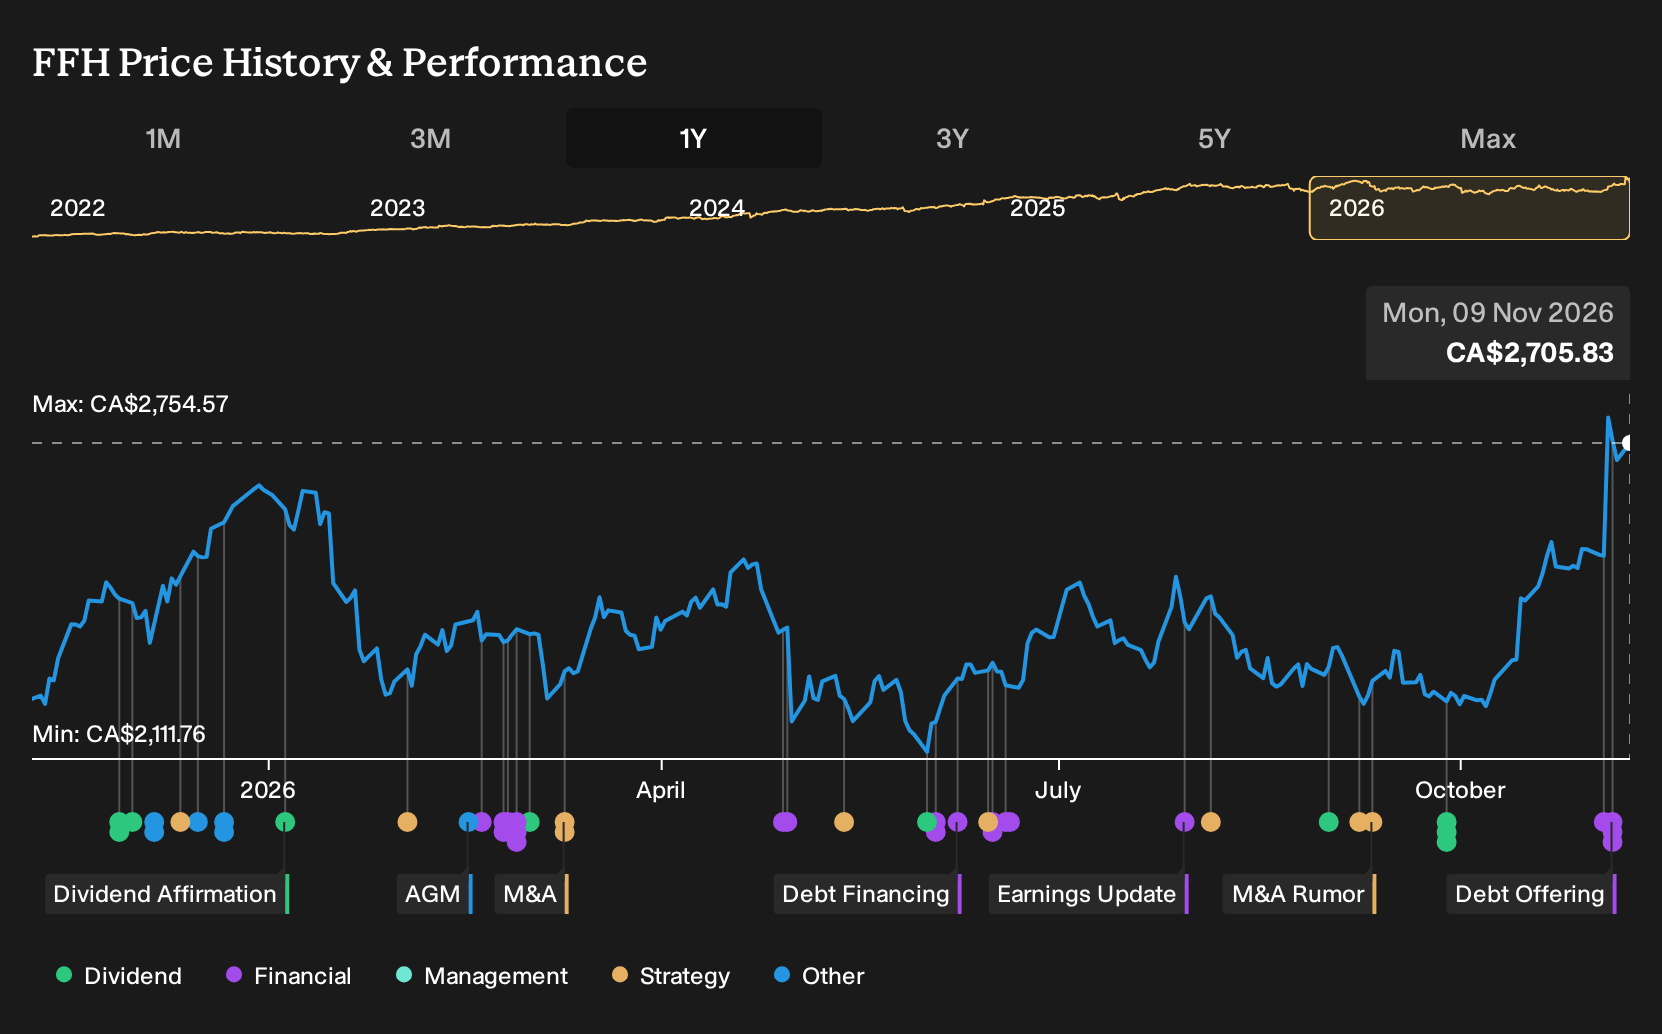
Exploring Other Perspectives
One alternate view focuses less on Fairfax Financial Holdings’ underwriting and more on balance sheet strain. The most pessimistic analysts were already building in roughly US$45.1b of 2029 revenue and about US$3.0b of earnings before this Q3 update, and they see limited room if new debt or bond issuance tightens flexibility. Consider that as a prompt to compare several narratives rather than rely on just one.
Explore 3 other Fairfax Financial Holdings fair value estimates, including one that suggests it could be worth just CA$2742.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Fairfax Financial Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fairfax Financial Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fairfax Financial Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Fairfax Financial Holdings?
Once you have formed a view on Fairfax Financial Holdings, it often helps to widen the lens and compare it with other businesses that share similar qualities or offer a very different risk profile. The Simply Wall St Screener can surface a range of companies that match the type of portfolio balance you are aiming for.
- If you want potential upside with tighter financial foundations, scan a curated 15 elite penny stocks with strong financials that already pass basic balance sheet and quality filters.
- For investors who prefer a margin of safety, filter for businesses on our 6 high quality undervalued stocks that combine solid fundamentals with what may be conservative market expectations.
- If resilience and capital preservation sit higher on your list, focus on stocks highlighted in the 9 resilient stocks with low risk scores which emphasize stronger financial health and lower measured risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com