


EN
Cryoport (CYRX) Lifts 2026 Outlook Following Revenue Update As Fair Value Stays Just Behind
Cryoport (CYRX) moved after issuing raised full year 2026 revenue guidance of US$197 million to US$199 million and posting third quarter revenue of US$50.22 million with continued net losses.
The raised 2026 guidance and third quarter revenue update came after a strong run in Cryoport’s share price, with a 1-day share price return of 7.17% on the latest move, a 90-day share price return of 36.92%, and a year-to-date share price return of 114.12%. The 1-year total shareholder return is 139.70%, even though the 5-year total shareholder return is down 73.40%, suggesting momentum has recently picked up despite a much weaker long-run record.
Spot fresh momentum stories like Cryoport alongside other potential breakouts in temperature controlled logistics and life sciences by scanning our hand picked 19 high quality undiscovered gems.Bulls see Cryoport’s recent surge and higher 2026 revenue guide as proof the story is turning, while bears point to ongoing losses and a weak 5 year record. Which side does the current valuation support?
Most Popular Narrative: 3% Overvalued
Cryoport closed at $20.47 against a narrative fair value of $19.78, so the analyst consensus Narrative on Simply Wall St currently sees the shares a touch ahead of that estimate, with the gap hinging on how its cell and gene therapy footprint converts into richer services over time.
The main factor that has to go right is that Cryoport continues to convert its broad clinical trial base and expanding global facilities and partnerships into higher margin commercial services and integrated, end-to-end platform usage.
The current valuation implies the market is not fully accounting for Cryoport's delivery of revenue above prior guidance, progress toward positive adjusted EBITDA, and an increasing mix of commercial cell and gene therapy revenue, which is why this narrative views the stock as undervalued and maintains a positive outlook.
See why 5 investors see Cryoport as 3% overvalued.
Result: Fair Value of $19.78 (OVERVALUED)
Still, Cryoport’s dependence on a relatively small pool of commercial therapies and its exposure to regulatory and trial rule changes could quickly upset this upbeat narrative.
Find out about the key risks to this Cryoport narrative.
Another Take On Cryoport’s Valuation
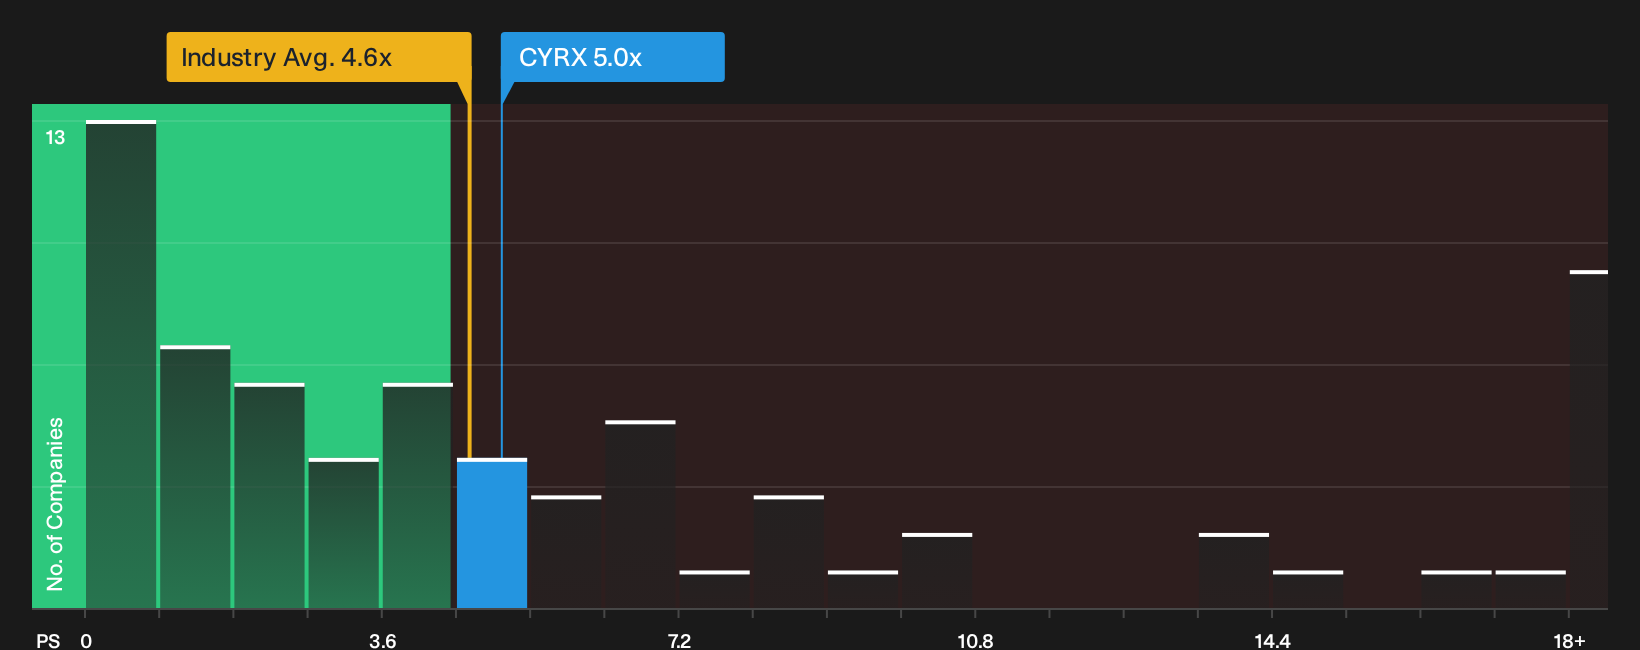
The analyst narrative pegs Cryoport’s fair value at $19.78, only slightly below the $20.47 share price. A different lens tells a sharper story. On a P/S of 5.4x, the stock trades richer than the US Life Sciences industry at 4.6x and above its own 3.1x fair ratio, which points to less room for error if sentiment cools.
To see how that pricing gap might close over time and what the numbers say about this setup, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Cryoport’s story so far. If you want to move fast and make up your own mind, start with the 1 key reward and 1 important warning sign
Looking For More Investment Ideas Beyond Cryoport?
If Cryoport has your attention, do not stop here. Broaden your watchlist with a few targeted hunting grounds that can surface fresh opportunities fast.
- Target resilient balance sheets and steadier fundamentals by running a focused search through our list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispriced quality by scanning companies flagged in our 33 high quality undervalued stocks.
- Explore opportunities that include cash payouts by filtering using our 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com