


EN
Does Lowered 2026 Guidance Change The Bull Case For Oshkosh Stock?
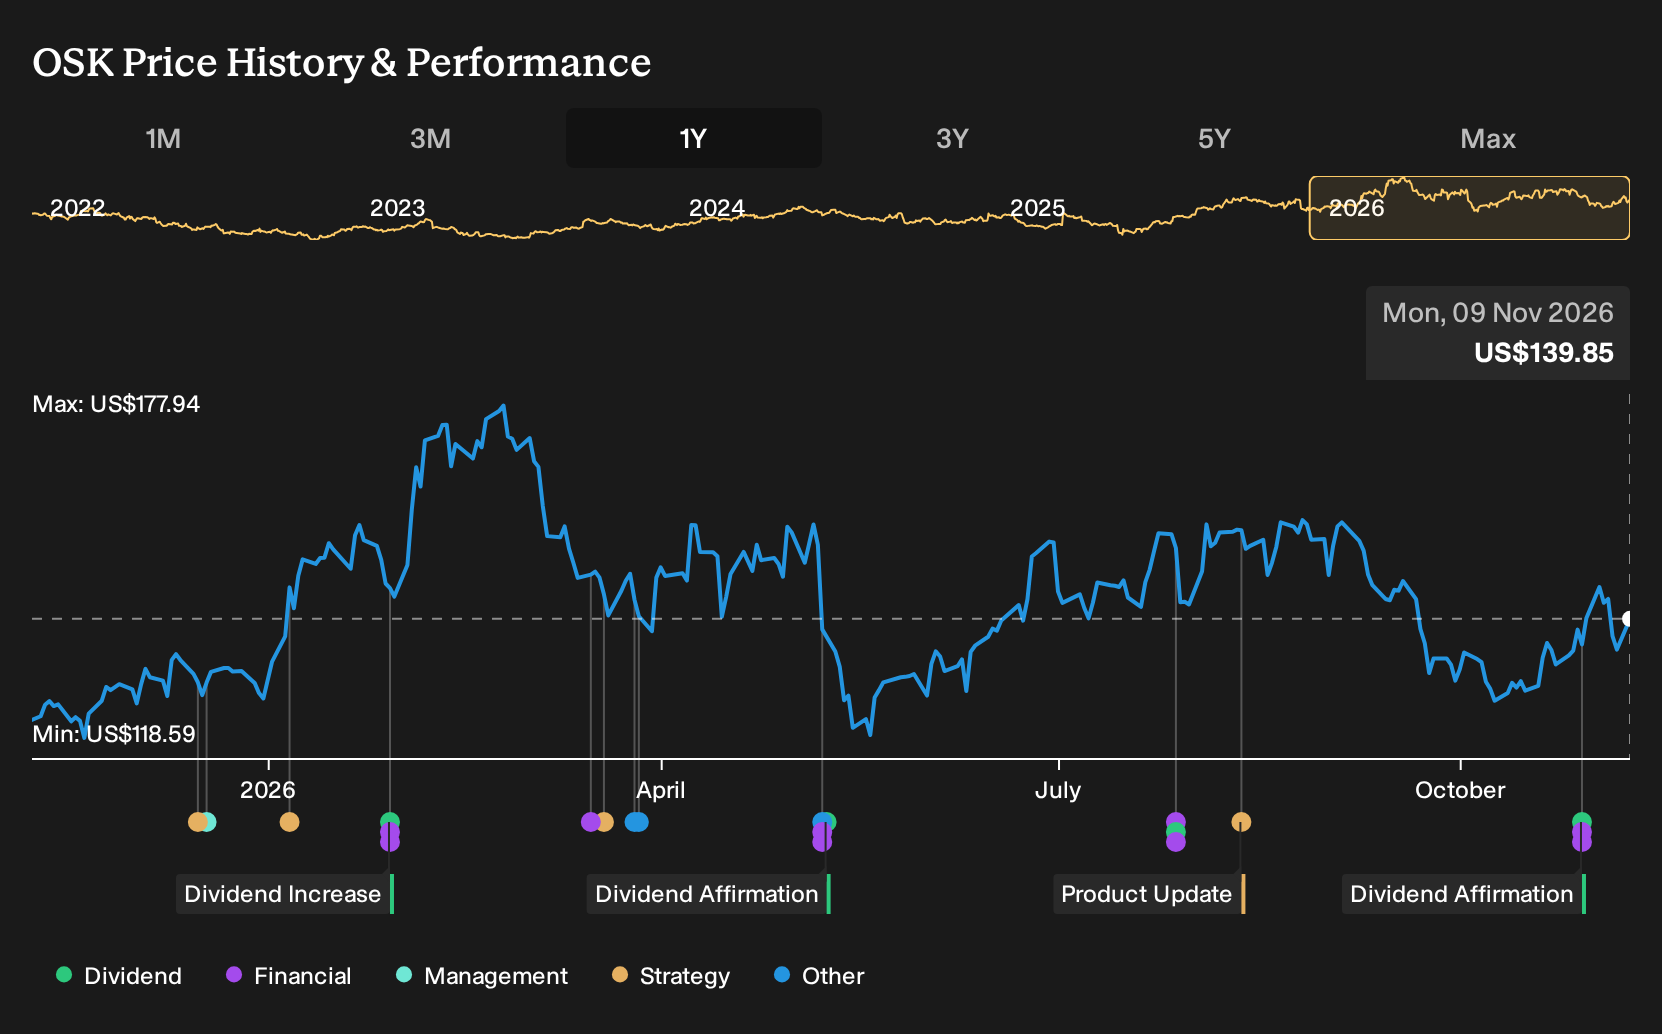
- Oshkosh reported third quarter 2026 sales of US$2,841.6 million and net income of US$138.4 million, while the board affirmed a quarterly dividend of US$0.57 per share payable on November 30, 2026, to holders on November 16.
- The revised 2026 guidance, which now assumes diluted EPS of US$8.00 to US$9.00 and about US$11.0 billion in net sales, highlights pressure from lower fire apparatus and NGDV production, while higher volume in the Access segment is expected to provide some offset.
- Investors may now consider how Oshkosh's longer term investment narrative aligns with this cut to 2026 earnings guidance and segment production expectations.
Compare Oshkosh's guidance reset and dividend decision with other industrial peers by scanning a curated set of list of solid balance sheet and fundamentals (25 results) for potential alternatives.
Oshkosh Investment Narrative Recap
To stay invested in Oshkosh, you need to be comfortable with a story built around large infrastructure demand, Access segment momentum and multi year government programs. The analyst consensus Narrative on Simply Wall St leans on execution in fire apparatus and NGDV as key levers for margins. The lowered 2026 outlook signals that these levers are under near term pressure, rather than broken.
The most immediate swing factor is whether Oshkosh can translate its Access backlog into consistent, profitable throughput while ironing out production issues in Vocational and Transport. The biggest risk is further disruption or timing changes in large government vehicle programs, together with ongoing sensitivity to tariffs in Access and Transport.
The guidance cut to US$8.00 to US$9.00 in diluted EPS for 2026, tied to lower fire apparatus and NGDV output, sits at the center of this story. That update directly touches the same catalysts analysts focus on, including manufacturing improvements at Pierce and the USPS next generation delivery vehicle program, so it matters for how you frame execution risk.
Dividend affirmation at US$0.57 per share, payable on November 30, 2026, gives you a data point on how Oshkosh is balancing cash returns with a year where earnings guidance has moved down. For income oriented holders, that payout sits alongside the current 1.63% yield profile and keeps the capital return framework mentioned in the analyst consensus Narrative on Simply Wall St in clear view.
Oshkosh's narrative projects US$12.9b revenue and US$1.1b earnings by 2029. This assumes 6.7% yearly revenue growth and an earnings increase of about US$544m from current earnings of US$556.3m.
Uncover why Oshkosh's fair value indicates a 17% potential upside to its current price before that discount to Oshkosh's narrative closes.
Exploring Other Perspectives
One alternate view leans hard on Oshkosh’s free cash flow potential. The most optimistic analysts were modelling revenue of about US$13.6b and earnings of roughly US$1.3b by 2029, well above consensus. You can use the guidance cut and dividend affirmation as a test of whether that richer cash flow story still feels realistic to you.
Explore 3 other Oshkosh fair value estimates, including one that suggests as much as 40% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Oshkosh research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Oshkosh. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Oshkosh's overall financial health at a glance.
Looking for more Oshkosh-sized investment ideas?
Once you have formed a view on Oshkosh, it can help to pressure test that thesis against other companies with different balance sheets, cash flow profiles and dividend approaches using the Simply Wall St Screener.
- Prioritize resilience by scanning a 30 resilient stocks with low risk scores that score well on financial strength and business stability.
- If income is your focus, compare Oshkosh's payout with a curated set of 6 dividend fortresses that pair higher yields with supporting fundamentals.
- For investors looking for new ideas, broaden your watchlist with a 19 high quality undiscovered gems that combine quality metrics with less widely followed tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com