


EN
Is Pinnacle West Capital (PNW) Fairly Valued Following Its Earnings Beat And Higher 2026 Outlook?
Pinnacle West Capital earnings beat and higher 2026 outlook
Pinnacle West Capital (PNW) reported third quarter results with higher sales, net income and earnings per share compared with a year earlier, and also raised its 2026 diluted EPS guidance range to US$5.05 to US$5.25.
The latest earnings beat and raised 2026 guidance appear to be feeding into renewed momentum in Pinnacle West Capital, with a 30 day share price return of 6.41% and a year to date share price gain of 19.42% at a recent price of US$105.26. Longer horizon investors have seen a 5 year total shareholder return of 97.90%, reflecting both price moves and reinvested dividends.
Scan how Pinnacle West Capital compares with other regulated utilities that show solid financial profiles using our curated list of list of solid balance sheet and fundamentals (25 results).
Pinnacle West Capital has rallied on stronger earnings and higher 2026 guidance, yet still trades only a touch below analyst targets. Is that tiny discount signaling caution that is justified by the valuation math?
Most Popular Narrative: 0% Overvalued
The analyst consensus Narrative on Simply Wall St puts Pinnacle West Capital’s fair value at $104.97, almost identical to the recent $105.26 share price. This frames the latest 2026 guidance upgrade against expectations that are already built into the stock.
The multi year capital program of about US$7.95b for 2026 to 2028, including higher transmission spend and new gas capacity such as the Redhawk expansion, Agave, Ironwood, Sundance and the planned Cholla gas conversion, is set to increase the regulated asset base and future revenue.
Growing transmission investment, including the potential multi hundred mile Four Corners to Cholla line that could approach US$1b and is recovered through a FERC formula rate with annual true ups, creates an additional earnings stream that can support both revenue and net margins over time.
See why 12 investors see Pinnacle West Capital as 0% overvalued.
Result: Fair Value of $104.97 (ABOUT RIGHT)
Still, heavier spending funded with more debt and equity, along with the ongoing reliance on gas and coal assets, could pressure returns if assumptions prove too optimistic.
Find out about the key risks to this Pinnacle West Capital narrative.
Another View: What P/E Says About Pinnacle West Capital
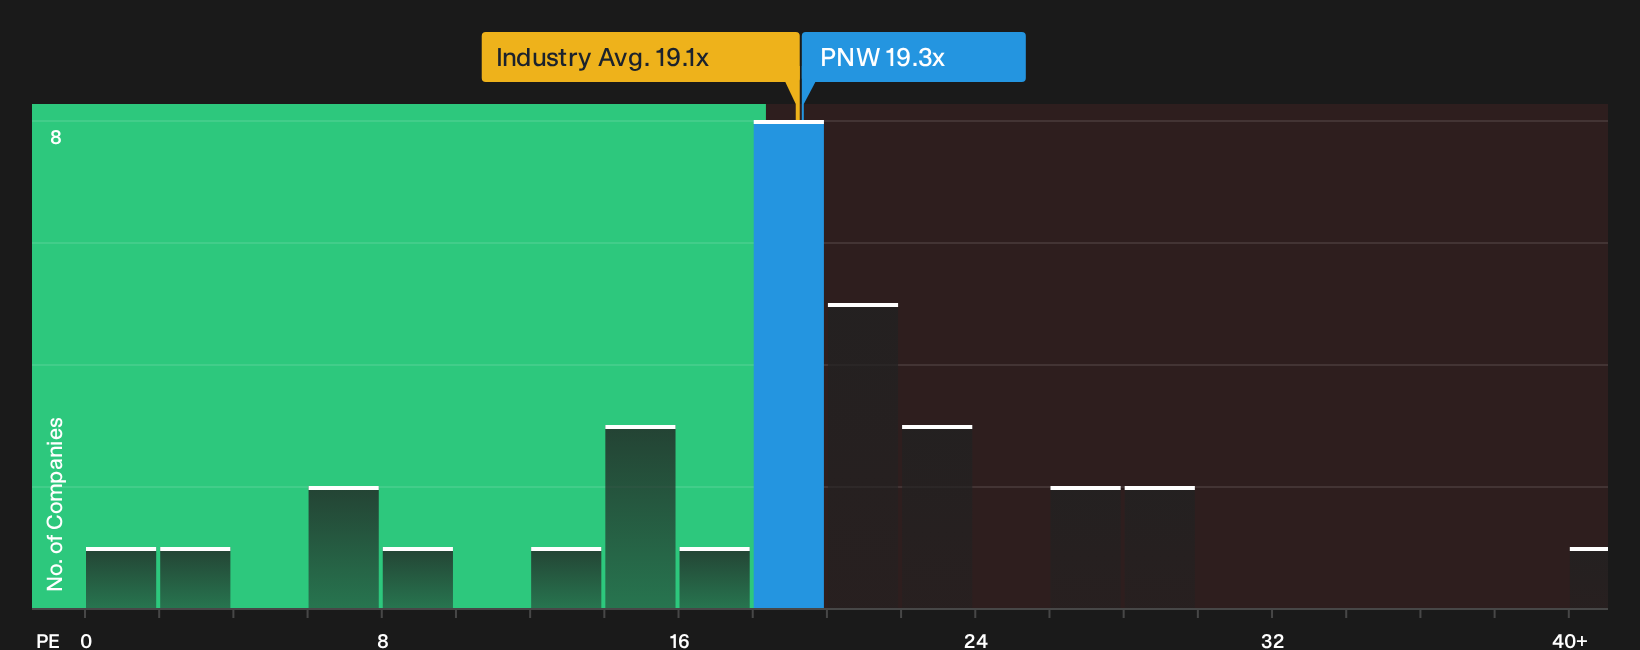
Moving away from intrinsic value estimates, the simple P/E snapshot paints a slightly different picture for Pinnacle West Capital. The stock trades on 19.3x earnings, a touch below its peer group at 22.2x, yet a little above the broader US Electric Utilities industry at 19.1x.
The fair ratio for Pinnacle West Capital sits at 19.8x, only modestly higher than today’s multiple. That narrow gap suggests limited room for error. If earnings or sentiment soften, does the market lean toward the cheaper industry level or drift closer to the fair ratio the model points to?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Pinnacle West Capital can create a lot of noise, so move quickly from headline impressions to hard data. Compare the potential upside with the red flags in one place with 2 key rewards and 2 important warning signs.
Looking for more Pinnacle West Capital style ideas?
If Pinnacle West Capital feels fairly priced to you, do not stop here. Fresh opportunities often sit just outside the obvious tickers you already follow.
- Target resilient potential by narrowing in on companies with stronger balance sheets and cleaner fundamentals through our focused list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities where quality and valuation line up by scanning our curated set of 33 high quality undervalued stocks.
- Build your income stream more deliberately by zeroing in on companies that behave like cash machines using our hand picked pool of 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com